About the Report
Base Year 2024Qatar District Cooling Plant Construction Market Overview
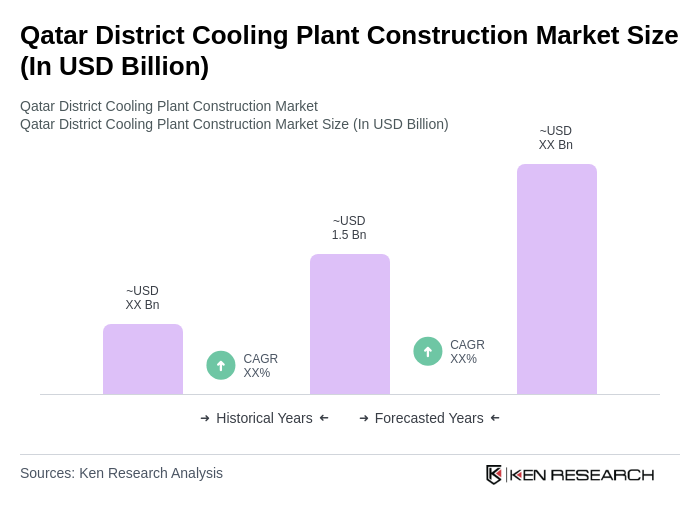
- The Qatar District Cooling Plant Construction Market is valued at USD 1.5 billion, based on a five-year historical analysis. This growth is primarily driven by the increasing demand for energy-efficient cooling solutions in urban areas, coupled with the rapid expansion of infrastructure projects in the region. The focus on sustainability and reduced carbon emissions has further propelled investments in district cooling technologies.
- Key players in this market include Doha, Al Rayyan, and Lusail, which dominate due to their strategic urban development plans and significant investments in infrastructure. The concentration of commercial and residential projects in these cities has created a robust demand for district cooling systems, making them pivotal in the market landscape.
- In 2023, the Qatari government implemented regulations mandating the use of district cooling systems in new developments, aiming to enhance energy efficiency and reduce peak electricity demand. This regulation is part of Qatar's broader strategy to promote sustainable urban development and align with its National Vision 2030 goals.
Qatar District Cooling Plant Construction Market Segmentation
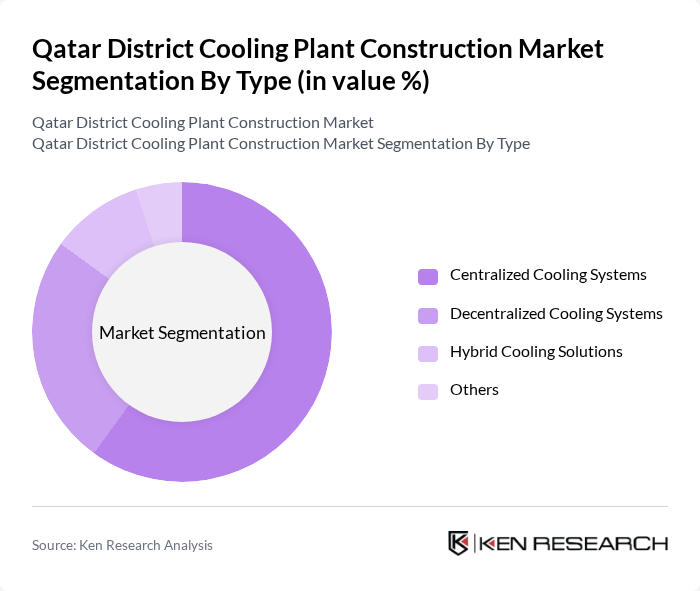
By Type:The market is segmented into various types of cooling systems, including centralized cooling systems, decentralized cooling systems, hybrid cooling solutions, and others. Centralized cooling systems are currently the most dominant segment due to their efficiency and ability to serve large areas, making them ideal for urban developments. Decentralized systems are gaining traction in smaller projects, while hybrid solutions are being explored for their flexibility and adaptability to different environments.
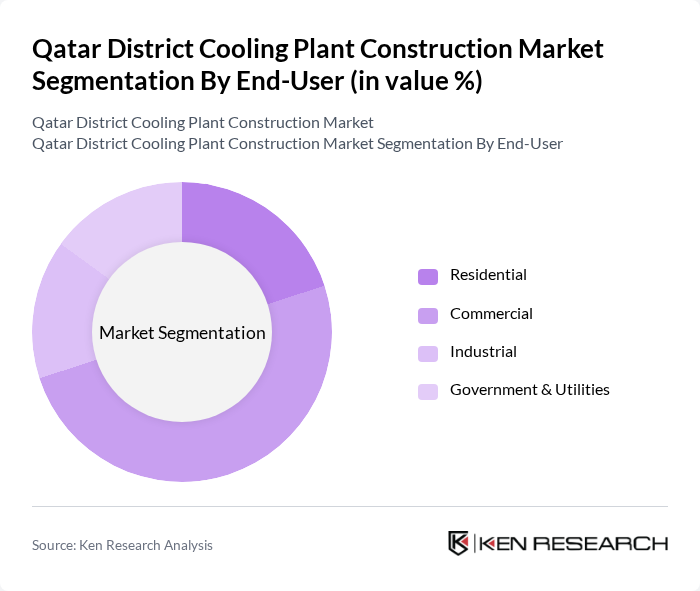
By End-User:The end-user segmentation includes residential, commercial, industrial, and government & utilities sectors. The commercial segment leads the market, driven by the rapid growth of office spaces, shopping malls, and hotels in urban areas. Residential projects are also significant, particularly in new developments, while industrial applications are expanding as companies seek energy-efficient solutions. Government initiatives further support the adoption of district cooling in public utilities.
Qatar District Cooling Plant Construction Market Competitive Landscape
The Qatar District Cooling Plant Construction Market is characterized by a dynamic mix of regional and international players. Leading participants such as Qatar Cool, Empower, Tabreed, Veolia, National Central Cooling Company, Qatari Diar, Al-Futtaim Engineering, Gulf District Cooling, Dalkia, Siemens, Engie, Abu Dhabi National Energy Company (TAQA), Mott MacDonald, Kahramaa, Qatar University contribute to innovation, geographic expansion, and service delivery in this space.
Qatar District Cooling Plant Construction Market Industry Analysis
Growth Drivers
- Increasing Demand for Energy Efficiency:The Qatar government aims to reduce energy consumption by 30% by 2030, driving the need for energy-efficient cooling solutions. The district cooling market is projected to save approximately 1.5 million MWh annually, translating to a reduction of around 1.2 million tons of CO2 emissions. This aligns with Qatar's National Vision 2030, which emphasizes sustainable development and energy efficiency as key priorities for urban infrastructure.
- Government Initiatives for Sustainable Development:Qatar's government has allocated over $200 billion for infrastructure projects, including sustainable cooling systems. The Qatar National Development Strategy 2018-2022 promotes the adoption of district cooling technologies, which are expected to account for 40% of the cooling market by 2024. This commitment to sustainability is further supported by the Qatar Green Building Council, which encourages energy-efficient construction practices.
- Urbanization and Infrastructure Development:Qatar's urban population is projected to reach 2.8 million in the future, necessitating efficient cooling solutions for residential and commercial buildings. The ongoing construction of mega-projects, such as Lusail City, is expected to increase the demand for district cooling systems significantly. With over 1.5 million square meters of new developments planned, the district cooling market is poised for substantial growth in response to urbanization trends.
Market Challenges
- High Initial Capital Investment:The upfront costs associated with district cooling plants can exceed $1 million per megawatt of cooling capacity. This high capital investment poses a significant barrier for new entrants and existing players looking to expand. Additionally, the long payback period, often ranging from 7 to 10 years, can deter potential investors, especially in a competitive market with alternative cooling solutions available.
- Regulatory Compliance and Bureaucracy:Navigating the regulatory landscape in Qatar can be challenging, with multiple agencies involved in the approval process for district cooling projects. Compliance with stringent environmental regulations and building codes can lead to delays and increased costs. In the future, the average time for project approvals is expected to be reported at 12 months, which can hinder timely market entry and project execution for developers.
Qatar District Cooling Plant Construction Market Future Outlook
The future of the Qatar district cooling market appears promising, driven by increasing urbanization and a strong governmental push towards sustainable infrastructure. As the population grows, the demand for efficient cooling solutions will rise, particularly in new developments. Furthermore, advancements in technology, such as IoT integration, will enhance operational efficiency and reduce costs, making district cooling more attractive to developers and end-users alike. The market is expected to evolve significantly, adapting to emerging trends and consumer needs.
Market Opportunities
- Expansion of Smart City Projects:Qatar's investment in smart city initiatives, with over $50 billion allocated, presents a significant opportunity for district cooling systems. These projects aim to integrate advanced technologies, enhancing energy efficiency and sustainability. The demand for innovative cooling solutions in smart cities is expected to grow, creating a favorable environment for district cooling providers.
- Integration of Renewable Energy Sources:The Qatar government aims to generate 20% of its energy from renewable sources by 2030. This shift presents an opportunity for district cooling systems to incorporate solar and other renewable energy technologies, reducing operational costs and enhancing sustainability. The integration of renewables can also improve the overall efficiency of cooling systems, making them more appealing to environmentally conscious consumers.
Scope of the Report
| Segment | Sub-Segments |
|---|---|
| By Type | Centralized Cooling Systems Decentralized Cooling Systems Hybrid Cooling Solutions Others |
| By End-User | Residential Commercial Industrial Government & Utilities |
| By Application | District Cooling Networks Standalone Cooling Plants Mixed-Use Developments Others |
| By Investment Source | Domestic Investment Foreign Direct Investment (FDI) Public-Private Partnerships (PPP) Government Schemes |
| By Policy Support | Subsidies Tax Exemptions Renewable Energy Certificates (RECs) Others |
| By Distribution Mode | Direct Sales Distributors Online Sales Others |
| By Price Range | Budget Mid-Range Premium Others |
Key Target Audience
Investors and Venture Capitalist Firms
Government and Regulatory Bodies (e.g., Qatar Ministry of Municipality and Environment)
Developers and Real Estate Companies
Utility Companies
Construction and Engineering Firms
Environmental Agencies (e.g., Qatar Environmental Regulatory Authority)
Energy Management Companies
Local Municipalities and Urban Planning Authorities
Players Mentioned in the Report:
Qatar Cool
Empower
Tabreed
Veolia
National Central Cooling Company
Qatari Diar
Al-Futtaim Engineering
Gulf District Cooling
Dalkia
Siemens
Engie
Abu Dhabi National Energy Company (TAQA)
Mott MacDonald
Kahramaa
Qatar University
Table of Contents
Market Assessment Phase
1. Executive Summary and Approach
2. Qatar District Cooling Plant Construction Market Overview
2.1 Key Insights and Strategic Recommendations
2.2 Qatar District Cooling Plant Construction Market Overview
2.3 Definition and Scope
2.4 Evolution of Market Ecosystem
2.5 Timeline of Key Regulatory Milestones
2.6 Value Chain & Stakeholder Mapping
2.7 Business Cycle Analysis
2.8 Policy & Incentive Landscape
3. Qatar District Cooling Plant Construction Market Analysis
3.1 Growth Drivers
3.1.1 Increasing Demand for Energy Efficiency
3.1.2 Government Initiatives for Sustainable Development
3.1.3 Urbanization and Infrastructure Development
3.1.4 Technological Advancements in Cooling Systems
3.2 Market Challenges
3.2.1 High Initial Capital Investment
3.2.2 Regulatory Compliance and Bureaucracy
3.2.3 Competition from Traditional Cooling Methods
3.2.4 Limited Awareness Among End-Users
3.3 Market Opportunities
3.3.1 Expansion of Smart City Projects
3.3.2 Integration of Renewable Energy Sources
3.3.3 Partnerships with Real Estate Developers
3.3.4 Growth in Green Building Certifications
3.4 Market Trends
3.4.1 Shift Towards Decentralized Cooling Solutions
3.4.2 Adoption of IoT in Cooling Systems
3.4.3 Focus on Sustainability and Carbon Reduction
3.4.4 Increasing Investment in Infrastructure Projects
3.5 Government Regulation
3.5.1 Energy Efficiency Standards
3.5.2 Environmental Impact Assessments
3.5.3 Incentives for Renewable Energy Integration
3.5.4 Building Code Compliance Requirements
4. SWOT Analysis
5. Stakeholder Analysis
6. Porter's Five Forces Analysis
7. Qatar District Cooling Plant Construction Market Market Size, 2019-2024
7.1 By Value
7.2 By Volume
7.3 By Average Selling Price
8. Qatar District Cooling Plant Construction Market Segmentation
8.1 By Type
8.1.1 Centralized Cooling Systems
8.1.2 Decentralized Cooling Systems
8.1.3 Hybrid Cooling Solutions
8.1.4 Others
8.2 By End-User
8.2.1 Residential
8.2.2 Commercial
8.2.3 Industrial
8.2.4 Government & Utilities
8.3 By Application
8.3.1 District Cooling Networks
8.3.2 Standalone Cooling Plants
8.3.3 Mixed-Use Developments
8.3.4 Others
8.4 By Investment Source
8.4.1 Domestic Investment
8.4.2 Foreign Direct Investment (FDI)
8.4.3 Public-Private Partnerships (PPP)
8.4.4 Government Schemes
8.5 By Policy Support
8.5.1 Subsidies
8.5.2 Tax Exemptions
8.5.3 Renewable Energy Certificates (RECs)
8.5.4 Others
8.6 By Distribution Mode
8.6.1 Direct Sales
8.6.2 Distributors
8.6.3 Online Sales
8.6.4 Others
8.7 By Price Range
8.7.1 Budget
8.7.2 Mid-Range
8.7.3 Premium
8.7.4 Others
9. Qatar District Cooling Plant Construction Market Competitive Analysis
9.1 Market Share of Key Players(Micro, Small, Medium, Large Enterprises)
9.2 Cross Comparison of Key Players
9.2.1 Company Name
9.2.2 Group Size (Large, Medium, or Small as per industry convention)
9.2.3 Revenue Growth Rate
9.2.4 Market Penetration Rate
9.2.5 Customer Retention Rate
9.2.6 Operational Efficiency Ratio
9.2.7 Project Completion Rate
9.2.8 Pricing Strategy
9.2.9 Innovation Rate
9.2.10 Customer Satisfaction Score
9.3 SWOT Analysis of Top Players
9.4 Pricing Analysis(By Class and Payload)
9.5 Detailed Profile of Major Companies
9.5.1 Qatar Cool
9.5.2 Empower
9.5.3 Tabreed
9.5.4 Veolia
9.5.5 National Central Cooling Company
9.5.6 Qatari Diar
9.5.7 Al-Futtaim Engineering
9.5.8 Gulf District Cooling
9.5.9 Dalkia
9.5.10 Siemens
9.5.11 Engie
9.5.12 Abu Dhabi National Energy Company (TAQA)
9.5.13 Mott MacDonald
9.5.14 Kahramaa
9.5.15 Qatar University
10. Qatar District Cooling Plant Construction Market End-User Analysis
10.1 Procurement Behavior of Key Ministries
10.1.1 Ministry of Municipality and Environment
10.1.2 Ministry of Energy and Industry
10.1.3 Ministry of Transport and Communications
10.2 Corporate Spend on Infrastructure & Energy
10.2.1 Investment Trends in Infrastructure Projects
10.2.2 Energy Efficiency Budgets
10.2.3 Corporate Sustainability Initiatives
10.3 Pain Point Analysis by End-User Category
10.3.1 Cost Management Challenges
10.3.2 Reliability of Cooling Systems
10.3.3 Regulatory Compliance Issues
10.4 User Readiness for Adoption
10.4.1 Awareness of District Cooling Benefits
10.4.2 Financial Readiness for Investment
10.4.3 Technical Capability for Implementation
10.5 Post-Deployment ROI and Use Case Expansion
10.5.1 Measurement of Energy Savings
10.5.2 Expansion into New Developments
10.5.3 Long-term Maintenance Costs
11. Qatar District Cooling Plant Construction Market Future Size, 2025-2030
11.1 By Value
11.2 By Volume
11.3 By Average Selling Price
Go-To-Market Strategy Phase
1. Whitespace Analysis + Business Model Canvas
1.1 Market Gaps Identification
1.2 Business Model Development
1.3 Value Proposition Canvas
2. Marketing and Positioning Recommendations
2.1 Branding Strategies
2.2 Product USPs
3. Distribution Plan
3.1 Urban Retail Strategies
3.2 Rural NGO Tie-ups
4. Channel & Pricing Gaps
4.1 Underserved Routes
4.2 Pricing Bands Analysis
5. Unmet Demand & Latent Needs
5.1 Category Gaps
5.2 Consumer Segments
6. Customer Relationship
6.1 Loyalty Programs
6.2 After-sales Service
7. Value Proposition
7.1 Sustainability Initiatives
7.2 Integrated Supply Chains
8. Key Activities
8.1 Regulatory Compliance
8.2 Branding Efforts
8.3 Distribution Setup
9. Entry Strategy Evaluation
9.1 Domestic Market Entry Strategy
9.1.1 Product Mix Considerations
9.1.2 Pricing Band Strategy
9.1.3 Packaging Options
9.2 Export Entry Strategy
9.2.1 Target Countries
9.2.2 Compliance Roadmap
10. Entry Mode Assessment
10.1 Joint Ventures
10.2 Greenfield Investments
10.3 Mergers & Acquisitions
10.4 Distributor Model
11. Capital and Timeline Estimation
11.1 Capital Requirements
11.2 Timelines for Implementation
12. Control vs Risk Trade-Off
12.1 Ownership vs Partnerships
13. Profitability Outlook
13.1 Breakeven Analysis
13.2 Long-term Sustainability
14. Potential Partner List
14.1 Distributors
14.2 Joint Ventures
14.3 Acquisition Targets
15. Execution Roadmap
15.1 Phased Plan for Market Entry
15.1.1 Market Setup
15.1.2 Market Entry
15.1.3 Growth Acceleration
15.1.4 Scale & Stabilize
15.2 Key Activities and Milestones
15.2.1 Milestone Planning
15.2.2 Activity Tracking
Research Methodology
Phase 1: Approach1
Desk Research
- Analysis of government reports and publications on district cooling regulations and policies in Qatar
- Review of industry reports from energy and utilities associations focusing on district cooling technologies
- Examination of market trends and forecasts from academic journals and research papers related to sustainable energy solutions
Primary Research
- Interviews with project managers and engineers from leading construction firms involved in district cooling projects
- Surveys with facility managers and operators of existing district cooling plants in Qatar
- Focus group discussions with stakeholders from the real estate and urban development sectors
Validation & Triangulation
- Cross-validation of findings through comparison with international district cooling case studies
- Triangulation of data from government sources, industry reports, and expert interviews
- Sanity checks conducted through expert panel reviews comprising industry veterans and academic professionals
Phase 2: Market Size Estimation1
Top-down Assessment
- Estimation of market size based on national energy consumption statistics and district cooling adoption rates
- Segmentation of the market by end-user categories such as residential, commercial, and industrial sectors
- Incorporation of projected growth rates influenced by urbanization and climate change initiatives
Bottom-up Modeling
- Collection of data on installed capacity and operational efficiency from existing district cooling plants
- Cost analysis based on construction expenses, operational costs, and maintenance requirements
- Volume and pricing analysis to determine revenue potential for new district cooling projects
Forecasting & Scenario Analysis
- Development of forecasting models using historical data and projected growth in urban developments
- Scenario analysis based on varying levels of government support and investment in sustainable infrastructure
- Creation of baseline, optimistic, and pessimistic forecasts through 2030, considering economic and environmental factors
Phase 3: CATI Sample Composition1
| Scope Item/Segment | Sample Size | Target Respondent Profiles |
|---|---|---|
| Residential District Cooling Projects | 100 | Property Developers, Facility Managers |
| Commercial District Cooling Systems | 80 | Building Owners, Operations Managers |
| Industrial Cooling Solutions | 60 | Plant Managers, Energy Efficiency Consultants |
| Government Policy Impact | 50 | Regulatory Officials, Urban Planners |
| Technological Innovations in Cooling | 70 | R&D Managers, Technology Providers |
Frequently Asked Questions
What is the current value of the Qatar District Cooling Plant Construction Market?
The Qatar District Cooling Plant Construction Market is valued at approximately USD 1.5 billion, driven by the increasing demand for energy-efficient cooling solutions and significant infrastructure investments in urban areas.
What are the main drivers of growth in the Qatar District Cooling Market?
Which cities are the key players in the Qatar District Cooling Market?
What regulations has the Qatari government implemented regarding district cooling systems?
Other Regional/Country Reports
Indonesia District Cooling Plant Construction Market
Malaysia District Cooling Plant Construction Market
KSA District Cooling Plant Construction Market
APAC District Cooling Plant Construction Market
SEA District Cooling Plant Construction Market
Vietnam District Cooling Plant Construction Market
Other Adjacent Reports
Mexico District Cooling Systems Market
Malaysia HVAC Systems Market
Kuwait Energy Efficient Building Market
Brazil Sustainable Construction Market
South Korea Urban Infrastructure Development Market
South Africa Renewable Energy Integration Market
Thailand Smart City Technologies Market
UAE Commercial Real Estate Development Market
Belgium Industrial Cooling Solutions Market
Singapore Green Building Materials Market
Why Buy From Us?

What makes us stand out is that our consultants follow Robust, Refine and Result (RRR) methodology. Robust for clear definitions, approaches and sanity checking, Refine for differentiating respondents' facts and opinions, and Result for presenting data with story.

We have set a benchmark in the industry by offering our clients with syndicated and customized market research reports featuring coverage of entire market as well as meticulous research and analyst insights.

While we don't replace traditional research, we flip the method upside down. Our dual approach of Top Bottom & Bottom Top ensures quality deliverable by not just verifying company fundamentals but also looking at the sector and macroeconomic factors.

With one step in the future, our research team constantly tries to show you the bigger picture. We help with some of the tough questions you may encounter along the way: How is the industry positioned? Best marketing channel? KPI's of competitors? By aligning every element, we help maximize success.

Our report gives you instant access to the answers and sources that other companies might choose to hide. We elaborate each steps of research methodology we have used and showcase you the sample size to earn your trust.

If you need any support, we are here! We pride ourselves on universe strength, data quality, and quick, friendly, and professional service.