About the Report
Base Year 2025Vietnam Wealth Management Market Overview
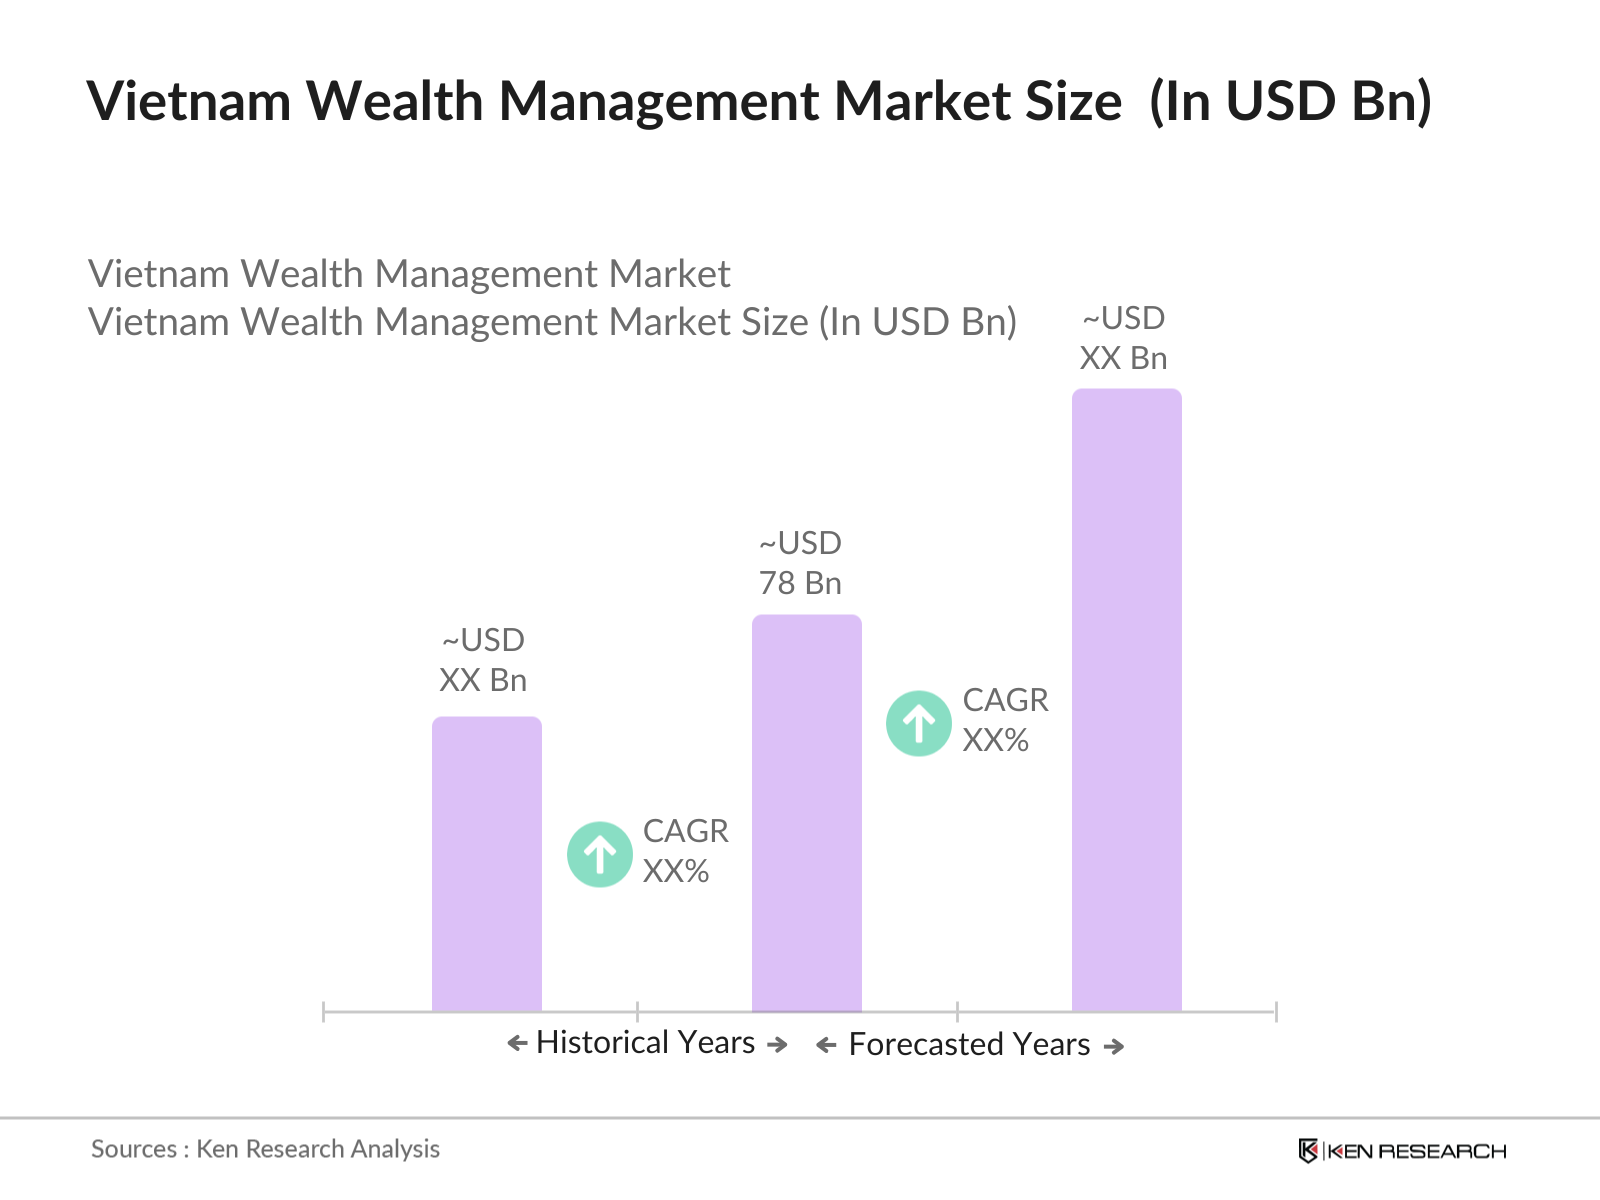
- The Vietnam Wealth Management Market is valued at approximately USD 78 billion, based on a five-year historical analysis and anchored to professionally managed assets. Licensed fund management companies oversee approximately VND 742 trillion, including more than VND 650 trillion in entrusted portfolios and nearly VND 92 trillion in investment-fund NAV. Expansion is supported by rising household wealth, greater securities participation and gradual migration from deposits and self-directed investing toward professionally managed portfolios.
- Ho Chi Minh City and Hanoi dominate the market because they concentrate private banks, securities companies, fund managers, entrepreneurs and high-income professionals. Vietnam has more than 9.25 million domestic securities trading accounts and approximately 19,400 millionaires, creating a broad pipeline for advisory and portfolio-management services. Ho Chi Minh City benefits from its corporate and entrepreneurial base, while Hanoi combines affluent households, financial institutions, government-linked enterprises and investment-management headquarters.
- Circular No. 99/2020/TT-BTC, issued by Vietnam’s Ministry of Finance in 2020, provides the operating framework for securities investment fund management companies. The regulation governs organizational requirements, portfolio management, internal controls, asset management activities and professional responsibilities. Together with the Securities Law and Circular No. 98/2020/TT-BTC governing investment funds, it establishes the regulatory foundation for licensed wealth and asset-management providers serving individual and institutional investors.
Vietnam Wealth Management Market Segmentation
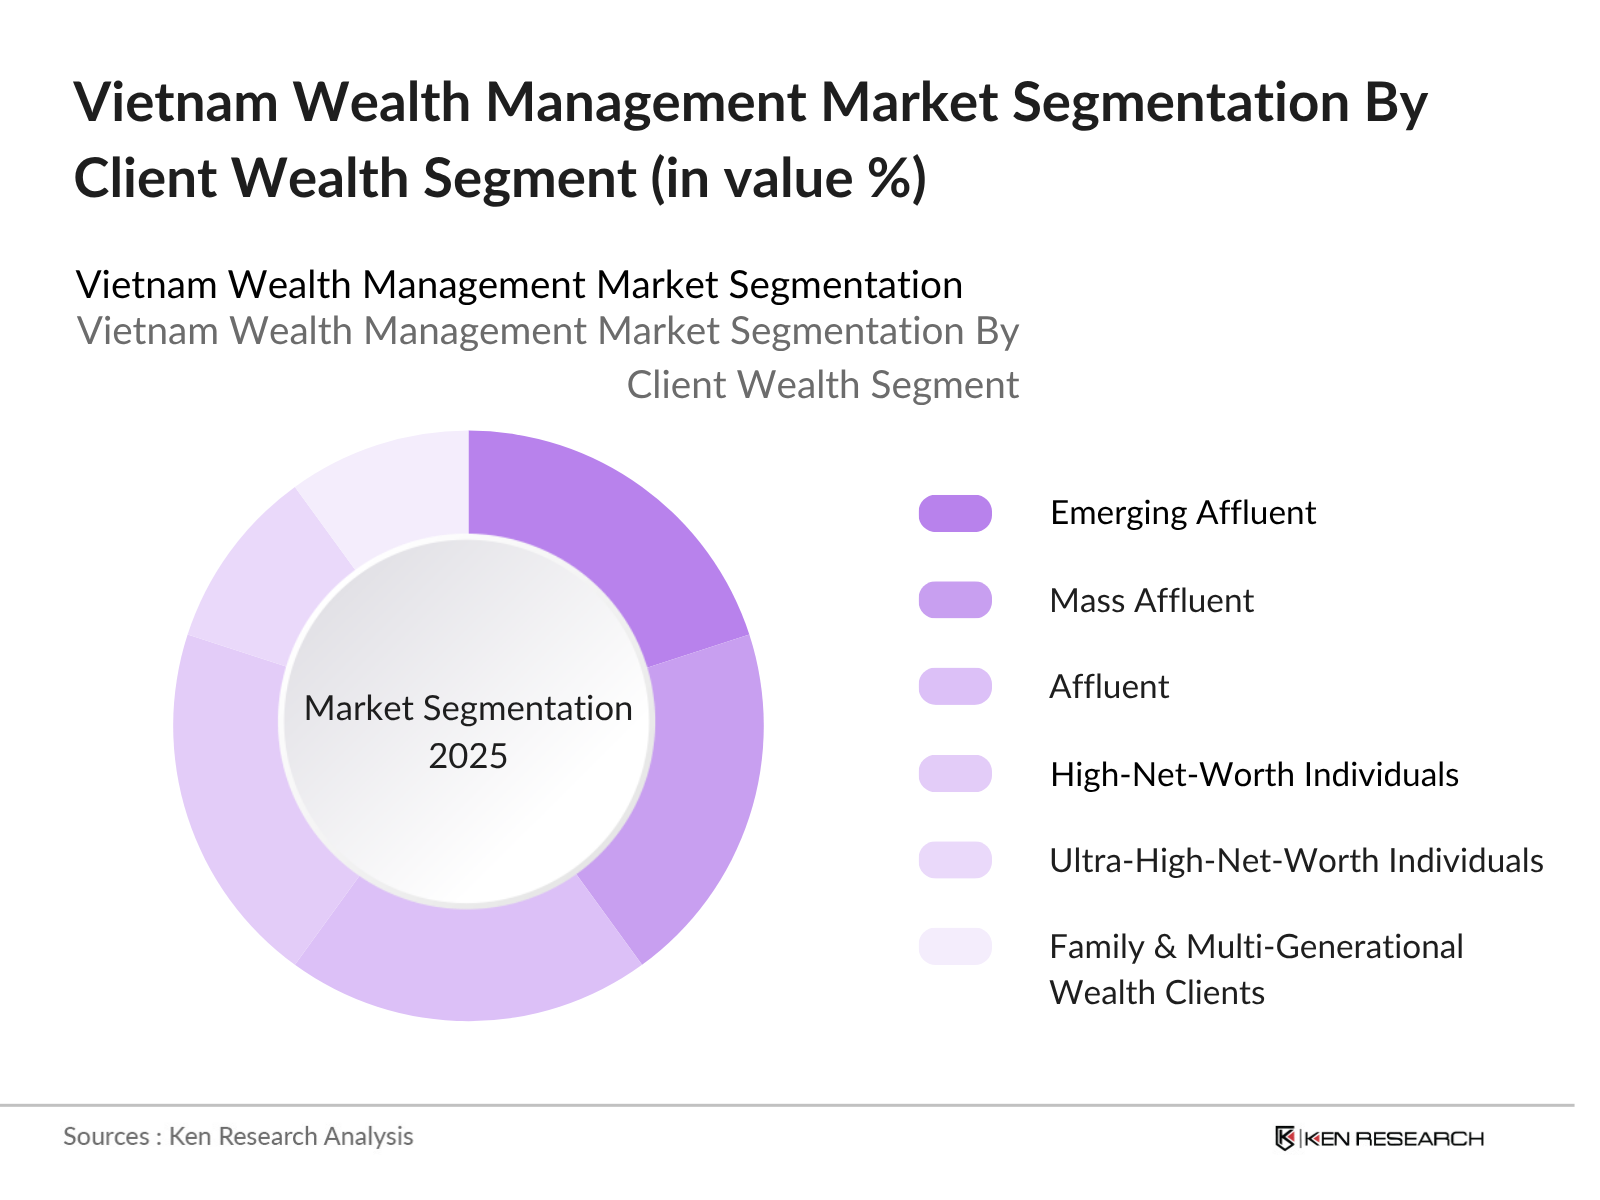
By Client Wealth Segment:High-Net-Worth Individuals represent the leading segment by managed asset value because concentrated business ownership, property wealth and investment portfolios create greater demand for professional diversification and relationship-led advice. Affluent and mass-affluent clients form a much larger pool by customer count and increasingly use funds, bonds, equities and digital investment products as alternatives to deposits. Ultra-High-Net-Worth Individuals represent fewer clients but require more complex portfolio construction, succession and offshore diversification support. Emerging-affluent consumers are becoming strategically important because mobile securities platforms and low-ticket investment products lower entry barriers. Family and multi-generational wealth clients remain a small but high-value segment requiring governance, inheritance planning and consolidated asset reporting. The indicative distribution below represents managed wealth rather than the number of individual clients.
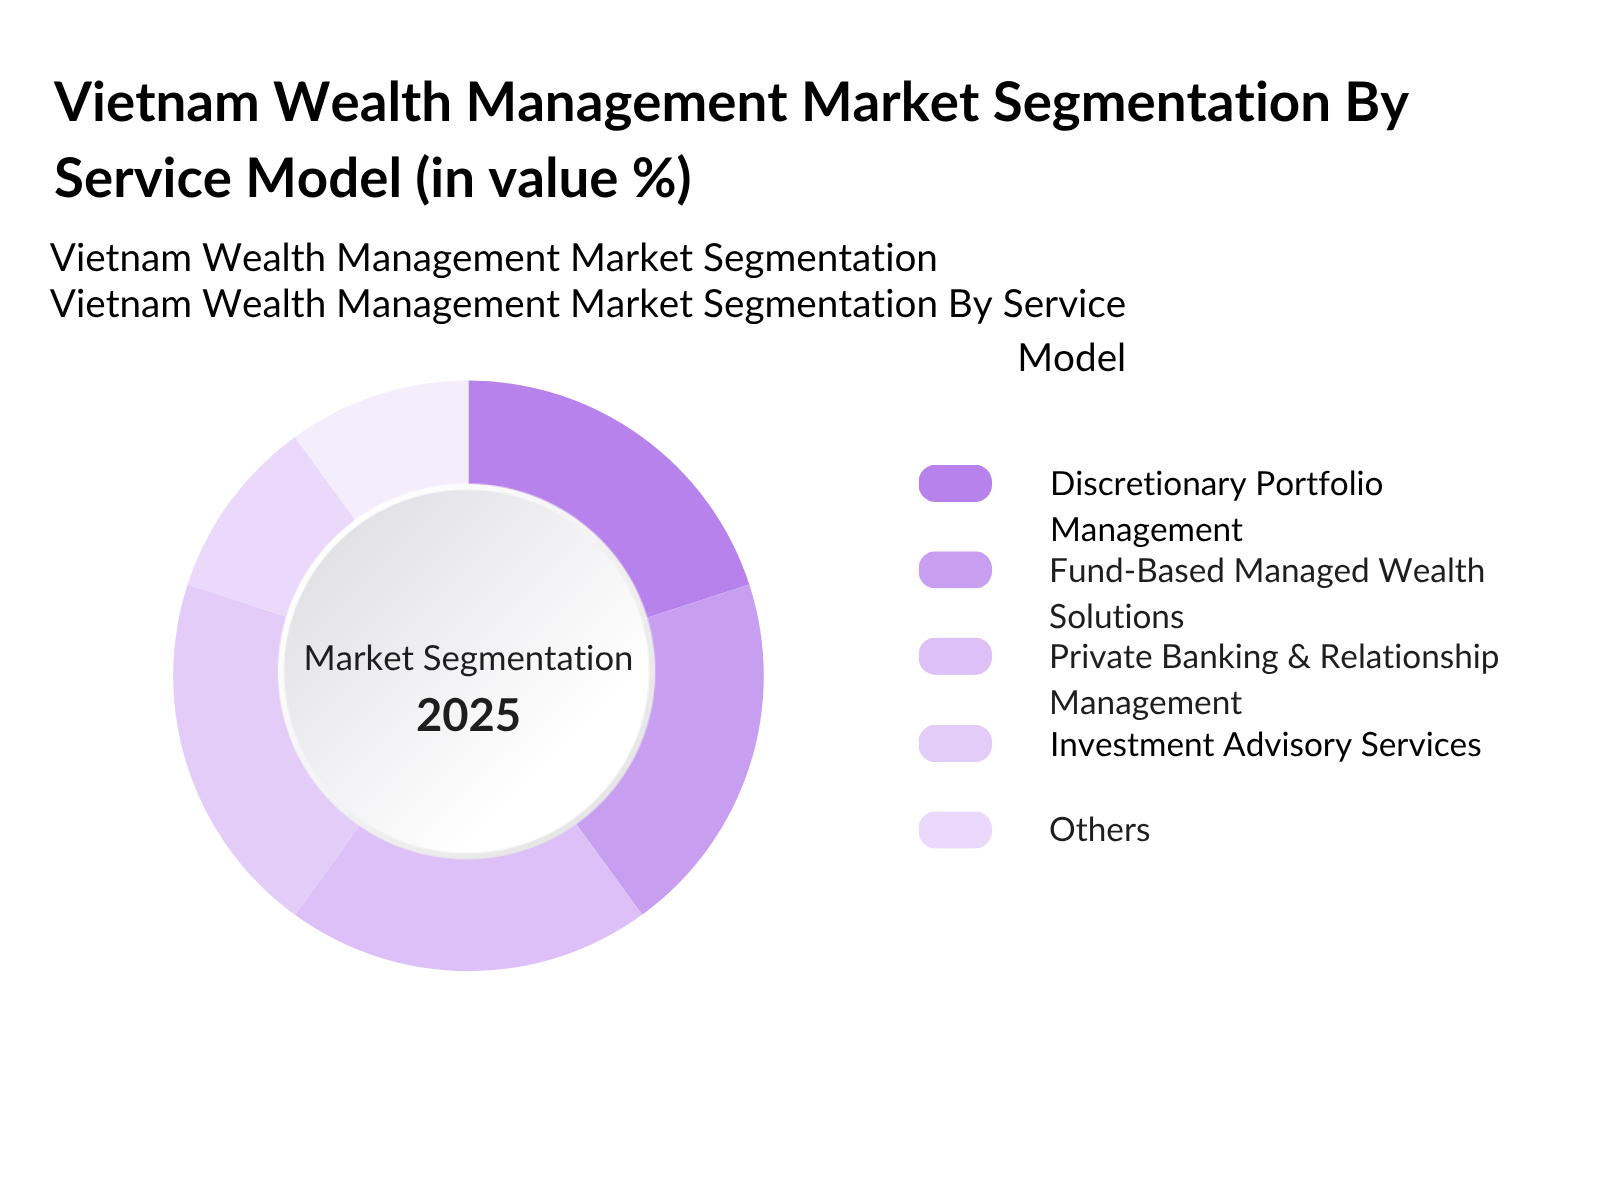
By Service Model:Discretionary portfolio management represents the largest service segment because Vietnam’s fund management industry already manages substantial entrusted portfolios for institutional and wealthy clients. Fund-based wealth solutions form another important category as open-ended funds, ETFs and diversified investment products gain acceptance among affluent retail investors. Private banking and relationship management serve clients requiring personalized advice, while investment advisory models support investors who retain final portfolio decisions. Digital and hybrid wealth services are expanding rapidly because mobile onboarding, securities platforms and automated portfolio tools reduce distribution costs. Execution-assisted services remain relevant for self-directed clients seeking access, research or transaction support without full portfolio delegation. Other services include specialized family wealth, succession, retirement and cross-border advisory solutions.
Vietnam Wealth Management Market Competitive Landscape
The Vietnam Wealth Management Market includes domestic and international fund managers, private-banking platforms, securities companies and digital investment providers. Leading participants such as Dragon Capital, VinaCapital, SSI Asset Management, Techcom Capital and Vietcombank Fund Management compete through Assets Under Management, product breadth, investment performance, affluent-client access, bank and securities distribution partnerships, relationship-manager capabilities and increasingly sophisticated digital wealth platforms.
Vietnam Wealth Management Market Industry Analysis
Growth Drivers
- Expansion of Professionally Managed Assets:Vietnam’s professional wealth-management ecosystem is expanding alongside the formal fund industry. Fund management companies oversaw approximately VND 742 trillion in assets, including more than VND 650 trillion in entrusted portfolios and nearly VND 92 trillion in fund NAV. The market also supported 43 licensed fund management companies. This growing institutional base gives affluent and high-net-worth clients more access to discretionary mandates, open-ended funds, ETFs, fixed-income products and professionally constructed portfolios beyond traditional bank deposits at scale.
- Rapid Expansion of Investor Participation:Investor participation is broadening rapidly as securities access becomes mainstream. Vietnam recorded 9,250,208 domestic securities trading accounts, including 9,232,471 individual accounts, alongside 47,780 foreign accounts. Open-ended fund trading accounts reached about 1.62 million through the depository system. A larger self-directed investor pool creates a natural conversion funnel for advisory, portfolio-management and private-banking services, especially as households seek asset allocation, risk management and long-term investment solutions across equities, bonds, funds and insurance-linked products across multiple financial goals.
- Growing Affluent and High-Net-Worth Population:The addressable affluent segment is becoming more relevant for premium financial services. Vietnam was home to about 19,400 millionaires, while another wealth-sizing methodology identified 5,459 individuals with liquid assets above USD 1 million. Ho Chi Minh City and Hanoi concentrate corporate ownership, entrepreneurship, high-income professionals and financial institutions. This wealth concentration supports demand for relationship managers, succession planning, portfolio diversification, offshore access, retirement solutions and tax-aware investment structures offered through banks, securities firms and asset managers.
Market Challenges
- Preference for Traditional and Self-Directed Assets:Managed wealth remains small relative to the country’s broader pool of personal financial assets because many households continue to favor cash, bank deposits, property and direct securities ownership. Even with VND 742 trillion managed by licensed fund managers, total fund NAV was only about VND 92 trillion. Wealth managers therefore face a client-conversion challenge: demonstrating professional portfolio value, transparent fees, liquidity and risk controls strongly enough to shift affluent investors from familiar self-directed assets toward discretionary and advisory products.
- Fragmented Provider and Regulatory Structure:Vietnam’s wealth-management ecosystem is fragmented across 43 fund management companies, securities firms, commercial banks, insurers and digital investment platforms, while regulation differs by product and institution. The market contained 120 securities investment funds, including 65 open-ended funds and 16 ETFs. Providers must manage suitability, disclosure, custody, distribution and portfolio-governance requirements across multiple product types. This increases compliance cost and makes integrated wealth propositions harder to deliver without strong technology, licensed advisers and coordinated product architecture.
Vietnam Wealth Management Market Future Outlook
Vietnam’s wealth-management sector is likely to deepen as more household savings move from deposits and direct trading toward diversified managed portfolios. The next phase will favor providers that combine private banking, securities access, open-ended funds, bonds, insurance and digital investment tools within a unified client experience. Ho Chi Minh City and Hanoi should remain the primary wealth hubs, while digital channels broaden reach into emerging affluent customers nationwide. Competition will increasingly depend on advisory quality, portfolio transparency, investment performance, open architecture, relationship-manager capability and seamless onboarding rather than product distribution alone, with regulatory discipline remaining central to trust.
Market Opportunities
- Conversion of Self-Directed Investors:The clearest opportunity is converting the country’s 9.25 million domestic securities accounts into higher-value advisory relationships. Providers can segment self-directed investors by portfolio size, activity and risk profile, then introduce goal-based portfolios, managed accounts and fund solutions. Digital onboarding combined with human advice can lower acquisition costs while creating a scalable path from mass affluent clients toward premium wealth tiers.
- Expansion of Managed Fund and Mandate Solutions:A second opportunity lies in professionally managed fund and mandate products. Fund managers already oversee roughly VND 742 trillion, while open-ended fund accounts reached about 1.62 million. Broader use of bond funds, balanced funds, ETFs, retirement solutions and discretionary portfolios can increase recurring fee income, particularly when banks and securities firms integrate these products into private-banking and affluent-client ecosystems.
Scope of the Report
| Segment | Sub-Segments |
|---|---|
| By Client Wealth Segment | Emerging Affluent Mass Affluent Affluent High-Net-Worth Individuals Ultra-High-Net-Worth Individuals Family & Multi-Generational Wealth Clients |
| By Service Model | Discretionary Portfolio Management Fund-Based Managed Wealth Solutions Private Banking & Relationship Management Investment Advisory Services Digital & Hybrid Wealth Management Execution-Assisted Investment Services Others |
| By Investment Product | Equity Funds & Listed Equities Bond Funds & Fixed-Income Securities Balanced & Multi-Asset Funds Exchange-Traded Funds Bank Deposits & Cash Management Products Insurance-Linked Investment Products Private Equity & Alternative Investments Retirement & Long-Term Savings Products Others |
| By Provider Type | Fund Management Companies Commercial Banks & Private Banks Securities Companies Insurance-Linked Wealth Providers Independent Investment Advisers Fintech & Digital Investment Platforms Others |
| By Investment Risk Profile | Capital Preservation Conservative Income Balanced Growth Aggressive Growth |
| By Distribution Channel | Relationship Manager & Private Banking Channel Bank Branch Distribution Securities Brokerage Platforms Fund Management Direct Distribution Mobile Apps & Digital Platforms Corporate & Institutional Partnerships Others |
| By Investment Objective | Capital Growth Regular Income Wealth Preservation Retirement Planning Education & Goal-Based Savings Succession & Intergenerational Wealth Transfer Others |
| By Geography | Ho Chi Minh City Hanoi Southeast Vietnam Central Vietnam Mekong Delta Northern Provinces excluding Hanoi |
Key Target Audience
Fund Management and Asset Management Companies
Commercial Banks and Private Banking Divisions
Securities Companies and Investment Platforms
Insurance Companies and Retirement-Solution Providers
High-Net-Worth and Family Wealth Service Providers
Investors and Venture Capitalist Firms
Government and Regulatory Bodies including State Securities Commission and Ministry of Finance
Fintech and Digital Wealth Management Platforms
Major Players Mentioned
Dragon Capital Vietfund Management
VinaCapital Fund Management JSC
SSI Asset Management Company Limited
Techcom Capital Joint Stock Company
Vietcombank Fund Management Company Limited
MB Capital Management Joint Stock Company
Eastspring Investments Fund Management Company
Manulife Investment Fund Management Vietnam
UOB Asset Management Vietnam
Viet Capital Asset Management Joint Stock Company
Table of Contents
Market Assessment Phase
1. Executive Summary and Approach
2. Vietnam Wealth Management Market Overview
2.1 Key Insights and Strategic Recommendations
2.2 Vietnam Wealth Management Market Overview
2.3 Definition and Scope
2.4 Evolution of Market Ecosystem
2.5 Timeline of Key Regulatory Milestones
2.6 Value Chain & Stakeholder Mapping
2.7 Business Cycle Analysis
2.8 Policy & Incentive Landscape
3. Vietnam Wealth Management Market Analysis
3.1 Growth Drivers
3.1.1 Expansion of Affluent and High-Net-Worth Client Base
3.1.2 Rising Securities and Investment Fund Participation
3.1.3 Shift from Deposits toward Professionally Managed Investments
3.1.4 Expansion of Digital Wealth and Hybrid Advisory Platforms
3.2 Market Challenges
3.2.1 Strong Household Preference for Deposits, Property and Direct Investing
3.2.2 Fragmented Wealth Management Regulatory and Distribution Structure
3.2.3 Shortage of Experienced Relationship Managers and Investment Advisers
3.2.4 Investor Trust, Product Transparency and Financial-Literacy Constraints
3.3 Market Opportunities
3.3.1 Conversion of Self-Directed Investors into Advisory Clients
3.3.2 Mass-Affluent Digital Wealth Management
3.3.3 Retirement, Goal-Based and Long-Term Investment Products
3.3.4 Family Wealth, Succession and Multi-Generational Advisory Services
3.4 Market Trends
3.4.1 Increasing Adoption of Open-Ended Funds and ETFs
3.4.2 Growth of Fee-Based and Goal-Based Advisory Models
3.4.3 Integration of Private Banking, Securities and Fund Platforms
3.4.4 Expansion of Mobile-First Wealth Management and Digital Onboarding
3.5 Government Regulation
3.5.1 Securities Law No. 54/2019/QH14
3.5.2 Decree No. 155/2020/ND-CP on Implementation of Securities Law
3.5.3 Circular No. 98/2020/TT-BTC on Securities Investment Funds
3.5.4 Circular No. 99/2020/TT-BTC on Fund Management Companies
4. SWOT Analysis
5. Stakeholder Analysis
6. Porter's Five Forces Analysis
7. Vietnam Wealth Management Market Size, 2019-2024
7.1 By Assets Under Management
7.2 By Number of Managed Investment Accounts
7.3 By Average Assets per Client
8. Vietnam Wealth Management Market Segmentation
8.1 By Client Wealth Segment
8.1.1 Emerging Affluent
8.1.2 Mass Affluent
8.1.3 Affluent
8.1.4 High-Net-Worth Individuals
8.1.5 Ultra-High-Net-Worth Individuals
8.1.6 Family & Multi-Generational Wealth Clients
8.2 By Service Model
8.2.1 Discretionary Portfolio Management
8.2.2 Fund-Based Managed Wealth Solutions
8.2.3 Private Banking & Relationship Management
8.2.4 Investment Advisory Services
8.2.5 Digital & Hybrid Wealth Management
8.2.6 Execution-Assisted Investment Services
8.2.7 Others
8.3 By Investment Product
8.3.1 Equity Funds & Listed Equities
8.3.2 Bond Funds & Fixed-Income Securities
8.3.3 Balanced & Multi-Asset Funds
8.3.4 Exchange-Traded Funds
8.3.5 Bank Deposits & Cash Management Products
8.3.6 Insurance-Linked Investment Products
8.3.7 Private Equity & Alternative Investments
8.3.8 Retirement & Long-Term Savings Products
8.3.9 Others
8.4 By Provider Type
8.4.1 Fund Management Companies
8.4.2 Commercial Banks & Private Banks
8.4.3 Securities Companies
8.4.4 Insurance-Linked Wealth Providers
8.4.5 Independent Investment Advisers
8.4.6 Fintech & Digital Investment Platforms
8.4.7 Others
8.5 By Investment Risk Profile
8.5.1 Capital Preservation
8.5.2 Conservative Income
8.5.3 Balanced
8.5.4 Growth
8.5.5 Aggressive Growth
8.6 By Distribution Channel
8.6.1 Relationship Manager & Private Banking Channel
8.6.2 Bank Branch Distribution
8.6.3 Securities Brokerage Platforms
8.6.4 Fund Management Direct Distribution
8.6.5 Mobile Apps & Digital Platforms
8.6.6 Corporate & Institutional Partnerships
8.6.7 Others
8.7 By Investment Objective
8.7.1 Capital Growth
8.7.2 Regular Income
8.7.3 Wealth Preservation
8.7.4 Retirement Planning
8.7.5 Education & Goal-Based Savings
8.7.6 Succession & Intergenerational Wealth Transfer
8.7.7 Others
8.8 By Geography
8.8.1 Ho Chi Minh City
8.8.2 Hanoi
8.8.3 Southeast Vietnam
8.8.4 Central Vietnam
8.8.5 Mekong Delta
8.8.6 Northern Provinces excluding Hanoi
9. Vietnam Wealth Management Market Competitive Analysis
9.1 Market Share of Key Players (Micro, Small, Medium, Large Enterprises)
9.2 Cross Comparison of Key Players
9.2.1 Company Name
9.2.2 Group Size (Large, Medium, or Small as per industry convention)
9.2.3 Assets Under Management
9.2.4 Affluent & HNWI Client Base
9.2.5 Wealth Product Portfolio Breadth
9.2.6 Discretionary & Advisory Mandate Capability
9.2.7 Distribution & Relationship Manager Coverage
9.2.8 Digital Wealth Platform Capability
9.2.9 Investment Performance & Client Retention
9.2.10 Pricing Strategy
9.3 SWOT Analysis of Top Players
9.4 Pricing Analysis by Client Tier and Advisory Model
9.5 Detailed Profile of Major Companies
9.5.1 Dragon Capital Vietfund Management
9.5.2 VinaCapital Fund Management JSC
9.5.3 SSI Asset Management Company Limited
9.5.4 Techcom Capital Joint Stock Company
9.5.5 Vietcombank Fund Management Company Limited
9.5.6 MB Capital Management Joint Stock Company
9.5.7 Eastspring Investments Fund Management Company
9.5.8 Manulife Investment Fund Management Vietnam
9.5.9 UOB Asset Management Vietnam
9.5.10 Viet Capital Asset Management Joint Stock Company
9.5.11 Bao Viet Fund Management Company Limited
9.5.12 VNDIRECT Securities Corporation
9.5.13 Techcom Securities Joint Stock Company
9.5.14 VPBank Securities Joint Stock Company
9.5.15 Mirae Asset Securities Vietnam
10. Vietnam Wealth Management Market End-User Analysis
10.1 Investment Behavior of Institutional Asset Owners
10.1.1 Insurance Company Investment Mandates
10.1.2 Corporate Treasury Portfolio Management
10.1.3 Pension & Long-Term Savings Allocation
10.1.4 Outsourced Institutional Portfolio Management
10.2 Corporate Spend on Employee Wealth & Financial Benefits
10.2.1 Employee Retirement and Long-Term Savings Programs
10.2.2 Executive Financial Planning Benefits
10.2.3 Employee Investment Education Programs
10.2.4 Corporate Cash and Treasury Advisory
10.3 Pain Point Analysis by Client Category
10.3.1 Limited Portfolio Diversification
10.3.2 Product Complexity and Fee Transparency
10.3.3 Lack of Integrated Financial Planning
10.3.4 Relationship Manager Quality and Continuity
10.3.5 Liquidity and Investment Performance Concerns
10.4 User Readiness for Adoption
10.4.1 Adoption of Open-Ended Funds
10.4.2 Adoption of Discretionary Portfolio Management
10.4.3 Adoption of Digital Wealth Platforms
10.4.4 Adoption of Retirement and Goal-Based Investing
10.5 Post-Adoption ROI and Use Case Expansion
10.5.1 Improved Portfolio Diversification
10.5.2 Consolidated Wealth Reporting
10.5.3 Expansion from Investment Products to Holistic Financial Planning
10.5.4 Multi-Generational Wealth and Succession Planning
11. Vietnam Wealth Management Market Future Size, 2025-2030
11.1 By Assets Under Management
11.2 By Managed Investment Accounts
11.3 By Average Assets per Client
Go-To-Market Strategy Phase
1. Whitespace Analysis + Business Model Canvas
1.1 Mass-Affluent Hybrid Advisory
1.2 Digital Goal-Based Investment Portfolios
1.3 Retirement and Long-Term Savings Solutions
1.4 Family-Office-Lite Services for Emerging HNWIs
2. Marketing and Positioning Recommendations (Branding Strategies, Product USPs)
2.1 Position Around Trust, Transparency and Fiduciary Discipline
2.2 Promote Goal-Based Asset Allocation as a Core USP
2.3 Build Investment Education and Thought Leadership
2.4 Differentiate Through Hybrid Human and Digital Advice
3. Distribution Plan (Private Banking, Securities and Digital Channels)
3.1 Ho Chi Minh City Private Wealth Hub
3.2 Hanoi Affluent and Institutional Wealth Hub
3.3 Bank and Securities Distribution Partnerships
3.4 Nationwide Mobile and Digital Wealth Distribution
4. Channel & Pricing Gaps (Underserved Segments, Pricing Bands)
4.1 Sub-HNWI Advisory Gap
4.2 Transparent Fee-Based Advisory Gap
4.3 Independent Open-Architecture Product Gap
4.4 Secondary-City Relationship Management Gap
5. Unmet Demand & Latent Needs (Category Gaps, Client Segments)
5.1 Integrated Financial Planning for Entrepreneurs
5.2 Multi-Asset Portfolios for Mass-Affluent Investors
5.3 Retirement and Education Goal Planning
5.4 Succession Planning and Family Wealth Governance
6. Customer Relationship (Loyalty Programs, Advisory Service)
7.1 Dedicated Relationship Manager Coverage
7.2 Quarterly Portfolio Review Programs
7.3 Tiered Wealth Membership Benefits
7.4 Investment Education and Client Engagement Events
7. Value Proposition (Transparency, Diversification, Integrated Advice)
8.1 Open-Architecture Investment Access
8.2 Personalized Risk-Based Portfolio Construction
8.3 Consolidated Wealth Reporting
8.4 Hybrid Digital and Human Advisory
8. Key Activities (Regulatory Compliance, Product Setup, Distribution)
9.1 Securities and Fund Management Regulatory Compliance
9.2 Investment Product Shelf Development
9.3 Relationship Manager Recruitment and Training
9.4 Digital KYC, Portfolio Reporting and Advisory Platform Setup
9. Entry Strategy Evaluation
9.1 Domestic Market Entry Strategy (Product Mix, Pricing Band, Client Tier)
10.1.1 Launch with Mass-Affluent and Affluent Client Segments
10.1.2 Offer Balanced, Fixed-Income and Equity Portfolio Solutions
10.1.3 Establish Transparent Advisory and Management Fee Tiers
10.1.4 Prioritize Ho Chi Minh City and Hanoi before National Expansion
9.2 International Entry Strategy (Cross-Border Expertise, Compliance Roadmap)
10.2.1 Partner with Licensed Vietnamese Financial Institutions
10.2.2 Localize Global Asset Allocation and Investment Products
10.2.3 Establish Regulatory and Data-Protection Compliance Framework
10.2.4 Develop Offshore Investment Expertise for Eligible Clients
10. Entry Mode Assessment (JV, Greenfield, M&A, Distribution Partnership)
11.1 Bank Distribution Partnership
11.2 Joint Venture with Licensed Fund Management Company
11.3 Acquisition of Local Wealth or Securities Platform
11.4 Greenfield Digital Wealth Platform with Licensed Partner
11. Capital and Timeline Estimation (Capital Requirements, Timelines)
12.1 Licensing and Regulatory Setup Requirements
12.2 Digital Platform and Cybersecurity Investment
12.3 Relationship Manager and Investment Team Cost
12.4 Marketing and Client Acquisition Investment
12. Control vs Risk Trade-Off (Ownership vs Partnerships)
13.1 Direct Product Control versus Bank Distribution Reach
13.2 Proprietary Products versus Open Architecture
13.3 Digital Scale versus Relationship Manager Intensity
13.4 Premium Advisory versus Mass-Affluent Accessibility
13. Profitability Outlook (Breakeven Analysis, Long-Term Sustainability)
14.1 Advisory and Management Fee Revenue
14.2 Assets Under Management Economics
14.3 Relationship Manager Productivity
14.4 Client Acquisition, Retention and Cross-Sell Economics
14. Potential Partner List (Distributors, JVs, Acquisition Targets)
15.1 Commercial Banks - Affluent Client Distribution Assessment
15.2 Securities Companies - Investment Platform Partnership Assessment
15.3 Fund Management Companies - Product Manufacturing Partnership Assessment
15.4 Insurance Companies - Long-Term Wealth Solution Partnership Assessment
15. Execution Roadmap
15.1 Phased Plan for Market Entry (Market Setup → Market Entry → Growth Acceleration → Scale & Stabilize)
16.1.1 Market Setup: Licensing, Product Architecture and Partner Selection
16.1.2 Market Entry: Ho Chi Minh City and Hanoi Client Acquisition
16.1.3 Growth Acceleration: Digital Wealth and Bank Distribution Expansion
16.1.4 Scale & Stabilize: Family Wealth, Retirement and Nationwide Coverage
15.2 Key Activities and Milestones
16.2.1 Complete Regulatory and Compliance Framework
16.2.2 Establish Core Investment and Advisory Team
16.2.3 Launch Initial Wealth Product Portfolio
16.2.4 Onboard Priority Affluent and HNWI Clients
16.2.5 Launch Digital Portfolio and Reporting Platform
16.2.6 Expand into Retirement and Family Wealth Services
Research Methodology
Phase 1: Approach1
Desk Research
- Analysis of fund management AUM, investment fund NAV, securities accounts, fund-account participation and wealth-industry indicators
- Review of State Securities Commission regulations, investment fund rules, fund management company requirements and securities-market policies
- Assessment of wealth-management products, private-banking offerings, securities platforms, fund portfolios and provider distribution models
Primary Research
- Interviews with fund managers, private bankers, wealth relationship managers and investment advisers
- Discussions with affluent investors, HNWIs, entrepreneurs and corporate treasury decision makers
- Interviews with securities-company product heads, bank wealth managers and digital investment platform executives
Validation & Triangulation
- Cross-validation of Assets Under Management using fund manager, regulatory and portfolio-level indicators
- Triangulation of client segmentation using relationship-manager interviews, product balances and investment behavior
- Sanity checks across fund NAV, entrusted portfolios, investment accounts and provider-level managed assets
Phase 2: Market Size Estimation1
Top-down Assessment
- Assessment of total professionally managed assets across licensed fund management companies
- Allocation of managed wealth across client segments, service models and investment products
- Adjustment for overlapping fund, private-banking and securities-platform distribution channels
Bottom-up Modeling
- Provider-level AUM and investment mandate benchmarks across leading asset managers
- Client-balance estimates across affluent, HNWI and institutional managed portfolios
- Aggregation of open-ended funds, ETFs, discretionary mandates and advisory-linked assets
Forecasting & Scenario Analysis
- Assessment of affluent population growth, securities participation and managed-investment adoption
- Scenarios based on deposit migration, fund penetration, digital wealth adoption and regulatory development
- Baseline, accelerated-managed-wealth and conservative-adoption scenarios through the outlook period
Phase 3: CATI Sample Composition1
| Scope Item/Segment | Sample Size | Target Respondent Profiles |
|---|---|---|
| Affluent & Mass-Affluent Wealth Clients | 130 | Affluent Investors, Professionals, Business Owners, Senior Executives |
| High-Net-Worth Clients | 70 | Entrepreneurs, Family Business Owners, HNWIs, Private-Banking Clients |
| Fund Management Companies | 60 | Portfolio Managers, Fund Managers, Product Heads, Investment Directors |
| Banks & Securities Wealth Platforms | 55 | Private Bankers, Relationship Managers, Wealth Product Heads, Brokerage Managers |
| Institutional Asset Owners | 45 | Chief Investment Officers, Treasury Heads, Insurance Investment Managers, Finance Directors |
Frequently Asked Questions
What is the size of the Vietnam Wealth Management Market?
The Vietnam Wealth Management Market is valued at approximately USD 29 billion based on professionally managed assets. Licensed fund management companies oversee about VND 742 trillion, including more than VND 650 trillion in entrusted portfolios and nearly VND 92 trillion in investment-fund NAV.
What is driving growth in the Vietnam Wealth Management Market?
How many fund management companies operate in Vietnam?
Why Buy From Us?

What makes us stand out is that our consultants follow Robust, Refine and Result (RRR) methodology. Robust for clear definitions, approaches and sanity checking, Refine for differentiating respondents' facts and opinions, and Result for presenting data with story.

We have set a benchmark in the industry by offering our clients with syndicated and customized market research reports featuring coverage of entire market as well as meticulous research and analyst insights.

While we don't replace traditional research, we flip the method upside down. Our dual approach of Top Bottom & Bottom Top ensures quality deliverable by not just verifying company fundamentals but also looking at the sector and macroeconomic factors.

With one step in the future, our research team constantly tries to show you the bigger picture. We help with some of the tough questions you may encounter along the way: How is the industry positioned? Best marketing channel? KPI's of competitors? By aligning every element, we help maximize success.

Our report gives you instant access to the answers and sources that other companies might choose to hide. We elaborate each steps of research methodology we have used and showcase you the sample size to earn your trust.

If you need any support, we are here! We pride ourselves on universe strength, data quality, and quick, friendly, and professional service.