About the Report
Base Year 2024Listen to the audio summary
Saudi Arabia Automotive Smart Glass OEM and Aftermarket Overview
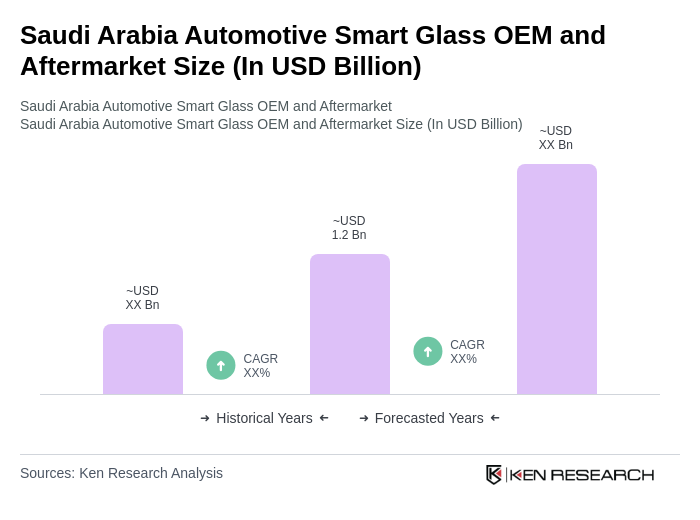
- The Saudi Arabia Automotive Smart Glass OEM and Aftermarket market is valued at USD 1.2 billion, based on a five-year historical analysis. This growth is primarily driven by increasing consumer demand for advanced automotive technologies, coupled with rising awareness of energy efficiency and sustainability. The integration of smart glass technologies in vehicles enhances comfort and safety, making it a preferred choice among manufacturers and consumers alike.
- Key cities such as Riyadh, Jeddah, and Dammam dominate the market due to their significant automotive manufacturing presence and high vehicle ownership rates. The concentration of automotive OEMs and aftermarket service providers in these urban centers facilitates innovation and distribution, further driving market growth. Additionally, the affluent consumer base in these cities is more inclined to invest in advanced automotive technologies.
- In 2023, the Saudi government implemented regulations mandating the use of energy-efficient materials in automotive manufacturing. This regulation aims to promote sustainability and reduce carbon emissions in the automotive sector, thereby encouraging the adoption of smart glass technologies. Compliance with these regulations is expected to drive innovation and investment in the automotive smart glass market.
Saudi Arabia Automotive Smart Glass OEM and Aftermarket Segmentation
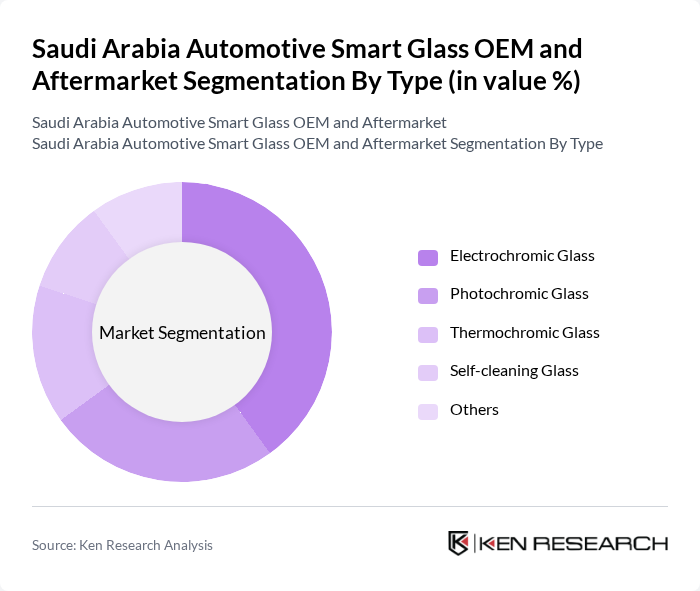
By Type:The market is segmented into various types of smart glass technologies, including Electrochromic Glass, Photochromic Glass, Thermochromic Glass, Self-cleaning Glass, and Others. Among these, Electrochromic Glass is gaining significant traction due to its ability to adjust transparency based on light exposure, enhancing passenger comfort and energy efficiency. The growing trend towards customization and luxury in vehicles is also propelling the demand for this type of smart glass.
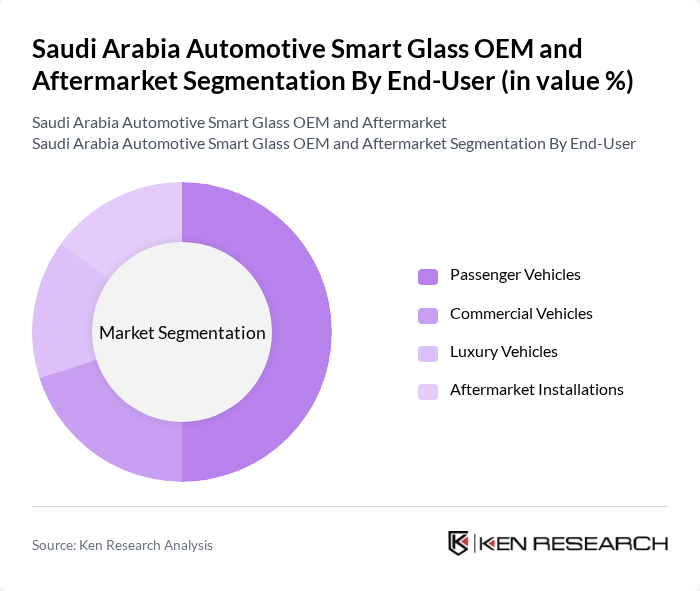
By End-User:The end-user segmentation includes Passenger Vehicles, Commercial Vehicles, Luxury Vehicles, and Aftermarket Installations. The Passenger Vehicles segment is the largest, driven by the increasing adoption of smart glass technologies in personal vehicles. Consumers are increasingly seeking enhanced comfort, safety, and aesthetic appeal, which smart glass technologies provide, leading to a surge in demand in this segment.
Saudi Arabia Automotive Smart Glass OEM and Aftermarket Competitive Landscape
The Saudi Arabia Automotive Smart Glass OEM and Aftermarket market is characterized by a dynamic mix of regional and international players. Leading participants such as Saint-Gobain, AGC Inc., NSG Group, Guardian Glass, Xinyi Glass Holdings, Fuyao Glass Industry Group, PPG Industries, Corning Incorporated, Asahi Glass Co., Ltd., Solutia Inc., Sika AG, 3M Company, Eastman Chemical Company, Nippon Sheet Glass Co., Ltd., Schott AG contribute to innovation, geographic expansion, and service delivery in this space.
Saudi Arabia Automotive Smart Glass OEM and Aftermarket Industry Analysis
Growth Drivers
- Increasing Demand for Energy-Efficient Vehicles:The Saudi automotive market is witnessing a significant shift towards energy-efficient vehicles, with a projected increase in electric vehicle (EV) sales from 5,000 units to 15,000 units. This surge is driven by rising fuel prices and government incentives, such as the Saudi Green Initiative, which aims to reduce carbon emissions by 60% in future. Consequently, the demand for smart glass technology, which enhances energy efficiency, is expected to rise substantially.
- Technological Advancements in Smart Glass:The automotive smart glass sector is experiencing rapid technological advancements, with innovations such as electrochromic and photochromic glass gaining traction. In future, the market for smart glass technology in vehicles is anticipated to reach approximately SAR 1.2 billion, driven by improved functionalities like self-tinting and enhanced UV protection. These advancements not only improve vehicle aesthetics but also contribute to energy savings, making them increasingly attractive to manufacturers and consumers alike.
- Government Initiatives Promoting Automotive Innovation:The Saudi government is actively promoting automotive innovation through various initiatives, including the National Industrial Development and Logistics Program, which allocates SAR 1.5 billion for automotive technology development. This funding is expected to foster research and development in smart glass technologies, encouraging local manufacturers to adopt these innovations. As a result, the automotive smart glass market is likely to benefit from increased investment and support, enhancing its growth prospects in the region.
Market Challenges
- High Initial Costs of Smart Glass Technology:One of the primary challenges facing the adoption of smart glass in the automotive sector is the high initial cost associated with the technology. The average cost of smart glass installation in vehicles can range from SAR 5,000 to SAR 10,000, which may deter consumers, especially in a market where price sensitivity is prevalent. This financial barrier can limit the widespread adoption of smart glass solutions, hindering market growth.
- Limited Awareness Among Consumers:Despite the benefits of smart glass technology, consumer awareness remains limited in Saudi Arabia. A recent survey indicated that only 30% of consumers are familiar with smart glass features and their advantages. This lack of awareness can impede market penetration, as consumers may not prioritize smart glass when purchasing vehicles. Effective marketing strategies and educational campaigns are essential to bridge this knowledge gap and stimulate demand.
Saudi Arabia Automotive Smart Glass OEM and Aftermarket Future Outlook
The future of the automotive smart glass market in Saudi Arabia appears promising, driven by increasing consumer demand for energy-efficient and technologically advanced vehicles. As the government continues to support innovation and sustainability initiatives, the market is expected to witness significant growth. Additionally, the expansion of the electric vehicle segment will further enhance the adoption of smart glass technologies, creating a favorable environment for manufacturers and aftermarket suppliers to thrive in the coming years.
Market Opportunities
- Expansion of Electric Vehicle Market:The rapid growth of the electric vehicle market presents a significant opportunity for smart glass manufacturers. With the Saudi government targeting 30% of all vehicles to be electric in future, the demand for energy-efficient smart glass solutions is expected to rise, providing a lucrative avenue for innovation and investment in this sector.
- Collaborations with Automotive Manufacturers:Strategic partnerships between smart glass technology providers and automotive manufacturers can lead to enhanced product offerings. Collaborations can facilitate the integration of smart glass into new vehicle models, allowing manufacturers to differentiate their products in a competitive market. This synergy is likely to drive innovation and expand market reach for both parties involved.
Scope of the Report
| Segment | Sub-Segments |
|---|---|
| By Type | Electrochromic Glass Photochromic Glass Thermochromic Glass Self-cleaning Glass Others |
| By End-User | Passenger Vehicles Commercial Vehicles Luxury Vehicles Aftermarket Installations |
| By Application | Windshields Side Windows Sunroofs Rear Windows |
| By Sales Channel | OEM Sales Aftermarket Sales Online Retail Physical Retail |
| By Distribution Mode | Direct Distribution Indirect Distribution E-commerce Platforms |
| By Price Range | Budget Mid-range Premium |
| By Policy Support | Government Subsidies Tax Incentives Regulatory Support Others |
Key Target Audience
Investors and Venture Capitalist Firms
Government and Regulatory Bodies (e.g., Saudi Standards, Metrology and Quality Organization)
Automotive Manufacturers and Producers
Automotive Component Distributors and Retailers
Smart Glass Technology Providers
Automotive Industry Associations
Financial Institutions and Banks
Automotive Aftermarket Service Providers
Players Mentioned in the Report:
Saint-Gobain
AGC Inc.
NSG Group
Guardian Glass
Xinyi Glass Holdings
Fuyao Glass Industry Group
PPG Industries
Corning Incorporated
Asahi Glass Co., Ltd.
Solutia Inc.
Sika AG
3M Company
Eastman Chemical Company
Nippon Sheet Glass Co., Ltd.
Schott AG
Table of Contents
Market Assessment Phase
1. Executive Summary and Approach
2. Saudi Arabia Automotive Smart Glass OEM and Aftermarket Overview
2.1 Key Insights and Strategic Recommendations
2.2 Saudi Arabia Automotive Smart Glass OEM and Aftermarket Overview
2.3 Definition and Scope
2.4 Evolution of Market Ecosystem
2.5 Timeline of Key Regulatory Milestones
2.6 Value Chain & Stakeholder Mapping
2.7 Business Cycle Analysis
2.8 Policy & Incentive Landscape
3. Saudi Arabia Automotive Smart Glass OEM and Aftermarket Analysis
3.1 Growth Drivers
3.1.1 Increasing demand for energy-efficient vehicles
3.1.2 Technological advancements in smart glass
3.1.3 Government initiatives promoting automotive innovation
3.1.4 Rising consumer awareness about vehicle safety
3.2 Market Challenges
3.2.1 High initial costs of smart glass technology
3.2.2 Limited awareness among consumers
3.2.3 Regulatory hurdles in product certification
3.2.4 Competition from traditional glass manufacturers
3.3 Market Opportunities
3.3.1 Expansion of electric vehicle market
3.3.2 Collaborations with automotive manufacturers
3.3.3 Development of aftermarket solutions
3.3.4 Growing interest in luxury vehicles
3.4 Market Trends
3.4.1 Increasing integration of smart technologies in vehicles
3.4.2 Shift towards sustainable materials
3.4.3 Rise in demand for customization options
3.4.4 Adoption of smart glass in commercial vehicles
3.5 Government Regulation
3.5.1 Standards for automotive safety and performance
3.5.2 Incentives for green technology adoption
3.5.3 Regulations on vehicle emissions
3.5.4 Compliance requirements for aftermarket products
4. SWOT Analysis
5. Stakeholder Analysis
6. Porter's Five Forces Analysis
7. Saudi Arabia Automotive Smart Glass OEM and Aftermarket Market Size, 2019-2024
7.1 By Value
7.2 By Volume
7.3 By Average Selling Price
8. Saudi Arabia Automotive Smart Glass OEM and Aftermarket Segmentation
8.1 By Type
8.1.1 Electrochromic Glass
8.1.2 Photochromic Glass
8.1.3 Thermochromic Glass
8.1.4 Self-cleaning Glass
8.1.5 Others
8.2 By End-User
8.2.1 Passenger Vehicles
8.2.2 Commercial Vehicles
8.2.3 Luxury Vehicles
8.2.4 Aftermarket Installations
8.3 By Application
8.3.1 Windshields
8.3.2 Side Windows
8.3.3 Sunroofs
8.3.4 Rear Windows
8.4 By Sales Channel
8.4.1 OEM Sales
8.4.2 Aftermarket Sales
8.4.3 Online Retail
8.4.4 Physical Retail
8.5 By Distribution Mode
8.5.1 Direct Distribution
8.5.2 Indirect Distribution
8.5.3 E-commerce Platforms
8.6 By Price Range
8.6.1 Budget
8.6.2 Mid-range
8.6.3 Premium
8.7 By Policy Support
8.7.1 Government Subsidies
8.7.2 Tax Incentives
8.7.3 Regulatory Support
8.7.4 Others
9. Saudi Arabia Automotive Smart Glass OEM and Aftermarket Competitive Analysis
9.1 Market Share of Key Players
9.2 Cross Comparison of Key Players
9.2.1 Company Name
9.2.2 Group Size (Large, Medium, or Small as per industry convention)
9.2.3 Revenue Growth Rate
9.2.4 Market Penetration Rate
9.2.5 Customer Retention Rate
9.2.6 Pricing Strategy
9.2.7 Product Innovation Rate
9.2.8 Distribution Efficiency
9.2.9 Brand Recognition Score
9.2.10 Customer Satisfaction Index
9.3 SWOT Analysis of Top Players
9.4 Pricing Analysis
9.5 Detailed Profile of Major Companies
9.5.1 Saint-Gobain
9.5.2 AGC Inc.
9.5.3 NSG Group
9.5.4 Guardian Glass
9.5.5 Xinyi Glass Holdings
9.5.6 Fuyao Glass Industry Group
9.5.7 PPG Industries
9.5.8 Corning Incorporated
9.5.9 Asahi Glass Co., Ltd.
9.5.10 Solutia Inc.
9.5.11 Sika AG
9.5.12 3M Company
9.5.13 Eastman Chemical Company
9.5.14 Nippon Sheet Glass Co., Ltd.
9.5.15 Schott AG
10. Saudi Arabia Automotive Smart Glass OEM and Aftermarket End-User Analysis
10.1 Procurement Behavior of Key Ministries
10.1.1 Ministry of Interior
10.1.2 Ministry of Transport
10.1.3 Ministry of Commerce
10.2 Corporate Spend on Infrastructure & Energy
10.2.1 Automotive Sector Investments
10.2.2 Infrastructure Development Projects
10.3 Pain Point Analysis by End-User Category
10.3.1 Cost of Smart Glass Installation
10.3.2 Availability of Skilled Labor
10.3.3 Maintenance and Repair Challenges
10.4 User Readiness for Adoption
10.4.1 Awareness of Smart Glass Benefits
10.4.2 Financial Readiness
10.4.3 Technological Familiarity
10.5 Post-Deployment ROI and Use Case Expansion
10.5.1 Performance Metrics Tracking
10.5.2 Customer Feedback Mechanisms
10.5.3 Future Use Case Development
11. Saudi Arabia Automotive Smart Glass OEM and Aftermarket Future Size, 2025-2030
11.1 By Value
11.2 By Volume
11.3 By Average Selling Price
Go-To-Market Strategy Phase
1. Whitespace Analysis + Business Model Canvas
1.1 Market Gaps Identification
1.2 Business Model Framework
2. Marketing and Positioning Recommendations
2.1 Branding Strategies
2.2 Product USPs
3. Distribution Plan
3.1 Urban Retail Strategies
3.2 Rural NGO Tie-ups
4. Channel & Pricing Gaps
4.1 Underserved Routes
4.2 Pricing Bands
5. Unmet Demand & Latent Needs
5.1 Category Gaps
5.2 Consumer Segments
6. Customer Relationship
6.1 Loyalty Programs
6.2 After-sales Service
7. Value Proposition
7.1 Sustainability Initiatives
7.2 Integrated Supply Chains
8. Key Activities
8.1 Regulatory Compliance
8.2 Branding Efforts
8.3 Distribution Setup
9. Entry Strategy Evaluation
9.1 Domestic Market Entry Strategy
9.1.1 Product Mix Considerations
9.1.2 Pricing Band Strategy
9.1.3 Packaging Approaches
9.2 Export Entry Strategy
9.2.1 Target Countries
9.2.2 Compliance Roadmap
10. Entry Mode Assessment
10.1 Joint Ventures
10.2 Greenfield Investments
10.3 Mergers & Acquisitions
10.4 Distributor Model
11. Capital and Timeline Estimation
11.1 Capital Requirements
11.2 Timelines for Implementation
12. Control vs Risk Trade-Off
12.1 Ownership Considerations
12.2 Partnerships Evaluation
13. Profitability Outlook
13.1 Breakeven Analysis
13.2 Long-term Sustainability Strategies
14. Potential Partner List
14.1 Distributors
14.2 Joint Ventures
14.3 Acquisition Targets
15. Execution Roadmap
15.1 Phased Plan for Market Entry
15.1.1 Market Setup
15.1.2 Market Entry
15.1.3 Growth Acceleration
15.1.4 Scale & Stabilize
15.2 Key Activities and Milestones
15.2.1 Milestone Tracking
15.2.2 Activity Scheduling
Research Methodology
Phase 1: Approach1
Desk Research
- Industry reports from automotive associations and trade bodies in Saudi Arabia
- Market analysis publications focusing on smart glass technologies and applications
- Government publications on automotive regulations and smart technology initiatives
Primary Research
- Interviews with OEM executives and product managers in the automotive sector
- Surveys with aftermarket suppliers and distributors of automotive glass
- Field interviews with automotive engineers specializing in smart glass integration
Validation & Triangulation
- Cross-validation of findings through multiple industry reports and expert opinions
- Triangulation of data from OEMs, aftermarket players, and regulatory bodies
- Sanity checks through expert panel discussions and feedback sessions
Phase 2: Market Size Estimation1
Top-down Assessment
- Analysis of total automotive market size in Saudi Arabia and smart glass penetration rates
- Segmentation by vehicle type (passenger, commercial) and smart glass applications
- Incorporation of government initiatives promoting smart technologies in vehicles
Bottom-up Modeling
- Volume estimates based on production data from local automotive manufacturers
- Cost analysis of smart glass technologies and their integration into vehicles
- Estimation of aftermarket demand based on vehicle age and replacement cycles
Forecasting & Scenario Analysis
- Multi-factor regression analysis considering economic growth and consumer trends
- Scenario modeling based on technological advancements and regulatory changes
- Baseline, optimistic, and pessimistic forecasts through 2030
Phase 3: CATI Sample Composition1
| Scope Item/Segment | Sample Size | Target Respondent Profiles |
|---|---|---|
| OEM Automotive Manufacturers | 100 | Product Managers, R&D Engineers |
| Aftermarket Suppliers of Smart Glass | 80 | Sales Managers, Supply Chain Coordinators |
| Automotive Technology Experts | 60 | Industry Analysts, Technical Consultants |
| Regulatory Bodies and Government Officials | 50 | Policy Makers, Compliance Officers |
| Automotive Repair Shops | 70 | Shop Owners, Service Managers |
Frequently Asked Questions
What is the current market value of the Saudi Arabia Automotive Smart Glass OEM and Aftermarket?
The Saudi Arabia Automotive Smart Glass OEM and Aftermarket market is valued at approximately USD 1.2 billion, reflecting a significant growth trend driven by consumer demand for advanced automotive technologies and energy-efficient solutions.
What types of smart glass technologies are available in the Saudi automotive market?
Which cities in Saudi Arabia are key players in the automotive smart glass market?
What government regulations are influencing the automotive smart glass market in Saudi Arabia?
Other Regional/Country Reports
Indonesia Automotive Smart Glass OEM and Aftermarket Market
Malaysia Automotive Smart Glass OEM and Aftermarket Market
KSA Automotive Smart Glass OEM and Aftermarket Market
APAC Automotive Smart Glass OEM and Aftermarket Market
SEA Automotive Smart Glass OEM and Aftermarket Market
Vietnam Automotive Smart Glass OEM and Aftermarket Market
Other Adjacent Reports
Malaysia Electric Vehicle Components Market
Kuwait Automotive Electronics (ECUs, Sensors, Controllers) Market Size, Share, Growth Drivers, Trends, Opportunities, Competitive Landscape & Forecast 2025–2030UAE Sustainable Automotive Materials Market
Brazil Vehicle Window Tinting Market
India Automotive Sunroof Market Size, Share & Forecast, By Sunroof Type, Vehicle Type & Sales Channel, 2026–2032India Advanced Driver Assistance Systems Market Size, Share & Forecast, By Solution Type, Vehicle Type & Technology, 2026-2031Brazil Building Smart Glass Market
Kuwait Aerospace Glass Market
Why Buy From Us?

What makes us stand out is that our consultants follow Robust, Refine and Result (RRR) methodology. Robust for clear definitions, approaches and sanity checking, Refine for differentiating respondents' facts and opinions, and Result for presenting data with story.

We have set a benchmark in the industry by offering our clients with syndicated and customized market research reports featuring coverage of entire market as well as meticulous research and analyst insights.

While we don't replace traditional research, we flip the method upside down. Our dual approach of Top Bottom & Bottom Top ensures quality deliverable by not just verifying company fundamentals but also looking at the sector and macroeconomic factors.

With one step in the future, our research team constantly tries to show you the bigger picture. We help with some of the tough questions you may encounter along the way: How is the industry positioned? Best marketing channel? KPI's of competitors? By aligning every element, we help maximize success.

Our report gives you instant access to the answers and sources that other companies might choose to hide. We elaborate each steps of research methodology we have used and showcase you the sample size to earn your trust.

If you need any support, we are here! We pride ourselves on universe strength, data quality, and quick, friendly, and professional service.