About the Report
Base Year 2024Thailand Paper Bag Market Overview
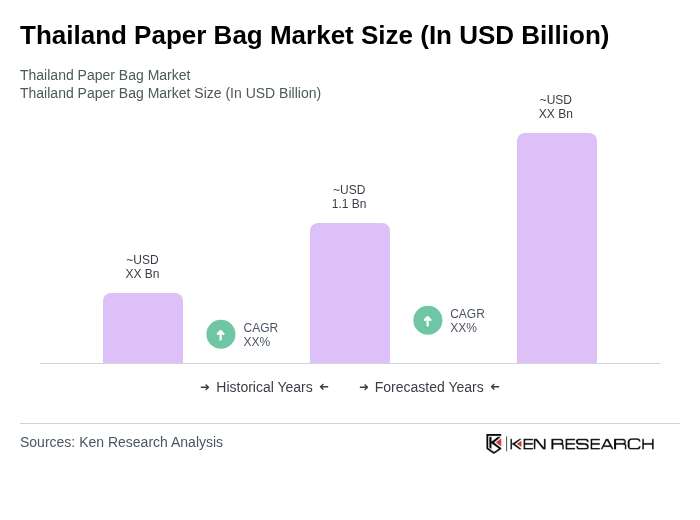
- The Thailand Paper Bag Market is valued at USD 1.1 billion, based on a five-year historical analysis. This growth is primarily driven by increasing environmental awareness, government regulations promoting sustainable packaging, a shift in consumer preferences towards eco-friendly products, and booming e-commerce demand for protective packaging solutions. The demand for paper bags has surged as businesses and consumers alike seek alternatives to plastic, aligning with global sustainability trends.
- Key cities such as Bangkok, Chiang Mai, and Phuket dominate the market due to their high population density, robust retail sectors, and tourism activities. Bangkok, as the capital, serves as a commercial hub, while Chiang Mai and Phuket attract significant tourist traffic, increasing the demand for paper bags in retail and food service sectors.
- The Roadmap on Plastic Waste Management 2018-2030 issued by the Ministry of Natural Resources and Environment in 2018 mandates the reduction of single-use plastics by 30% by 2025 from the 2018 baseline, requiring businesses to phase out thin plastic bags thinner than 36 microns and transition to biodegradable and recyclable packaging solutions with compliance monitored through annual reporting and penalties for non-adherence. This regulation aims to minimize environmental impact and promote sustainable practices across various industries, significantly influencing the paper bag market.
Thailand Paper Bag Market Segmentation
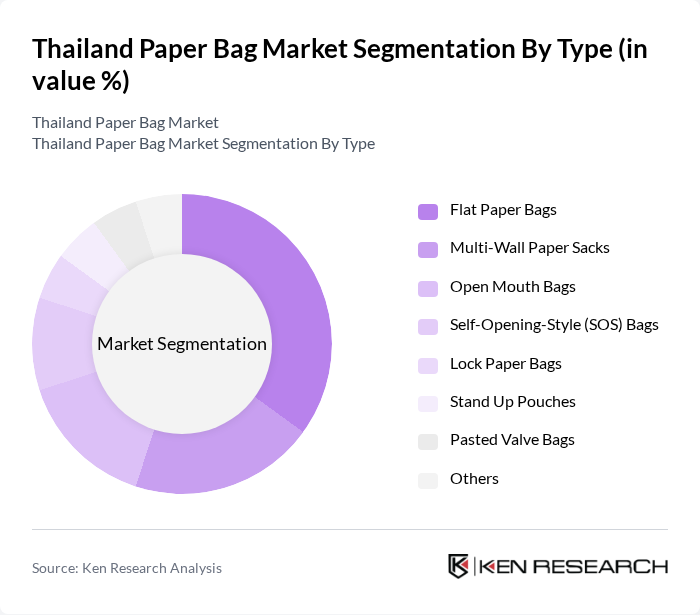
By Type:The market is segmented into various types of paper bags, including Flat Paper Bags, Multi-Wall Paper Sacks, Open Mouth Bags, Self-Opening-Style (SOS) Bags, Lock Paper Bags, Stand Up Pouches, Pasted Valve Bags, and Others. Among these, Flat Paper Bags are the most widely used due to their versatility and cost-effectiveness, making them a preferred choice for retailers and consumers alike.
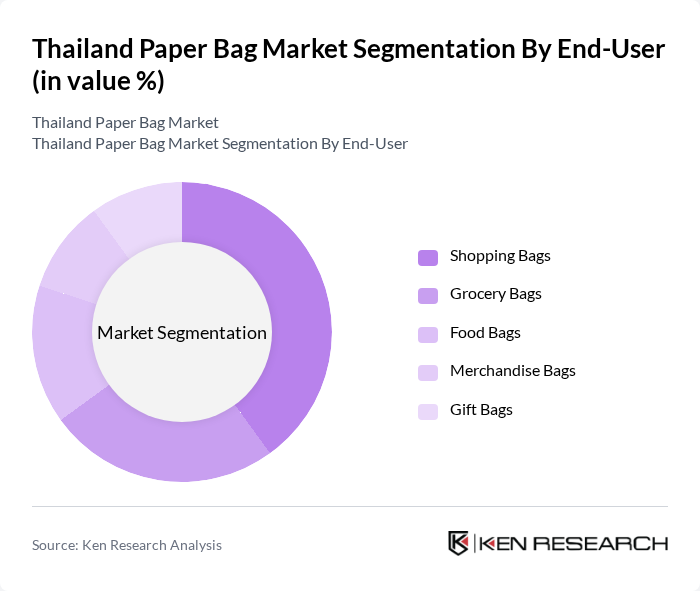
By End-User:The end-user segmentation includes Shopping Bags, Grocery Bags, Food Bags, Merchandise Bags, and Gift Bags. Shopping Bags dominate the market as they are widely used in retail environments, driven by the increasing trend of consumers opting for reusable and eco-friendly options.
Thailand Paper Bag Market Competitive Landscape
The Thailand Paper Bag Market is characterized by a dynamic mix of regional and international players. Leading participants such as SCG Packaging Public Company Limited, Thai Paper Mill Co., Ltd., Tetra Pak (Thailand) Ltd., Siam Paper Public Company Limited, Bangkok Paper Company Limited, Chao Phraya Paper Company Limited, Thai Containers Group, Pulp and Paper (Thailand) Co., Ltd., Paper Pack Co., Ltd., K.P. Paper Co., Ltd., S.P. Paper Co., Ltd., Thai Kraft Paper Co., Ltd., A.P. Paper Co., Ltd., P.P. Paper Co., Ltd., S.P. Packaging Co., Ltd. contribute to innovation, geographic expansion, and service delivery in this space.
Thailand Paper Bag Market Industry Analysis
Growth Drivers
- Increasing Environmental Awareness:The Thai population's environmental consciousness has surged, with 75% of consumers actively seeking eco-friendly products. This shift is driven by educational campaigns and media coverage highlighting the detrimental effects of plastic waste. As a result, the demand for paper bags has increased significantly, with an estimated 18% rise in sales in the future alone. This trend is expected to continue as more consumers prioritize sustainability in their purchasing decisions.
- Government Regulations Promoting Eco-Friendly Products:The Thai government has implemented various regulations to curb plastic usage, including a ban on single-use plastics in major cities. In future, the government allocated approximately THB 1.2 billion to support businesses transitioning to sustainable packaging solutions. These initiatives have spurred the growth of the paper bag market, with a projected increase in production capacity by 25% in the future, as manufacturers adapt to new regulations and consumer preferences.
- Rise in Retail and E-commerce Activities:Thailand's retail sector has experienced robust growth, with e-commerce sales reaching THB 3.5 trillion in the future, a 30% increase from the previous year. This surge in online shopping has led to a higher demand for packaging solutions, including paper bags. Retailers are increasingly adopting paper bags to enhance their brand image and meet consumer expectations for sustainable practices, contributing to a projected 35% growth in paper bag usage in the retail sector by the future.
Market Challenges
- High Production Costs:The production of paper bags involves higher costs compared to plastic alternatives, primarily due to raw material prices and manufacturing processes. In future, the average cost of producing a paper bag was THB 6, while plastic bags cost only THB 3. This price disparity poses a challenge for manufacturers, as they must balance sustainability with affordability to remain competitive in the market, especially among price-sensitive consumers.
- Competition from Plastic Alternatives:Despite the growing demand for paper bags, plastic alternatives remain a formidable competitor due to their lower cost and convenience. In future, plastic bags accounted for 55% of the total packaging market in Thailand. This dominance is reinforced by consumer habits and the widespread availability of plastic products, making it challenging for paper bag manufacturers to capture market share without significant marketing efforts and consumer education.
Thailand Paper Bag Market Future Outlook
The Thailand paper bag market is poised for significant growth, driven by increasing environmental awareness and supportive government policies. As consumers continue to prioritize sustainability, the demand for paper bags is expected to rise, particularly in the retail and food sectors. Innovations in biodegradable materials and production technologies will further enhance market potential. Additionally, collaborations with eco-conscious brands will likely create new avenues for growth, positioning the paper bag industry favorably in the evolving packaging landscape.
Market Opportunities
- Expansion in the Food and Beverage Sector:The food and beverage industry in Thailand is projected to grow by 12% annually, creating a substantial opportunity for paper bag manufacturers. As restaurants and cafes shift towards sustainable packaging, the demand for paper bags for takeout and delivery services is expected to increase significantly, providing a lucrative market segment for producers.
- Growth in Sustainable Packaging Demand:With the global shift towards sustainability, the demand for eco-friendly packaging solutions is on the rise. Thailand's packaging market is expected to reach THB 600 billion by the future, with a significant portion dedicated to sustainable options. This trend presents an opportunity for paper bag manufacturers to innovate and capture market share by offering customized, environmentally friendly products that meet consumer expectations.
Scope of the Report
| Segment | Sub-Segments |
|---|---|
| By Type | Flat Paper Bags Multi-Wall Paper Sacks Open Mouth Bags Self-Opening-Style (SOS) Bags Lock Paper Bags Stand Up Pouches Pasted Valve Bags Others |
| By End-User | Shopping Bags Grocery Bags Food Bags Merchandise Bags Gift Bags |
| By Material Grade | Brown Paper Bags White Paper Bags Laminated Paper Bags Recycled Paper Bags |
| By Distribution Channel | Online Retail Supermarkets/Hypermarkets Convenience Stores Specialty Stores Direct Sales |
| By Region | Central Thailand Northern Thailand Northeastern Thailand Southern Thailand Others |
Key Target Audience
Investors and Venture Capitalist Firms
Government and Regulatory Bodies (e.g., Ministry of Industry, Pollution Control Department)
Manufacturers and Producers
Distributors and Retailers
Packaging Material Suppliers
Environmental NGOs and Advocacy Groups
Logistics and Supply Chain Companies
Trade Associations and Chambers of Commerce
Players Mentioned in the Report:
SCG Packaging Public Company Limited
Thai Paper Mill Co., Ltd.
Tetra Pak (Thailand) Ltd.
Siam Paper Public Company Limited
Bangkok Paper Company Limited
Chao Phraya Paper Company Limited
Thai Containers Group
Pulp and Paper (Thailand) Co., Ltd.
Paper Pack Co., Ltd.
K.P. Paper Co., Ltd.
S.P. Paper Co., Ltd.
Thai Kraft Paper Co., Ltd.
A.P. Paper Co., Ltd.
P.P. Paper Co., Ltd.
S.P. Packaging Co., Ltd.
Table of Contents
Market Assessment Phase
1. Executive Summary and Approach
2. Thailand Paper Bag Market Overview
2.1 Key Insights and Strategic Recommendations
2.2 Thailand Paper Bag Market Overview
2.3 Definition and Scope
2.4 Evolution of Market Ecosystem
2.5 Timeline of Key Regulatory Milestones
2.6 Value Chain & Stakeholder Mapping
2.7 Business Cycle Analysis
2.8 Policy & Incentive Landscape
3. Thailand Paper Bag Market Analysis
3.1 Growth Drivers
3.1.1 Increasing Environmental Awareness
3.1.2 Government Regulations Promoting Eco-Friendly Products
3.1.3 Rise in Retail and E-commerce Activities
3.1.4 Shift from Plastic to Paper Products
3.2 Market Challenges
3.2.1 High Production Costs
3.2.2 Competition from Plastic Alternatives
3.2.3 Supply Chain Disruptions
3.2.4 Limited Consumer Awareness
3.3 Market Opportunities
3.3.1 Expansion in the Food and Beverage Sector
3.3.2 Growth in Sustainable Packaging Demand
3.3.3 Technological Advancements in Production
3.3.4 Export Potential to Neighboring Countries
3.4 Market Trends
3.4.1 Customization and Branding of Paper Bags
3.4.2 Adoption of Biodegradable Materials
3.4.3 Increased Online Shopping and Delivery Services
3.4.4 Collaborations with Eco-Conscious Brands
3.5 Government Regulation
3.5.1 Ban on Single-Use Plastics
3.5.2 Incentives for Sustainable Packaging
3.5.3 Standards for Paper Bag Production
3.5.4 Environmental Impact Assessments
4. SWOT Analysis
5. Stakeholder Analysis
6. Porter's Five Forces Analysis
7. Thailand Paper Bag Market Market Size, 2019-2024
7.1 By Value
7.2 By Volume
7.3 By Average Selling Price
8. Thailand Paper Bag Market Segmentation
8.1 By Type
8.1.1 Flat Paper Bags
8.1.2 Multi-Wall Paper Sacks
8.1.3 Open Mouth Bags
8.1.4 Self-Opening-Style (SOS) Bags
8.1.5 Lock Paper Bags
8.1.6 Stand Up Pouches
8.1.7 Pasted Valve Bags
8.1.8 Others
8.2 By End-User
8.2.1 Shopping Bags
8.2.2 Grocery Bags
8.2.3 Food Bags
8.2.4 Merchandise Bags
8.2.5 Gift Bags
8.3 By Material Grade
8.3.1 Brown Paper Bags
8.3.2 White Paper Bags
8.3.3 Laminated Paper Bags
8.3.4 Recycled Paper Bags
8.4 By Distribution Channel
8.4.1 Online Retail
8.4.2 Supermarkets/Hypermarkets
8.4.3 Convenience Stores
8.4.4 Specialty Stores
8.4.5 Direct Sales
8.5 By Region
8.5.1 Central Thailand
8.5.2 Northern Thailand
8.5.3 Northeastern Thailand
8.5.4 Southern Thailand
8.5.5 Others
9. Thailand Paper Bag Market Competitive Analysis
9.1 Market Share of Key Players
9.2 Cross Comparison of Key Players
9.2.1 Company Name
9.2.2 Revenue (USD Million)
9.2.3 Year-over-Year Revenue Growth Rate (%)
9.2.4 Market Share (%)
9.2.5 Production Capacity (Units/Year)
9.2.6 Geographic Presence (Number of Countries)
9.2.7 Product Portfolio Breadth (Number of SKUs)
9.2.8 R&D Investment as % of Revenue
9.2.9 Customer Retention Rate (%)
9.2.10 Sustainability Certifications
9.3 SWOT Analysis of Top Players
9.4 Pricing Analysis
9.5 Detailed Profile of Major Companies
9.5.1 SCG Packaging Public Company Limited
9.5.2 Thai Paper Mill Co., Ltd.
9.5.3 Tetra Pak (Thailand) Ltd.
9.5.4 Siam Paper Public Company Limited
9.5.5 Bangkok Paper Company Limited
9.5.6 Chao Phraya Paper Company Limited
9.5.7 Thai Containers Group
9.5.8 Pulp and Paper (Thailand) Co., Ltd.
9.5.9 Paper Pack Co., Ltd.
9.5.10 K.P. Paper Co., Ltd.
9.5.11 S.P. Paper Co., Ltd.
9.5.12 Thai Kraft Paper Co., Ltd.
9.5.13 A.P. Paper Co., Ltd.
9.5.14 P.P. Paper Co., Ltd.
9.5.15 S.P. Packaging Co., Ltd.
10. Thailand Paper Bag Market End-User Analysis
10.1 Procurement Behavior of Key Ministries
10.1.1 Government Initiatives for Sustainable Packaging
10.1.2 Budget Allocations for Eco-Friendly Products
10.1.3 Collaboration with Local Manufacturers
10.1.4 Compliance with Environmental Standards
10.2 Corporate Spend on Infrastructure & Energy
10.2.1 Investment in Sustainable Packaging Solutions
10.2.2 Budget for Eco-Friendly Initiatives
10.2.3 Partnerships with Green Suppliers
10.2.4 Focus on Reducing Carbon Footprint
10.3 Pain Point Analysis by End-User Category
10.3.1 Cost of Sustainable Alternatives
10.3.2 Availability of Quality Paper Bags
10.3.3 Consumer Acceptance of Paper Products
10.3.4 Supply Chain Reliability
10.4 User Readiness for Adoption
10.4.1 Awareness of Environmental Impact
10.4.2 Willingness to Pay for Sustainable Options
10.4.3 Availability of Alternatives
10.4.4 Support from Retailers
10.5 Post-Deployment ROI and Use Case Expansion
10.5.1 Measurement of Cost Savings
10.5.2 Customer Feedback and Satisfaction
10.5.3 Opportunities for Product Diversification
10.5.4 Long-term Sustainability Goals
11. Thailand Paper Bag Market Future Size, 2025-2030
11.1 By Value
11.2 By Volume
11.3 By Average Selling Price
Go-To-Market Strategy Phase
12. Whitespace Analysis + Business Model Canvas
12.1 Market Gaps Identification
12.2 Value Proposition Development
12.3 Revenue Streams Analysis
12.4 Customer Segmentation
12.5 Key Partnerships
12.6 Cost Structure
12.7 Channels of Distribution
13. Marketing and Positioning Recommendations
13.1 Branding Strategies
13.2 Product USPs
13.3 Target Audience Identification
13.4 Marketing Channels
13.5 Promotional Activities
14. Distribution Plan
14.1 Urban Retail vs Rural NGO Tie-ups
14.2 Logistics and Supply Chain Management
14.3 Distribution Partnerships
14.4 Inventory Management
14.5 Customer Delivery Options
15. Channel & Pricing Gaps
15.1 Underserved Routes
15.2 Pricing Bands
15.3 Competitor Pricing Analysis
15.4 Value-Based Pricing Strategies
15.5 Discounts and Promotions
16. Unmet Demand & Latent Needs
16.1 Category Gaps
16.2 Consumer Segments
16.3 Product Development Opportunities
16.4 Market Entry Strategies
16.5 Customer Feedback Mechanisms
17. Customer Relationship
17.1 Loyalty Programs
17.2 After-sales Service
17.3 Customer Engagement Strategies
17.4 Feedback and Improvement Processes
17.5 Community Building Initiatives
18. Value Proposition
18.1 Sustainability
18.2 Integrated Supply Chains
18.3 Customer-Centric Approach
18.4 Competitive Advantage
18.5 Long-term Vision
19. Key Activities
19.1 Regulatory Compliance
19.2 Branding
19.3 Distribution Setup
19.4 Quality Assurance
19.5 Market Research
20. Entry Strategy Evaluation
20.1 Domestic Market Entry Strategy
20.1.1 Product Mix
20.1.2 Pricing Band
20.1.3 Packaging
20.2 Export Entry Strategy
20.2.1 Target Countries
20.2.2 Compliance Roadmap
21. Entry Mode Assessment
21.1 JV
21.2 Greenfield
21.3 M&A
21.4 Distributor Model
22. Capital and Timeline Estimation
22.1 Capital Requirements
22.2 Timelines
23. Control vs Risk Trade-Off
23.1 Ownership vs Partnerships
24. Profitability Outlook
24.1 Breakeven Analysis
24.2 Long-term Sustainability
25. Potential Partner List
25.1 Distributors
25.2 JVs
25.3 Acquisition Targets
26. Execution Roadmap
26.1 Phased Plan for Market Entry
26.1.1 Market Setup
26.1.2 Market Entry
26.1.3 Growth Acceleration
26.1.4 Scale & Stabilize
26.2 Key Activities and Milestones
26.2.1 Activity Planning
26.2.2 Milestone Tracking
27. Disclaimer
Research Methodology
Phase 1: Approach1
Desk Research
- Analysis of industry reports from Thai government agencies and trade associations
- Review of market trends and consumer behavior studies published by local universities
- Examination of import/export data related to paper bags from the Ministry of Commerce
Primary Research
- Interviews with key stakeholders in the packaging industry, including manufacturers and suppliers
- Surveys conducted with retailers to understand their preferences and purchasing patterns
- Focus group discussions with consumers to gauge attitudes towards paper bag usage
Validation & Triangulation
- Cross-validation of findings through multiple data sources, including trade publications and market surveys
- Triangulation of insights from interviews and surveys to ensure consistency
- Sanity checks through expert reviews from industry veterans and academic professionals
Phase 2: Market Size Estimation1
Top-down Assessment
- Estimation of total market size based on national consumption data and growth rates
- Segmentation of the market by end-user industries such as retail, food service, and e-commerce
- Incorporation of government regulations promoting sustainable packaging solutions
Bottom-up Modeling
- Collection of sales data from leading paper bag manufacturers in Thailand
- Estimation of production capacities and operational efficiencies of local firms
- Volume and pricing analysis based on different types of paper bags (e.g., grocery, retail, custom)
Forecasting & Scenario Analysis
- Utilization of historical growth trends to project future market developments
- Scenario modeling based on potential shifts in consumer preferences and regulatory changes
- Development of baseline, optimistic, and pessimistic forecasts through 2030
Phase 3: CATI Sample Composition1
| Scope Item/Segment | Sample Size | Target Respondent Profiles |
|---|---|---|
| Retail Sector Paper Bag Usage | 120 | Store Managers, Procurement Officers |
| Food Service Industry Insights | 100 | Restaurant Owners, Supply Chain Managers |
| E-commerce Packaging Preferences | 80 | eCommerce Managers, Logistics Coordinators |
| Consumer Attitudes Towards Sustainability | 100 | General Consumers, Environmental Advocates |
| Manufacturing Insights on Production | 70 | Production Managers, Quality Control Supervisors |
Frequently Asked Questions
What is the current value of the Thailand paper bag market?
The Thailand paper bag market is valued at approximately USD 1.1 billion, reflecting a significant growth trend driven by increasing environmental awareness and government regulations promoting sustainable packaging solutions.
What factors are driving the growth of the paper bag market in Thailand?
Which cities in Thailand are the largest markets for paper bags?
What types of paper bags are most commonly used in Thailand?
Other Regional/Country Reports
Other Adjacent Reports
Qatar Retail Packaging Market
Egypt E-commerce Packaging Market
Vietnam Corrugated Packaging Market Size, Share & Forecast, By Product Type, Application & End-Use Industry, 2026-2031Asia Pacific Flexible Packaging Market Size, Share & Forecast, By Material, Product Type & End-Use Industry, 2026-2031Malaysia Kraft Paper Market
Brazil Recycled Packaging Market
Why Buy From Us?

What makes us stand out is that our consultants follow Robust, Refine and Result (RRR) methodology. Robust for clear definitions, approaches and sanity checking, Refine for differentiating respondents' facts and opinions, and Result for presenting data with story.

We have set a benchmark in the industry by offering our clients with syndicated and customized market research reports featuring coverage of entire market as well as meticulous research and analyst insights.

While we don't replace traditional research, we flip the method upside down. Our dual approach of Top Bottom & Bottom Top ensures quality deliverable by not just verifying company fundamentals but also looking at the sector and macroeconomic factors.

With one step in the future, our research team constantly tries to show you the bigger picture. We help with some of the tough questions you may encounter along the way: How is the industry positioned? Best marketing channel? KPI's of competitors? By aligning every element, we help maximize success.

Our report gives you instant access to the answers and sources that other companies might choose to hide. We elaborate each steps of research methodology we have used and showcase you the sample size to earn your trust.

If you need any support, we are here! We pride ourselves on universe strength, data quality, and quick, friendly, and professional service.