About the Report
Base Year 2024Listen to the audio summary
GCC Electric Trucks Market Overview
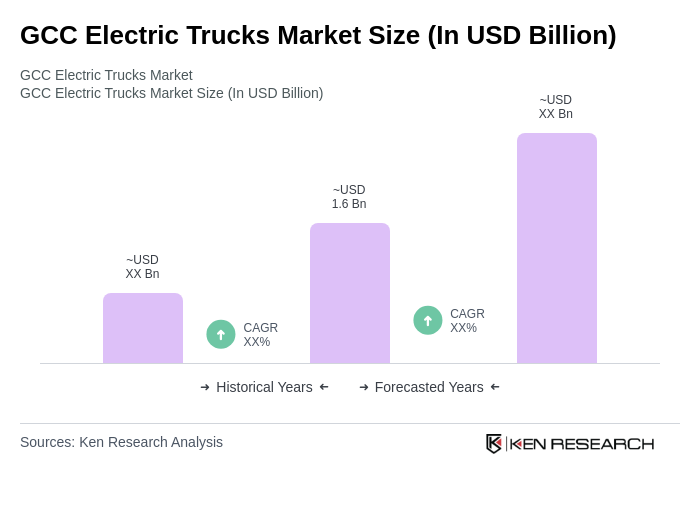
- The GCC Electric Trucks Market is valued at USD 1.6 billion, based on a five-year historical analysis. This growth is primarily driven by increasing government initiatives to promote electric vehicles, rising fuel prices, and a growing emphasis on reducing carbon emissions. The market is also supported by advancements in battery technology, such as improved energy density and faster charging, which enhance the efficiency and range of electric trucks, making them more appealing to consumers and businesses alike .
- Key players in this market include the United Arab Emirates, Saudi Arabia, and Qatar. The UAE leads due to its robust infrastructure and government support for electric vehicles, while Saudi Arabia benefits from its large logistics sector and investments in sustainable transport. Qatar's focus on diversifying its economy and reducing emissions also positions it as a significant player in the electric truck market .
- In 2023, the Saudi Arabian government implemented the "Green Fleet Initiative" under the National Transport and Logistics Strategy, issued by the Ministry of Transport and Logistics Services. This regulation mandates that all new government fleet vehicles procured from 2030 onward must be electric, with compliance requirements for annual reporting and phased procurement targets. The initiative aims to reduce greenhouse gas emissions and promote sustainable transportation solutions, significantly impacting the electric truck market by increasing demand from public sector fleets .
GCC Electric Trucks Market Segmentation
By Type:The market is segmented into various types of electric trucks, including Light Duty Electric Trucks, Medium Duty Electric Trucks, Heavy Duty Electric Trucks, Specialty Electric Trucks (e.g., refuse trucks, utility vehicles), and Pickup Trucks. Each sub-segment caters to different consumer needs and operational requirements, with specific applications in logistics, construction, and municipal services .
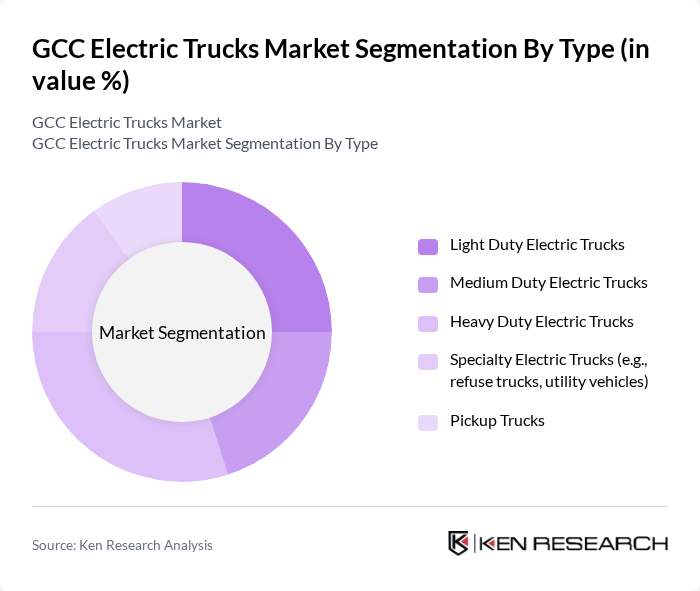
The Heavy Duty Electric Trucks segment is currently dominating the market due to the increasing demand for sustainable solutions in freight transport and logistics. Companies are increasingly adopting heavy-duty electric trucks to reduce operational costs and meet regulatory requirements for emissions. The growing trend towards e-commerce and the need for efficient last-mile delivery solutions further bolster the demand for this segment, making it a key player in the GCC electric trucks market .
By End-User:The end-user segmentation includes Logistics and Transportation Companies, Construction & Infrastructure Firms, Retail & E-commerce Delivery, Government and Municipal Fleets, and Oil & Gas Sector Logistics. Each of these sectors has unique requirements and challenges that electric trucks can address, leading to varied adoption rates across different industries .
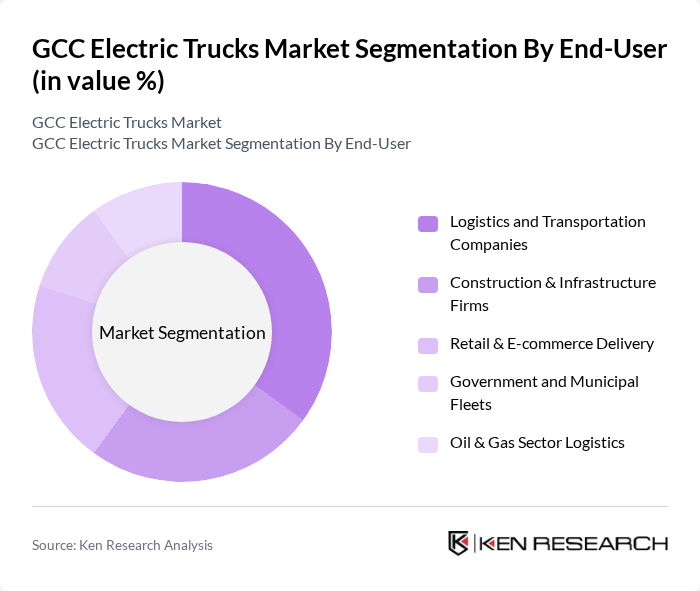
Logistics and Transportation Companies are the leading end-users of electric trucks, driven by the need for cost-effective and environmentally friendly transportation solutions. The rise of e-commerce has further accelerated this trend, as companies seek to optimize their delivery fleets. Additionally, government incentives and regulations promoting electric vehicles are encouraging logistics firms to transition to electric trucks, solidifying their position as the dominant end-user in the market .
GCC Electric Trucks Market Competitive Landscape
The GCC Electric Trucks Market is characterized by a dynamic mix of regional and international players. Leading participants such as Tesla, Inc., BYD Company Limited, Daimler Truck AG, Volvo Group, MAN Truck & Bus SE, Scania AB, Nikola Corporation, Renault Trucks, Foton Motor Group, Hino Motors, Ltd., Freightliner Trucks (Daimler Truck North America), FUSO (Mitsubishi Fuso Truck and Bus Corporation), Isuzu Motors Ltd., Ceer (Saudi Arabia), Ashok Leyland contribute to innovation, geographic expansion, and service delivery in this space.
GCC Electric Trucks Market Industry Analysis
Growth Drivers
- Increasing Environmental Regulations:The GCC region is witnessing a surge in environmental regulations aimed at reducing carbon emissions. For instance, the UAE aims to reduce greenhouse gas emissions by 30% in the future. This regulatory push is driving the adoption of electric trucks, as companies seek to comply with stricter emission standards. In the future, the region is expected to implement more stringent regulations, further incentivizing the transition to electric vehicles, which are crucial for achieving these environmental goals.
- Advancements in Battery Technology:Significant advancements in battery technology are enhancing the performance and affordability of electric trucks. The cost of lithium-ion batteries has decreased by approximately 89% since 2010, making electric trucks more economically viable. In the future, battery energy density is projected to improve by 20%, allowing for longer ranges and faster charging times. This technological progress is crucial for addressing consumer concerns and driving the adoption of electric trucks in the GCC market.
- Government Incentives for Electric Vehicles:Governments across the GCC are introducing various incentives to promote electric vehicle adoption. For example, Saudi Arabia has allocated USD 1.5 billion for electric vehicle infrastructure development. In the future, these incentives are expected to include tax breaks, subsidies, and grants for electric truck purchases, making them more attractive to businesses. Such financial support is essential for overcoming initial cost barriers and accelerating the transition to electric transportation in the region.
Market Challenges
- High Initial Investment Costs:One of the primary challenges facing the GCC electric truck market is the high initial investment required for electric vehicles. The average cost of an electric truck can exceed USD 150,000, significantly higher than traditional diesel trucks, which average around USD 80,000. This price disparity poses a barrier for many logistics companies, particularly small and medium-sized enterprises, hindering widespread adoption despite the long-term savings on fuel and maintenance.
- Limited Charging Infrastructure:The lack of a comprehensive charging infrastructure remains a significant challenge for the electric truck market in the GCC. As of the future, there are only about 1,200 public charging stations across the region, which is insufficient to support a growing fleet of electric trucks. In the future, the demand for charging stations is expected to increase by 50%, highlighting the urgent need for investment in infrastructure to facilitate the transition to electric vehicles.
GCC Electric Trucks Market Future Outlook
The future of the GCC electric truck market appears promising, driven by technological advancements and supportive government policies. As battery technology continues to evolve, electric trucks will become more efficient and cost-effective, addressing consumer concerns about range and charging. Additionally, the expansion of charging infrastructure is expected to accelerate adoption rates. With increasing environmental awareness and a shift towards sustainable logistics, the market is poised for significant growth, fostering innovation and collaboration among stakeholders in the transportation sector.
Market Opportunities
- Expansion of Charging Networks:The development of extensive charging networks presents a significant opportunity for the electric truck market. With an anticipated investment of USD 500 million in the future, the GCC aims to increase the number of charging stations by 60%. This expansion will alleviate range anxiety and encourage more companies to transition to electric trucks, ultimately enhancing market growth.
- Partnerships with Logistics Companies:Collaborations between electric truck manufacturers and logistics companies can drive market growth. In the future, partnerships are expected to increase by 40%, enabling shared resources and expertise. These alliances will facilitate the integration of electric trucks into existing fleets, promoting sustainable practices and reducing operational costs for logistics providers, thereby enhancing the overall market landscape.
Scope of the Report
| Segment | Sub-Segments |
|---|---|
| By Type | Light Duty Electric Trucks Medium Duty Electric Trucks Heavy Duty Electric Trucks Specialty Electric Trucks (e.g., refuse trucks, utility vehicles) Pickup Trucks |
| By End-User | Logistics and Transportation Companies Construction & Infrastructure Firms Retail & E-commerce Delivery Government and Municipal Fleets Oil & Gas Sector Logistics |
| By Application | Freight & Cargo Transport Waste Management & Municipal Services Last-Mile Delivery Construction Material Hauling |
| By Sales Channel | Direct OEM Sales Authorized Dealerships Fleet Leasing & Rental |
| By Distribution Mode | Urban Distribution Rural & Remote Area Distribution Cross-Border & Regional Distribution |
| By Price Range | Entry-Level/Budget Electric Trucks Mid-Range Electric Trucks Premium/Luxury Electric Trucks |
| By Charging Type | Fast DC Charging Standard AC Charging Wireless/Inductive Charging |
Key Target Audience
Investors and Venture Capitalist Firms
Government and Regulatory Bodies (e.g., Ministry of Energy, Ministry of Transport)
Manufacturers and Producers
Logistics and Transportation Companies
Fleet Operators
Charging Infrastructure Providers
Environmental NGOs and Advocacy Groups
Automotive Component Suppliers
Players Mentioned in the Report:
Tesla, Inc.
BYD Company Limited
Daimler Truck AG
Volvo Group
MAN Truck & Bus SE
Scania AB
Nikola Corporation
Renault Trucks
Foton Motor Group
Hino Motors, Ltd.
Freightliner Trucks (Daimler Truck North America)
FUSO (Mitsubishi Fuso Truck and Bus Corporation)
Isuzu Motors Ltd.
Ceer (Saudi Arabia)
Ashok Leyland
Table of Contents
Market Assessment Phase
1. Executive Summary and Approach
2. GCC Electric Trucks Market Overview
2.1 Key Insights and Strategic Recommendations
2.2 GCC Electric Trucks Market Overview
2.3 Definition and Scope
2.4 Evolution of Market Ecosystem
2.5 Timeline of Key Regulatory Milestones
2.6 Value Chain & Stakeholder Mapping
2.7 Business Cycle Analysis
2.8 Policy & Incentive Landscape
3. GCC Electric Trucks Market Analysis
3.1 Growth Drivers
3.1.1 Increasing Environmental Regulations
3.1.2 Advancements in Battery Technology
3.1.3 Rising Fuel Prices
3.1.4 Government Incentives for Electric Vehicles
3.2 Market Challenges
3.2.1 High Initial Investment Costs
3.2.2 Limited Charging Infrastructure
3.2.3 Range Anxiety Among Consumers
3.2.4 Competition from Traditional Trucks
3.3 Market Opportunities
3.3.1 Expansion of Charging Networks
3.3.2 Partnerships with Logistics Companies
3.3.3 Development of Autonomous Electric Trucks
3.3.4 Growing Demand for Sustainable Transportation
3.4 Market Trends
3.4.1 Increasing Adoption of Fleet Electrification
3.4.2 Integration of Smart Technologies
3.4.3 Focus on Total Cost of Ownership
3.4.4 Rise of E-commerce and Last-Mile Delivery Solutions
3.5 Government Regulation
3.5.1 Emission Standards for Commercial Vehicles
3.5.2 Incentives for Electric Vehicle Purchases
3.5.3 Regulations on Charging Infrastructure Development
3.5.4 Policies Supporting Renewable Energy Integration
4. SWOT Analysis
5. Stakeholder Analysis
6. Porter's Five Forces Analysis
7. GCC Electric Trucks Market Market Size, 2019-2024
7.1 By Value
7.2 By Volume
7.3 By Average Selling Price
8. GCC Electric Trucks Market Segmentation
8.1 By Type
8.1.1 Light Duty Electric Trucks
8.1.2 Medium Duty Electric Trucks
8.1.3 Heavy Duty Electric Trucks
8.1.4 Specialty Electric Trucks (e.g., refuse trucks, utility vehicles)
8.1.5 Pickup Trucks
8.2 By End-User
8.2.1 Logistics and Transportation Companies
8.2.2 Construction & Infrastructure Firms
8.2.3 Retail & E-commerce Delivery
8.2.4 Government and Municipal Fleets
8.2.5 Oil & Gas Sector Logistics
8.3 By Application
8.3.1 Freight & Cargo Transport
8.3.2 Waste Management & Municipal Services
8.3.3 Last-Mile Delivery
8.3.4 Construction Material Hauling
8.4 By Sales Channel
8.4.1 Direct OEM Sales
8.4.2 Authorized Dealerships
8.4.3 Fleet Leasing & Rental
8.5 By Distribution Mode
8.5.1 Urban Distribution
8.5.2 Rural & Remote Area Distribution
8.5.3 Cross-Border & Regional Distribution
8.6 By Price Range
8.6.1 Entry-Level/Budget Electric Trucks
8.6.2 Mid-Range Electric Trucks
8.6.3 Premium/Luxury Electric Trucks
8.7 By Charging Type
8.7.1 Fast DC Charging
8.7.2 Standard AC Charging
8.7.3 Wireless/Inductive Charging
9. GCC Electric Trucks Market Competitive Analysis
9.1 Market Share of Key Players
9.2 Cross Comparison of Key Players
9.2.1 Company Name
9.2.2 Group Size (Large, Medium, or Small as per industry convention)
9.2.3 Revenue Growth Rate (GCC region)
9.2.4 Market Penetration Rate (GCC electric truck units deployed/market share)
9.2.5 Order Backlog & Pipeline (number/value of trucks on order)
9.2.6 Average Selling Price (ASP) per Truck
9.2.7 Production Capacity Utilization (units/year, % utilization)
9.2.8 Distribution Network Coverage (number of GCC countries, dealer/service points)
9.2.9 Charging Infrastructure Partnerships (number/value of partnerships in GCC)
9.2.10 Local Assembly/Manufacturing Presence
9.2.11 After-Sales Service Network Strength
9.2.12 R&D Investment in Electric Trucks (as % of revenue)
9.2.13 Product Portfolio Breadth (number of electric truck models offered in GCC)
9.2.14 Brand Recognition/Equity (GCC fleet operator surveys, awards, etc.)
9.3 SWOT Analysis of Top Players
9.4 Pricing Analysis
9.5 Detailed Profile of Major Companies
9.5.1 Tesla, Inc.
9.5.2 BYD Company Limited
9.5.3 Daimler Truck AG
9.5.4 Volvo Group
9.5.5 MAN Truck & Bus SE
9.5.6 Scania AB
9.5.7 Nikola Corporation
9.5.8 Renault Trucks
9.5.9 Foton Motor Group
9.5.10 Hino Motors, Ltd.
9.5.11 Freightliner Trucks (Daimler Truck North America)
9.5.12 FUSO (Mitsubishi Fuso Truck and Bus Corporation)
9.5.13 Isuzu Motors Ltd.
9.5.14 Ceer (Saudi Arabia)
9.5.15 Ashok Leyland
10. GCC Electric Trucks Market End-User Analysis
10.1 Procurement Behavior of Key Ministries
10.1.1 Budget Allocation for Electric Vehicles
10.1.2 Evaluation Criteria for Procurement
10.1.3 Decision-Making Process
10.2 Corporate Spend on Infrastructure & Energy
10.2.1 Investment in Charging Infrastructure
10.2.2 Budget for Fleet Electrification
10.2.3 Energy Management Strategies
10.3 Pain Point Analysis by End-User Category
10.3.1 Cost of Ownership Concerns
10.3.2 Reliability and Maintenance Issues
10.3.3 Availability of Charging Stations
10.4 User Readiness for Adoption
10.4.1 Awareness of Electric Truck Benefits
10.4.2 Training and Support Needs
10.4.3 Financial Incentives for Adoption
10.5 Post-Deployment ROI and Use Case Expansion
10.5.1 Measurement of Cost Savings
10.5.2 Expansion into New Markets
10.5.3 Long-term Sustainability Goals
11. GCC Electric Trucks Market Future Size, 2025-2030
11.1 By Value
11.2 By Volume
11.3 By Average Selling Price
Go-To-Market Strategy Phase
1. Whitespace Analysis + Business Model Canvas
1.1 Identification of Market Gaps
1.2 Value Proposition Development
1.3 Revenue Streams Analysis
1.4 Cost Structure Evaluation
1.5 Key Partnerships Identification
1.6 Customer Segmentation
1.7 Channels of Distribution
2. Marketing and Positioning Recommendations
2.1 Branding Strategies
2.2 Product USPs
2.3 Target Audience Identification
2.4 Communication Strategy
2.5 Digital Marketing Approaches
3. Distribution Plan
3.1 Urban Retail Strategies
3.2 Rural NGO Tie-ups
3.3 E-commerce Integration
3.4 Logistics Partnerships
4. Channel & Pricing Gaps
4.1 Underserved Routes Analysis
4.2 Pricing Bands Evaluation
4.3 Competitor Pricing Comparison
5. Unmet Demand & Latent Needs
5.1 Category Gaps Identification
5.2 Consumer Segments Analysis
5.3 Future Demand Projections
6. Customer Relationship
6.1 Loyalty Programs Development
6.2 After-sales Service Strategies
6.3 Customer Feedback Mechanisms
7. Value Proposition
7.1 Sustainability Initiatives
7.2 Integrated Supply Chains
7.3 Competitive Advantages
8. Key Activities
8.1 Regulatory Compliance
8.2 Branding Initiatives
8.3 Distribution Setup
9. Entry Strategy Evaluation
9.1 Domestic Market Entry Strategy
9.1.1 Product Mix Considerations
9.1.2 Pricing Band Strategy
9.1.3 Packaging Solutions
9.2 Export Entry Strategy
9.2.1 Target Countries Identification
9.2.2 Compliance Roadmap Development
10. Entry Mode Assessment
10.1 Joint Ventures
10.2 Greenfield Investments
10.3 Mergers & Acquisitions
10.4 Distributor Model Evaluation
11. Capital and Timeline Estimation
11.1 Capital Requirements Analysis
11.2 Timelines for Market Entry
12. Control vs Risk Trade-Off
12.1 Ownership vs Partnerships
12.2 Risk Mitigation Strategies
13. Profitability Outlook
13.1 Breakeven Analysis
13.2 Long-term Sustainability Considerations
14. Potential Partner List
14.1 Distributors Identification
14.2 Joint Ventures Opportunities
14.3 Acquisition Targets
15. Execution Roadmap
15.1 Phased Plan for Market Entry
15.1.1 Market Setup
15.1.2 Market Entry
15.1.3 Growth Acceleration
15.1.4 Scale & Stabilize
15.2 Key Activities and Milestones
15.2.1 Milestone Planning
15.2.2 Activity Tracking
Research Methodology
Phase 1: Approach1
Desk Research
- Industry reports from regional transport and logistics associations
- Government publications on electric vehicle adoption and infrastructure development
- Market analysis from energy and automotive sector publications
Primary Research
- Interviews with fleet managers from logistics and transportation companies
- Surveys targeting electric vehicle manufacturers and suppliers
- Field interviews with policymakers and regulatory bodies involved in electric vehicle initiatives
Validation & Triangulation
- Cross-validation of data from multiple industry reports and government sources
- Triangulation of insights from primary interviews with secondary data findings
- Sanity checks through expert panels comprising industry veterans and analysts
Phase 2: Market Size Estimation1
Top-down Assessment
- Analysis of total vehicle sales in the GCC region with a focus on electric trucks
- Segmentation of market size by country and application sectors (e.g., logistics, construction)
- Incorporation of government incentives and policies promoting electric vehicle adoption
Bottom-up Modeling
- Estimation of electric truck sales based on historical growth rates and market trends
- Operational cost analysis for electric trucks versus traditional diesel trucks
- Volume projections based on fleet expansion plans of major logistics companies
Forecasting & Scenario Analysis
- Multi-variable forecasting using economic indicators and fuel price trends
- Scenario analysis based on regulatory changes and technological advancements
- Development of baseline, optimistic, and pessimistic market growth scenarios through 2030
Phase 3: CATI Sample Composition1
| Scope Item/Segment | Sample Size | Target Respondent Profiles |
|---|---|---|
| Logistics and Transportation Companies | 120 | Fleet Managers, Operations Directors |
| Electric Vehicle Manufacturers | 80 | Product Development Managers, Sales Executives |
| Government Regulatory Bodies | 40 | Policy Makers, Environmental Officers |
| Infrastructure Development Firms | 60 | Project Managers, Business Development Leads |
| End-Users in Construction and Delivery Sectors | 50 | Procurement Managers, Sustainability Officers |
Frequently Asked Questions
What is the current value of the GCC Electric Trucks Market?
The GCC Electric Trucks Market is valued at approximately USD 1.6 billion, driven by government initiatives, rising fuel prices, and advancements in battery technology that enhance the efficiency and appeal of electric trucks.
Which countries are leading in the GCC Electric Trucks Market?
What is the "Green Fleet Initiative" in Saudi Arabia?
What types of electric trucks are available in the GCC market?
Other Regional/Country Reports
Indonesia Electric Trucks Market
Malaysia Electric Trucks Market
KSA Electric Trucks Market
APAC Electric Trucks Market
SEA Electric Trucks Market
Other Adjacent Reports
Belgium Battery Technology Market
Colombia Logistics Software MarketMexico Renewable Energy Integration Market
Indonesia Automotive Manufacturing Market Size, Share & Forecast, By Vehicle Type, Powertrain & Geography, 2026–2032Brazil Fleet Management Solutions Market Size, Share & Forecast, By Solution Type, Deployment Model & End-Use Industry, 2026-2031South Korea Sustainable Transportation Market
Saudi Arabia Commercial Vehicle Market Size, Share & Forecast, By Vehicle Type, Powertrain, Usage Type & Sales Channel, 2026-2031Asia Pacific Electric Bus Market Outlook to 2030: Size, Share, Growth and TrendsUAE Hydrogen Fuel Cell Vehicle Market
Why Buy From Us?

What makes us stand out is that our consultants follow Robust, Refine and Result (RRR) methodology. Robust for clear definitions, approaches and sanity checking, Refine for differentiating respondents' facts and opinions, and Result for presenting data with story.

We have set a benchmark in the industry by offering our clients with syndicated and customized market research reports featuring coverage of entire market as well as meticulous research and analyst insights.

While we don't replace traditional research, we flip the method upside down. Our dual approach of Top Bottom & Bottom Top ensures quality deliverable by not just verifying company fundamentals but also looking at the sector and macroeconomic factors.

With one step in the future, our research team constantly tries to show you the bigger picture. We help with some of the tough questions you may encounter along the way: How is the industry positioned? Best marketing channel? KPI's of competitors? By aligning every element, we help maximize success.

Our report gives you instant access to the answers and sources that other companies might choose to hide. We elaborate each steps of research methodology we have used and showcase you the sample size to earn your trust.

If you need any support, we are here! We pride ourselves on universe strength, data quality, and quick, friendly, and professional service.