About the Report
Base Year 2024North America Chocolate Market Overview
- The North America Chocolate Market is valued at USD 34 billion, based on a five-year historical analysis. This growth is primarily driven by increasing consumer demand for premium and artisanal chocolates, a rising trend toward healthier options such as organic and sugar-free varieties, and a growing emphasis on sustainability and ethically sourced ingredients. The market is also supported by the expansion of retail channels, especially e-commerce, and innovative product offerings that cater to diverse consumer preferences .
- The United States and Canada dominate the North American chocolate market due to their large consumer base and established retail infrastructure. The U.S. is particularly influential, with a strong culture of chocolate consumption and high per capita spending on confectionery products. Urban centers such as New York, Los Angeles, and Toronto serve as key hubs for chocolate sales, driven by gifting, seasonal celebrations, and a growing interest in premium and specialty chocolates .
- In recent years, the U.S. government has implemented updated regulations aimed at improving food labeling standards, including for chocolate products. These regulations mandate clearer labeling of ingredients and nutritional information, ensuring that consumers are better informed about the products they purchase. The initiative is part of a broader effort to promote transparency in food production and enhance consumer trust in food safety .
North America Chocolate Market Segmentation
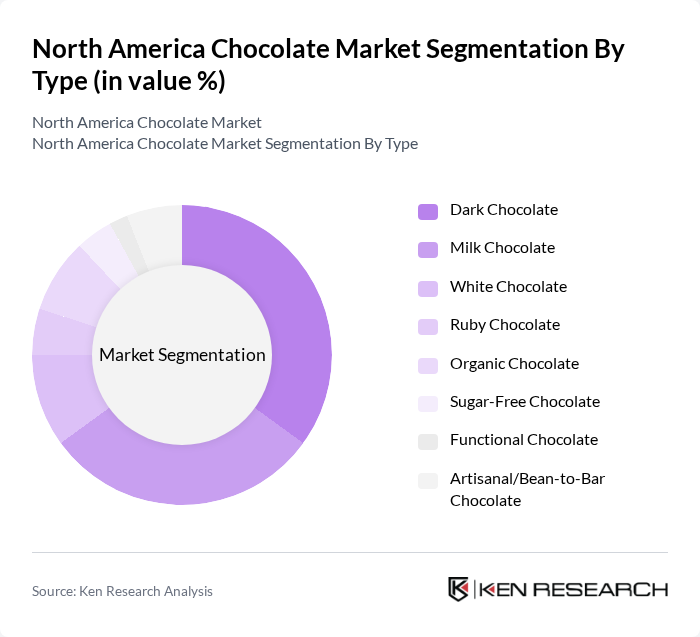
By Type:The chocolate market can be segmented into various types, each catering to different consumer preferences and dietary needs. The primary subsegments include Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate, Organic Chocolate, Sugar-Free Chocolate, Functional Chocolate, and Artisanal/Bean-to-Bar Chocolate. Among these, Dark Chocolate has gained significant popularity due to its perceived health benefits, including higher antioxidant content and lower sugar levels. Consumers are increasingly opting for dark chocolate as a healthier alternative, which has led to its strong presence in the market .
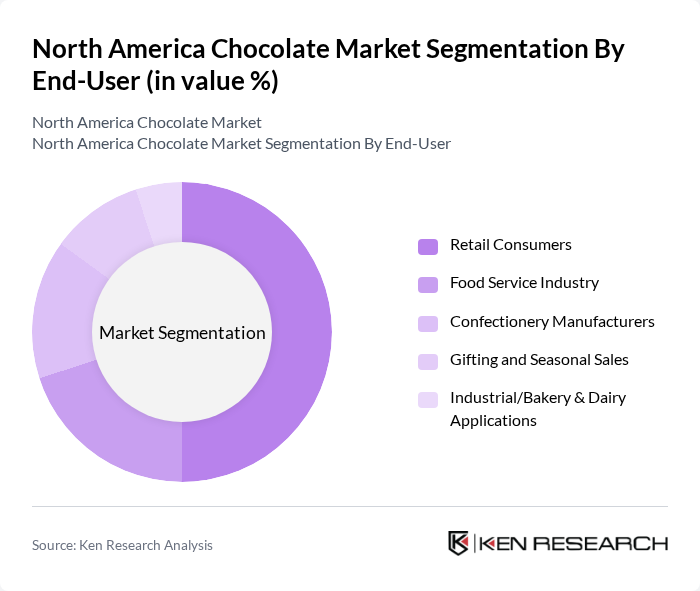
By End-User:The chocolate market is also segmented by end-user categories, which include Retail Consumers, Food Service Industry, Confectionery Manufacturers, Gifting and Seasonal Sales, and Industrial/Bakery & Dairy Applications. The Retail Consumers segment is the largest, driven by the increasing trend of chocolate consumption for personal enjoyment and gifting. The rise of e-commerce and specialty stores has further boosted retail sales, allowing consumers to access a wider variety of chocolate products conveniently .
North America Chocolate Market Competitive Landscape
The North America Chocolate Market is characterized by a dynamic mix of regional and international players. Leading participants such as Mars, Incorporated, The Hershey Company, Mondelez International, Inc., Nestlé USA, Inc., Ferrero USA, Inc., Lindt & Sprüngli (USA) Inc., Ghirardelli Chocolate Company, Godiva Chocolatier, Inc., Tootsie Roll Industries, Inc., Barry Callebaut AG, Chocoladefabriken Lindt & Sprüngli AG, Cargill, Incorporated, Blommer Chocolate Company, See's Candies, Inc., Russell Stover Chocolates LLC contribute to innovation, geographic expansion, and service delivery in this space.
North America Chocolate Market Industry Analysis
Growth Drivers
- Increasing Demand for Premium Chocolate:The North American chocolate market is witnessing a significant shift towards premium products, with sales reaching approximately $24 billion in future. This trend is driven by consumers' willingness to pay more for high-quality ingredients and artisanal craftsmanship. The premium segment is projected to grow as consumers increasingly seek unique flavors and experiences, with a notable 15% increase in sales of premium chocolate brands reported in the last year, according to industry reports.
- Rising Health Consciousness and Demand for Dark Chocolate:Health-conscious consumers are increasingly opting for dark chocolate, which is perceived as a healthier alternative due to its higher cocoa content and lower sugar levels. In future, dark chocolate sales accounted for over $8 billion in North America, reflecting a 10% year-on-year growth. This shift is supported by research indicating that dark chocolate can provide health benefits, such as improved heart health and antioxidant properties, further driving its popularity among consumers.
- Expansion of E-commerce Platforms:The rise of e-commerce has transformed the chocolate purchasing landscape, with online sales growing by 25% in future, reaching approximately $6 billion. This growth is attributed to the convenience of online shopping and the ability to access a wider variety of products. Major retailers and niche brands are increasingly investing in digital marketing strategies to enhance their online presence, catering to the growing demand for home delivery and subscription services in the chocolate sector.
Market Challenges
- Fluctuating Cocoa Prices:The North American chocolate market faces challenges due to the volatility of cocoa prices, which have seen fluctuations of up to 30% in the past year. This instability is primarily driven by climate change, political unrest in cocoa-producing countries, and supply chain disruptions. As cocoa prices rise, manufacturers may struggle to maintain profit margins, potentially leading to increased retail prices and reduced consumer demand for chocolate products.
- Stringent Regulatory Compliance:The chocolate industry in North America is subject to rigorous regulatory standards, including food safety and labeling requirements. Compliance with these regulations can be costly and time-consuming for manufacturers. In future, the average cost of compliance for food manufacturers was estimated at $1.8 million annually, impacting smaller companies disproportionately. This challenge can hinder innovation and market entry for new players, limiting competition and consumer choice.
North America Chocolate Market Future Outlook
The North American chocolate market is poised for continued growth, driven by evolving consumer preferences and innovative product offerings. As health trends persist, the demand for organic and fair-trade chocolate is expected to rise, with sales projected to exceed $4 billion in future. Additionally, the integration of technology in marketing and distribution will enhance consumer engagement, allowing brands to tailor their offerings. Sustainability initiatives will also play a crucial role in shaping the market, as consumers increasingly prioritize eco-friendly practices in their purchasing decisions.
Market Opportunities
- Growth in Organic and Fair-Trade Chocolate:The organic chocolate segment is projected to grow significantly, with sales expected to reach $1.5 billion in future. This growth is driven by increasing consumer awareness of sustainable practices and ethical sourcing, presenting a lucrative opportunity for brands that prioritize organic ingredients and fair-trade certifications.
- Expansion into Untapped Markets:Emerging markets in North America, particularly among younger demographics, present significant growth potential. With millennials and Gen Z showing a preference for unique and artisanal chocolate products, brands can capitalize on this trend by introducing innovative flavors and limited-edition offerings, potentially increasing market share by 20% in these segments.
Scope of the Report
| Segment | Sub-Segments |
|---|---|
| By Type | Dark Chocolate Milk Chocolate White Chocolate Ruby Chocolate Organic Chocolate Sugar-Free Chocolate Functional Chocolate (e.g., fortified, protein, probiotic) Artisanal/Bean-to-Bar Chocolate |
| By End-User | Retail Consumers Food Service Industry Confectionery Manufacturers Gifting and Seasonal Sales Industrial/Bakery & Dairy Applications |
| By Distribution Channel | Supermarkets and Hypermarkets Online Retail Specialty Stores Convenience Stores Duty-Free & Travel Retail |
| By Packaging Type | Boxes Bags Bars Bulk Packaging Gift Packaging |
| By Flavor | Classic Flavors (Milk, Dark, White) Exotic Flavors (e.g., chili, sea salt, matcha) Seasonal Flavors (e.g., pumpkin spice, peppermint) Customized/Personalized Flavors |
| By Price Range | Premium Mid-Range Economy |
| By Occasion | Everyday Consumption Gifting Celebrations Seasonal Events |
Key Target Audience
Investors and Venture Capitalist Firms
Government and Regulatory Bodies (e.g., U.S. Food and Drug Administration, Canadian Food Inspection Agency)
Manufacturers and Producers
Distributors and Retailers
Importers and Exporters
Food and Beverage Industry Associations
Packaging Suppliers
Market Analysts and Economic Development Agencies
Players Mentioned in the Report:
Mars, Incorporated
The Hershey Company
Mondelez International, Inc.
Nestle USA, Inc.
Ferrero USA, Inc.
Lindt & Sprungli (USA) Inc.
Ghirardelli Chocolate Company
Godiva Chocolatier, Inc.
Tootsie Roll Industries, Inc.
Barry Callebaut AG
Chocoladefabriken Lindt & Sprungli AG
Cargill, Incorporated
Blommer Chocolate Company
See's Candies, Inc.
Russell Stover Chocolates LLC
Table of Contents
Market Assessment Phase
1. Executive Summary and Approach
2. North America Chocolate Market Overview
2.1 Key Insights and Strategic Recommendations
2.2 North America Chocolate Market Overview
2.3 Definition and Scope
2.4 Evolution of Market Ecosystem
2.5 Timeline of Key Regulatory Milestones
2.6 Value Chain & Stakeholder Mapping
2.7 Business Cycle Analysis
2.8 Policy & Incentive Landscape
3. North America Chocolate Market Analysis
3.1 Growth Drivers
3.1.1 Increasing Demand for Premium Chocolate
3.1.2 Rising Health Consciousness and Demand for Dark Chocolate
3.1.3 Expansion of E-commerce Platforms
3.1.4 Innovative Product Offerings and Flavors
3.2 Market Challenges
3.2.1 Fluctuating Cocoa Prices
3.2.2 Stringent Regulatory Compliance
3.2.3 Competition from Alternative Snacks
3.2.4 Supply Chain Disruptions
3.3 Market Opportunities
3.3.1 Growth in Organic and Fair-Trade Chocolate
3.3.2 Expansion into Untapped Markets
3.3.3 Collaborations with Local Artisans
3.3.4 Increasing Popularity of Gifting Chocolate Products
3.4 Market Trends
3.4.1 Rise of Vegan and Plant-Based Chocolate
3.4.2 Focus on Sustainable Sourcing
3.4.3 Customization and Personalization of Products
3.4.4 Digital Marketing and Social Media Influence
3.5 Government Regulation
3.5.1 Food Safety Standards
3.5.2 Labeling Requirements
3.5.3 Import Tariffs on Cocoa Products
3.5.4 Environmental Regulations on Packaging
4. SWOT Analysis
5. Stakeholder Analysis
6. Porter's Five Forces Analysis
7. North America Chocolate Market Market Size, 2019-2024
7.1 By Value
7.2 By Volume
7.3 By Average Selling Price
8. North America Chocolate Market Segmentation
8.1 By Type
8.1.1 Dark Chocolate
8.1.2 Milk Chocolate
8.1.3 White Chocolate
8.1.4 Ruby Chocolate
8.1.5 Organic Chocolate
8.1.6 Sugar-Free Chocolate
8.1.7 Functional Chocolate (e.g., fortified, protein, probiotic)
8.1.8 Artisanal/Bean-to-Bar Chocolate
8.2 By End-User
8.2.1 Retail Consumers
8.2.2 Food Service Industry
8.2.3 Confectionery Manufacturers
8.2.4 Gifting and Seasonal Sales
8.2.5 Industrial/Bakery & Dairy Applications
8.3 By Distribution Channel
8.3.1 Supermarkets and Hypermarkets
8.3.2 Online Retail
8.3.3 Specialty Stores
8.3.4 Convenience Stores
8.3.5 Duty-Free & Travel Retail
8.4 By Packaging Type
8.4.1 Boxes
8.4.2 Bags
8.4.3 Bars
8.4.4 Bulk Packaging
8.4.5 Gift Packaging
8.5 By Flavor
8.5.1 Classic Flavors (Milk, Dark, White)
8.5.2 Exotic Flavors (e.g., chili, sea salt, matcha)
8.5.3 Seasonal Flavors (e.g., pumpkin spice, peppermint)
8.5.4 Customized/Personalized Flavors
8.6 By Price Range
8.6.1 Premium
8.6.2 Mid-Range
8.6.3 Economy
8.7 By Occasion
8.7.1 Everyday Consumption
8.7.2 Gifting
8.7.3 Celebrations
8.7.4 Seasonal Events
9. North America Chocolate Market Competitive Analysis
9.1 Market Share of Key Players
9.2 Cross Comparison of Key Players
9.2.1 Company Name
9.2.2 Group Size (Large, Medium, or Small as per industry convention)
9.2.3 Revenue Growth Rate (CAGR, 3-5 years)
9.2.4 Market Share (%)
9.2.5 Product Portfolio Breadth (Number of SKUs/Variants)
9.2.6 Distribution Channel Coverage (Retail, Online, Foodservice, etc.)
9.2.7 Brand Recognition Index (Consumer Awareness/Preference)
9.2.8 Innovation Rate (New Product Launches per Year)
9.2.9 Sustainability Initiatives (e.g., % ethically sourced cocoa)
9.2.10 Profitability Margin (%)
9.3 SWOT Analysis of Top Players
9.4 Pricing Analysis
9.5 Detailed Profile of Major Companies
9.5.1 Mars, Incorporated
9.5.2 The Hershey Company
9.5.3 Mondelez International, Inc.
9.5.4 Nestlé USA, Inc.
9.5.5 Ferrero USA, Inc.
9.5.6 Lindt & Sprüngli (USA) Inc.
9.5.7 Ghirardelli Chocolate Company
9.5.8 Godiva Chocolatier, Inc.
9.5.9 Tootsie Roll Industries, Inc.
9.5.10 Barry Callebaut AG
9.5.11 Chocoladefabriken Lindt & Sprüngli AG
9.5.12 Cargill, Incorporated
9.5.13 Blommer Chocolate Company
9.5.14 See's Candies, Inc.
9.5.15 Russell Stover Chocolates LLC
10. North America Chocolate Market End-User Analysis
10.1 Procurement Behavior of Key Ministries
10.1.1 Government Procurement Policies
10.1.2 Budget Allocations for Chocolate Products
10.1.3 Supplier Selection Criteria
10.2 Corporate Spend on Infrastructure & Energy
10.2.1 Investment in Sustainable Practices
10.2.2 Budget for Marketing and Promotions
10.2.3 Expenditure on Research and Development
10.3 Pain Point Analysis by End-User Category
10.3.1 Quality Assurance Issues
10.3.2 Supply Chain Reliability
10.3.3 Price Sensitivity
10.4 User Readiness for Adoption
10.4.1 Awareness of Product Benefits
10.4.2 Willingness to Pay for Premium Products
10.4.3 Accessibility of Products
10.5 Post-Deployment ROI and Use Case Expansion
10.5.1 Measurement of Customer Satisfaction
10.5.2 Analysis of Repeat Purchase Rates
10.5.3 Expansion into New Market Segments
11. North America Chocolate Market Future Size, 2025-2030
11.1 By Value
11.2 By Volume
11.3 By Average Selling Price
Go-To-Market Strategy Phase
1. Whitespace Analysis + Business Model Canvas
1.1 Market Gaps Identification
1.2 Value Proposition Development
1.3 Revenue Streams Analysis
1.4 Customer Segmentation
1.5 Key Partnerships
1.6 Cost Structure Analysis
1.7 Channels of Distribution
2. Marketing and Positioning Recommendations
2.1 Branding Strategies
2.2 Product USPs
2.3 Target Audience Identification
2.4 Communication Strategy
2.5 Digital Marketing Tactics
3. Distribution Plan
3.1 Urban Retail Strategies
3.2 Rural NGO Tie-ups
3.3 E-commerce Distribution
3.4 Direct-to-Consumer Channels
4. Channel & Pricing Gaps
4.1 Underserved Routes
4.2 Pricing Bands Analysis
4.3 Competitor Pricing Strategies
5. Unmet Demand & Latent Needs
5.1 Category Gaps
5.2 Consumer Segments Analysis
5.3 Emerging Trends
6. Customer Relationship
6.1 Loyalty Programs
6.2 After-sales Service
6.3 Customer Feedback Mechanisms
7. Value Proposition
7.1 Sustainability Initiatives
7.2 Integrated Supply Chains
7.3 Unique Selling Points
8. Key Activities
8.1 Regulatory Compliance
8.2 Branding Efforts
8.3 Distribution Setup
9. Entry Strategy Evaluation
9.1 Domestic Market Entry Strategy
9.1.1 Product Mix Considerations
9.1.2 Pricing Band Strategy
9.1.3 Packaging Innovations
9.2 Export Entry Strategy
9.2.1 Target Countries Identification
9.2.2 Compliance Roadmap Development
10. Entry Mode Assessment
10.1 Joint Ventures
10.2 Greenfield Investments
10.3 Mergers & Acquisitions
10.4 Distributor Model Evaluation
11. Capital and Timeline Estimation
11.1 Capital Requirements Analysis
11.2 Timelines for Market Entry
12. Control vs Risk Trade-Off
12.1 Ownership vs Partnerships
12.2 Risk Mitigation Strategies
13. Profitability Outlook
13.1 Breakeven Analysis
13.2 Long-term Sustainability Strategies
14. Potential Partner List
14.1 Distributors
14.2 Joint Ventures
14.3 Acquisition Targets
15. Execution Roadmap
15.1 Phased Plan for Market Entry
15.1.1 Market Setup
15.1.2 Market Entry
15.1.3 Growth Acceleration
15.1.4 Scale & Stabilize
15.2 Key Activities and Milestones
15.2.1 Milestone Planning
15.2.2 Activity Tracking
Research Methodology
Phase 1: Approach1
Desk Research
- Analysis of industry reports from market research firms focusing on the North American chocolate market
- Review of trade publications and chocolate industry journals for trends and insights
- Examination of government and trade association data on chocolate production and consumption
Primary Research
- Interviews with key stakeholders including chocolate manufacturers and distributors
- Surveys targeting consumers to understand preferences and purchasing behavior
- Focus groups with chocolate retailers to gather insights on market dynamics and challenges
Validation & Triangulation
- Cross-validation of findings through multiple data sources including sales data and consumer surveys
- Triangulation of insights from industry experts and market analysts
- Sanity checks through expert panel reviews to ensure data accuracy and relevance
Phase 2: Market Size Estimation1
Top-down Assessment
- Estimation of market size based on national chocolate consumption statistics and growth rates
- Segmentation of the market by product type (dark, milk, and white chocolate) and distribution channel
- Incorporation of macroeconomic factors influencing consumer spending on chocolate
Bottom-up Modeling
- Collection of sales data from leading chocolate manufacturers to establish baseline figures
- Estimation of average retail prices across different chocolate segments
- Calculation of market size based on volume sold and average pricing across various channels
Forecasting & Scenario Analysis
- Multi-factor regression analysis incorporating variables such as consumer trends and health consciousness
- Scenario modeling based on potential economic shifts and changes in consumer preferences
- Development of baseline, optimistic, and pessimistic forecasts through 2030
Phase 3: CATI Sample Composition1
| Scope Item/Segment | Sample Size | Target Respondent Profiles |
|---|---|---|
| Chocolate Manufacturers | 60 | Production Managers, R&D Directors |
| Retail Chocolate Outlets | 50 | Store Managers, Category Buyers |
| Consumer Preferences | 100 | Chocolate Consumers, Health-Conscious Shoppers |
| Distribution Channels | 40 | Logistics Coordinators, Supply Chain Managers |
| Market Trends Analysis | 40 | Market Analysts, Industry Experts |
Frequently Asked Questions
What is the current value of the North America chocolate market?
The North America chocolate market is valued at approximately USD 34 billion, driven by increasing consumer demand for premium and artisanal chocolates, healthier options, and sustainable ingredients. This growth reflects a significant trend in consumer preferences over the past five years.
Which countries dominate the North American chocolate market?
What are the main types of chocolate available in the North American market?
What factors are driving growth in the North American chocolate market?
Other Regional/Country Reports
Why Buy From Us?

What makes us stand out is that our consultants follow Robust, Refine and Result (RRR) methodology. Robust for clear definitions, approaches and sanity checking, Refine for differentiating respondents' facts and opinions, and Result for presenting data with story.

We have set a benchmark in the industry by offering our clients with syndicated and customized market research reports featuring coverage of entire market as well as meticulous research and analyst insights.

While we don't replace traditional research, we flip the method upside down. Our dual approach of Top Bottom & Bottom Top ensures quality deliverable by not just verifying company fundamentals but also looking at the sector and macroeconomic factors.

With one step in the future, our research team constantly tries to show you the bigger picture. We help with some of the tough questions you may encounter along the way: How is the industry positioned? Best marketing channel? KPI's of competitors? By aligning every element, we help maximize success.

Our report gives you instant access to the answers and sources that other companies might choose to hide. We elaborate each steps of research methodology we have used and showcase you the sample size to earn your trust.

If you need any support, we are here! We pride ourselves on universe strength, data quality, and quick, friendly, and professional service.