About the Report
Base Year 2024Malaysia Virtual Visits Market Overview
- The Malaysia Virtual Visits Market is valued at USD 1.0 billion, based on a five-year historical analysis of telehealth and digital health revenues in Malaysia and their share within the broader Southeast Asia telehealth market. This growth is primarily driven by the increasing adoption of telehealth services accelerated by the COVID-19 pandemic, which led to a rapid increase in virtual consultations and remote monitoring as part of Malaysia’s digital health expansion. The rising demand for convenient and accessible healthcare options, combined with high internet and smartphone penetration and growing comfort with online services, has further fueled this market expansion.
- Key cities such as Kuala Lumpur, Penang, and Johor Bahru dominate the Malaysia Virtual Visits Market due to their advanced healthcare infrastructure, higher concentration of private hospitals, and high internet penetration rates. These urban centers have seen a surge in telehealth adoption, supported by a tech-savvy population and very high national internet usage (over 95 percent of Malaysians online and predominantly mobile-first), which reinforces the preference for virtual consultations alongside traditional in-person visits.
- Telehealth and virtual visits in Malaysia are guided by existing healthcare and data protection frameworks rather than a standalone Telemedicine Act implemented in 2023. The Ministry of Health regulates telemedicine primarily through the Telemedicine Blueprint and subsequent policy directions, while the Medical Act 1971 (Act 50) governs registration and practice of medical practitioners, including those providing care via teleconsultations, and the Personal Data Protection Act 2010 (Act 709) sets requirements on patient data privacy and processing for private-sector healthcare providers. These instruments collectively provide the operational framework for licensing of practitioners, standards of care, and protection of patient information in virtual healthcare services, which supports trust and wider adoption of virtual visits.
Malaysia Virtual Visits Market Segmentation
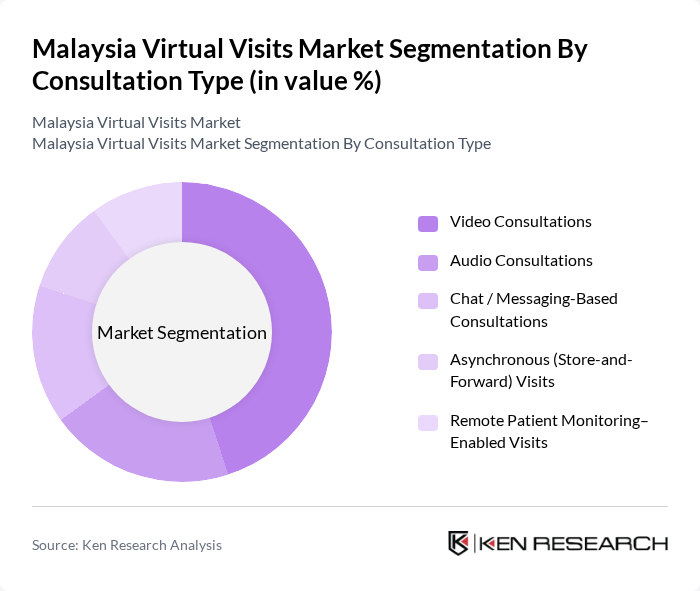
By Consultation Type:The consultation type segment includes various methods through which virtual visits are conducted. The subsegments are Video Consultations, Audio Consultations, Chat / Messaging-Based Consultations, Asynchronous (Store-and-Forward) Visits, and Remote Patient Monitoring–Enabled Visits. Among these, Video Consultations are the most popular due to their ability to provide a face-to-face interaction experience, which enhances patient engagement and satisfaction, and they are the primary mode of consumer-facing telehealth globally and in Southeast Asia. The convenience of accessing healthcare from home, combined with widespread smartphone usage and improvements in broadband and mobile data quality, has led to a significant increase in the usage of video consultations, making it the leading subsegment in this category.
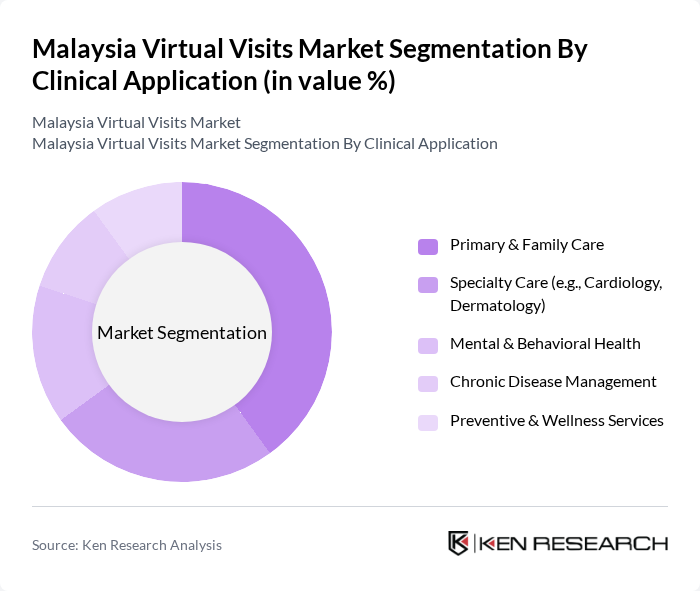
By Clinical Application:This segment encompasses various clinical applications for virtual visits, including Primary & Family Care, Specialty Care (e.g., Cardiology, Dermatology), Mental & Behavioral Health, Chronic Disease Management, and Preventive & Wellness Services. Primary & Family Care is the dominant subsegment, as it addresses a wide range of common acute and chronic conditions and is often the first point of contact for patients in Malaysia’s healthcare system, both in public and private settings. The increasing focus on preventive healthcare, early intervention, and the long-term management of chronic diseases such as diabetes, hypertension, and cardiovascular diseases through remote follow-up and monitoring has further solidified its leading position in the market.
Malaysia Virtual Visits Market Competitive Landscape
The Malaysia Virtual Visits Market is characterized by a dynamic mix of regional and international players. Leading participants such as DoctorOnCall, Teleme, HealthMetrics, BookDoc, GetDoc, Doctor2U, Naluri, ClicknCare, DOC2US, CaringUp, Telehealth Malaysia, MySejahtera (Digital Health Functions), Public Hospital-Linked Virtual Visit Platforms, Private Hospital-Linked Virtual Visit Platforms, Regional / International Telehealth Platforms Active in Malaysia contribute to innovation, geographic expansion, and service delivery in this space.
Malaysia Virtual Visits Market Industry Analysis
Growth Drivers
- Increased Internet Penetration:Malaysia's internet penetration rate reached97%in future, with approximately32 millionusers accessing online services. This widespread connectivity facilitates virtual healthcare access, allowing patients to consult with healthcare providers from their homes. The Malaysian Communications and Multimedia Commission reported a4.8%increase in broadband subscriptions in future, indicating a growing infrastructure that supports telehealth services. Enhanced internet access is crucial for the expansion of virtual visits, enabling more individuals to utilize these services effectively.
- Rising Demand for Remote Healthcare Services:The COVID-19 pandemic significantly accelerated the demand for remote healthcare services in Malaysia, with a reported200%increase in telehealth consultations in future. The Ministry of Health noted that over1.5 millionvirtual consultations were conducted, reflecting a shift in patient preferences towards convenience and safety. This trend is expected to continue as more patients seek accessible healthcare solutions, driving the growth of the virtual visits market in the coming years.
- Government Support for Digital Health Initiatives:The Malaysian government allocatedRM 100 million(approximatelyUSD 24 millionin future to enhance digital health infrastructure. This funding supports initiatives aimed at improving telemedicine services and integrating technology into healthcare systems. The government's commitment to digital health is evident in its National Health Policy, which emphasizes the importance of telehealth in improving healthcare access, particularly in rural areas, thereby fostering market growth for virtual visits.
Market Challenges
- Data Privacy Concerns:Data privacy remains a significant challenge in the Malaysian virtual visits market, with70%of consumers expressing concerns about the security of their personal health information. The Personal Data Protection Act (PDPA) mandates strict compliance, yet many healthcare providers struggle to implement adequate data protection measures. This lack of trust can hinder patient adoption of virtual healthcare services, posing a barrier to market growth and necessitating improved security protocols.
- Limited Digital Literacy Among Certain Demographics:Approximately40%of Malaysia's population, particularly among older adults and rural residents, exhibit limited digital literacy, which poses a challenge for virtual visits adoption. The Digital Economy Corporation reported that many individuals lack the skills to navigate telehealth platforms effectively. This gap in digital literacy can restrict access to virtual healthcare services, highlighting the need for targeted educational initiatives to empower these demographics and enhance market penetration.
Malaysia Virtual Visits Market Future Outlook
The future of the Malaysia virtual visits market appears promising, driven by ongoing technological advancements and increasing consumer acceptance of telehealth solutions. As healthcare providers continue to innovate and enhance their digital offerings, the integration of artificial intelligence and machine learning will likely improve patient experiences. Additionally, the government's commitment to digital health initiatives will further bolster the market, ensuring that virtual consultations become a standard component of healthcare delivery in Malaysia.
Market Opportunities
- Expansion of Telehealth Services:The growing acceptance of telehealth presents a significant opportunity for healthcare providers to expand their services. With over1.5 millionvirtual consultations recorded in future, there is potential for further growth as more patients seek convenient healthcare options. Providers can capitalize on this trend by enhancing their telehealth platforms and offering specialized services tailored to patient needs.
- Integration of AI and Machine Learning:The integration of AI and machine learning technologies into virtual visits can enhance diagnostic accuracy and patient engagement. By leveraging these technologies, healthcare providers can offer personalized treatment plans and improve patient outcomes. The increasing investment in health tech solutions, projected to reachRM 1 billion(approximatelyUSD 240 millionby future, underscores the potential for innovation in the virtual visits market.
Scope of the Report
| Segment | Sub-Segments |
|---|---|
| By Consultation Type | Video Consultations Audio Consultations Chat / Messaging-Based Consultations Asynchronous (Store-and-Forward) Visits Remote Patient Monitoring–Enabled Visits |
| By Clinical Application | Primary & Family Care Specialty Care (e.g., Cardiology, Dermatology) Mental & Behavioral Health Chronic Disease Management Preventive & Wellness Services |
| By End-User | Public Hospitals & Clinics (MOH, University, Military) Private Hospitals & Specialist Centres Standalone GP / Primary Care Clinics Corporate & Occupational Health Programs Individual Self-Pay Consumers |
| By Service Provider Type | Integrated Hospital-Backed Platforms Independent Telehealth Platforms & Aggregators Health Insurer–Backed Platforms Employer / TPA-Backed Health Platforms Pharmacies & Diagnostics-Linked Platforms |
| By Technology Stack | Mobile Applications (Android / iOS) Web-Based Portals Integrated EHR / EMR-Linked Solutions Connected Devices & Wearables AI-Enabled Triage & Decision Support Tools |
| By Payment & Reimbursement Model | Out-of-Pocket (Self-Pay) Private Insurance Reimbursement Corporate / Employer-Sponsored Plans Government & Public Payer Programs Subscription / Membership Models |
| By Geography (Within Malaysia) | Central Region (Klang Valley) Northern Region Southern Region East Coast Region East Malaysia (Sabah & Sarawak) |
Key Target Audience
Investors and Venture Capitalist Firms
Government and Regulatory Bodies (e.g., Ministry of Tourism, Arts and Culture Malaysia)
Healthcare Providers and Institutions
Real Estate Developers
Event Organizers and Planners
Travel and Hospitality Companies
Telecommunications Providers
Tourism Boards and Agencies
Players Mentioned in the Report:
DoctorOnCall
Teleme
HealthMetrics
BookDoc
GetDoc
Doctor2U
Naluri
ClicknCare
DOC2US
CaringUp
Telehealth Malaysia
MySejahtera (Digital Health Functions)
Public Hospital-Linked Virtual Visit Platforms
Private Hospital-Linked Virtual Visit Platforms
Regional / International Telehealth Platforms Active in Malaysia
Table of Contents
Market Assessment Phase
1. Executive Summary and Approach
2. Malaysia Virtual Visits Market Overview
2.1 Key Insights and Strategic Recommendations
2.2 Malaysia Virtual Visits Market Overview
2.3 Definition and Scope
2.4 Evolution of Market Ecosystem
2.5 Timeline of Key Regulatory Milestones
2.6 Value Chain & Stakeholder Mapping
2.7 Business Cycle Analysis
2.8 Policy & Incentive Landscape
3. Malaysia Virtual Visits Market Analysis
3.1 Growth Drivers
3.1.1 Increased Internet Penetration
3.1.2 Rising Demand for Remote Healthcare Services
3.1.3 Technological Advancements in Communication
3.1.4 Government Support for Digital Health Initiatives
3.2 Market Challenges
3.2.1 Data Privacy Concerns
3.2.2 Limited Digital Literacy Among Certain Demographics
3.2.3 Regulatory Hurdles
3.2.4 Competition from Traditional Healthcare Models
3.3 Market Opportunities
3.3.1 Expansion of Telehealth Services
3.3.2 Integration of AI and Machine Learning
3.3.3 Partnerships with Tech Companies
3.3.4 Growing Acceptance of Virtual Consultations
3.4 Market Trends
3.4.1 Shift Towards Hybrid Healthcare Models
3.4.2 Increased Focus on Patient-Centric Solutions
3.4.3 Rise of Mobile Health Applications
3.4.4 Emphasis on Preventive Healthcare
3.5 Government Regulation
3.5.1 Telemedicine Guidelines
3.5.2 Data Protection Laws
3.5.3 Licensing Requirements for Practitioners
3.5.4 Reimbursement Policies for Virtual Visits
4. SWOT Analysis
5. Stakeholder Analysis
6. Porter's Five Forces Analysis
7. Malaysia Virtual Visits Market Market Size, 2019-2024
7.1 By Value
7.2 By Volume
7.3 By Average Selling Price
8. Malaysia Virtual Visits Market Segmentation
8.1 By Consultation Type
8.1.1 Video Consultations
8.1.2 Audio Consultations
8.1.3 Chat / Messaging-Based Consultations
8.1.4 Asynchronous (Store-and-Forward) Visits
8.1.5 Remote Patient Monitoring–Enabled Visits
8.2 By Clinical Application
8.2.1 Primary & Family Care
8.2.2 Specialty Care (e.g., Cardiology, Dermatology)
8.2.3 Mental & Behavioral Health
8.2.4 Chronic Disease Management
8.2.5 Preventive & Wellness Services
8.3 By End-User
8.3.1 Public Hospitals & Clinics (MOH, University, Military)
8.3.2 Private Hospitals & Specialist Centres
8.3.3 Standalone GP / Primary Care Clinics
8.3.4 Corporate & Occupational Health Programs
8.3.5 Individual Self-Pay Consumers
8.4 By Service Provider Type
8.4.1 Integrated Hospital-Backed Platforms
8.4.2 Independent Telehealth Platforms & Aggregators
8.4.3 Health Insurer–Backed Platforms
8.4.4 Employer / TPA-Backed Health Platforms
8.4.5 Pharmacies & Diagnostics-Linked Platforms
8.5 By Technology Stack
8.5.1 Mobile Applications (Android / iOS)
8.5.2 Web-Based Portals
8.5.3 Integrated EHR / EMR-Linked Solutions
8.5.4 Connected Devices & Wearables
8.5.5 AI-Enabled Triage & Decision Support Tools
8.6 By Payment & Reimbursement Model
8.6.1 Out-of-Pocket (Self-Pay)
8.6.2 Private Insurance Reimbursement
8.6.3 Corporate / Employer-Sponsored Plans
8.6.4 Government & Public Payer Programs
8.6.5 Subscription / Membership Models
8.7 By Geography (Within Malaysia)
8.7.1 Central Region (Klang Valley)
8.7.2 Northern Region
8.7.3 Southern Region
8.7.4 East Coast Region
8.7.5 East Malaysia (Sabah & Sarawak)
9. Malaysia Virtual Visits Market Competitive Analysis
9.1 Market Share of Key Players
9.2 Cross Comparison of Key Players
9.2.1 Company Name
9.2.2 Group Size (Large, Medium, or Small as per industry convention)
9.2.3 Customer Acquisition Cost (CAC) per Active User
9.2.4 Average Revenue Per User (ARPU) – Monthly / Annual
9.2.5 Customer Lifetime Value (CLV)
9.2.6 Customer Retention / Churn Rate
9.2.7 Monthly Active Users (MAUs) & Visit Frequency
9.2.8 Conversion Rate (Free to Paid / Registered to First Visit)
9.2.9 EBITDA Margin / Operating Margin
9.2.10 Revenue Mix (B2C vs B2B vs B2G)
9.2.11 Average Consultation Fee & Pricing Positioning
9.2.12 Net Promoter Score (NPS) / User Satisfaction Score
9.2.13 On-Time Service Fulfilment Rate (Wait Time SLAs)
9.2.14 Technology Uptime & Incident Rate
9.3 SWOT Analysis of Top Players
9.4 Pricing Analysis
9.5 Detailed Profile of Major Companies
9.5.1 DoctorOnCall
9.5.2 Teleme
9.5.3 HealthMetrics
9.5.4 BookDoc
9.5.5 GetDoc
9.5.6 Doctor2U
9.5.7 Naluri
9.5.8 ClicknCare
9.5.9 DOC2US
9.5.10 CaringUp
9.5.11 Telehealth Malaysia
9.5.12 MySejahtera (Digital Health Functions)
9.5.13 Public Hospital-Linked Virtual Visit Platforms
9.5.14 Private Hospital-Linked Virtual Visit Platforms
9.5.15 Regional / International Telehealth Platforms Active in Malaysia
10. Malaysia Virtual Visits Market End-User Analysis
10.1 Procurement Behavior of Key Ministries
10.1.1 Budget Allocation for Telehealth
10.1.2 Decision-Making Processes
10.1.3 Preferred Service Providers
10.1.4 Evaluation Criteria
10.1.5 Others
10.2 Corporate Spend on Infrastructure & Energy
10.2.1 Investment in Digital Health Solutions
10.2.2 Budget for Employee Health Programs
10.2.3 Spending on Technology Upgrades
10.2.4 Partnerships with Telehealth Providers
10.2.5 Others
10.3 Pain Point Analysis by End-User Category
10.3.1 Accessibility Issues
10.3.2 Cost Concerns
10.3.3 Quality of Care
10.3.4 Technology Barriers
10.3.5 Others
10.4 User Readiness for Adoption
10.4.1 Awareness Levels
10.4.2 Training Needs
10.4.3 Technology Familiarity
10.4.4 Trust in Virtual Consultations
10.4.5 Others
10.5 Post-Deployment ROI and Use Case Expansion
10.5.1 Cost Savings Analysis
10.5.2 User Engagement Metrics
10.5.3 Service Utilization Rates
10.5.4 Feedback Mechanisms
10.5.5 Others
11. Malaysia Virtual Visits Market Future Size, 2025-2030
11.1 By Value
11.2 By Volume
11.3 By Average Selling Price
Go-To-Market Strategy Phase
1. Whitespace Analysis + Business Model Canvas
1.1 Market Gaps Identification
1.2 Value Proposition Development
1.3 Revenue Streams
1.4 Cost Structure Analysis
1.5 Key Partnerships
1.6 Customer Segments
1.7 Channels
2. Marketing and Positioning Recommendations
2.1 Branding Strategies
2.2 Product USPs
3. Distribution Plan
3.1 Urban Retail vs Rural NGO Tie-Ups
4. Channel & Pricing Gaps
4.1 Underserved Routes
4.2 Pricing Bands
5. Unmet Demand & Latent Needs
5.1 Category Gaps
5.2 Consumer Segments
6. Customer Relationship
6.1 Loyalty Programs
6.2 After-Sales Service
7. Value Proposition
7.1 Sustainability
7.2 Integrated Supply Chains
8. Key Activities
8.1 Regulatory Compliance
8.2 Branding
8.3 Distribution Setup
9. Entry Strategy Evaluation
9.1 Domestic Market Entry Strategy
9.1.1 Product Mix
9.1.2 Pricing Band
9.1.3 Packaging
9.2 Export Entry Strategy
9.2.1 Target Countries
9.2.2 Compliance Roadmap
10. Entry Mode Assessment
10.1 JV
10.2 Greenfield
10.3 M&A
10.4 Distributor Model
11. Capital and Timeline Estimation
11.1 Capital Requirements
11.2 Timelines
12. Control vs Risk Trade-Off
12.1 Ownership vs Partnerships
13. Profitability Outlook
13.1 Breakeven Analysis
13.2 Long-Term Sustainability
14. Potential Partner List
14.1 Distributors
14.2 JVs
14.3 Acquisition Targets
15. Execution Roadmap
15.1 Phased Plan for Market Entry
15.1.1 Market Setup
15.1.2 Market Entry
15.1.3 Growth Acceleration
15.1.4 Scale & Stabilize
15.2 Key Activities and Milestones
Research Methodology
Phase 1: Approach1
Desk Research
- Analysis of government reports on tourism and virtual experiences in Malaysia
- Review of industry publications and market reports on virtual visits and digital tourism trends
- Examination of academic journals focusing on technology adoption in the tourism sector
Primary Research
- Interviews with key stakeholders in the tourism industry, including tour operators and destination managers
- Surveys conducted with consumers who have participated in virtual visits to gauge satisfaction and preferences
- Focus group discussions with technology providers specializing in virtual reality and augmented reality solutions
Validation & Triangulation
- Cross-validation of findings through comparison with international virtual tourism case studies
- Triangulation of data from consumer surveys, expert interviews, and industry reports
- Sanity checks through feedback from a panel of industry experts and academic professionals
Phase 2: Market Size Estimation1
Top-down Assessment
- Estimation of market size based on national tourism revenue and projected growth in virtual experiences
- Segmentation of the market by type of virtual visit (e.g., cultural, educational, adventure)
- Incorporation of trends in digital engagement and consumer behavior shifts post-pandemic
Bottom-up Modeling
- Collection of data from leading virtual tour providers on pricing and service offerings
- Estimation of user adoption rates based on demographic studies and technology penetration
- Calculation of revenue potential based on average spend per virtual visit and expected user base growth
Forecasting & Scenario Analysis
- Multi-factor analysis considering technological advancements, consumer preferences, and economic conditions
- Scenario modeling based on varying levels of market penetration and regulatory impacts
- Development of baseline, optimistic, and pessimistic forecasts through 2030
Phase 3: CATI Sample Composition1
| Scope Item/Segment | Sample Size | Target Respondent Profiles |
|---|---|---|
| Virtual Cultural Tours | 120 | Tour Operators, Cultural Heritage Managers |
| Educational Virtual Visits | 100 | School Administrators, Educational Content Creators |
| Adventure Virtual Experiences | 80 | Adventure Tour Providers, Marketing Managers |
| Corporate Virtual Team Building | 60 | HR Managers, Corporate Event Planners |
| Consumer Feedback on Virtual Visits | 90 | General Consumers, Frequent Travelers |
Frequently Asked Questions
What is the current value of the Malaysia Virtual Visits Market?
The Malaysia Virtual Visits Market is valued at approximately USD 1.0 billion, reflecting significant growth driven by the increased adoption of telehealth services, particularly during the COVID-19 pandemic, which accelerated virtual consultations and remote monitoring.
Which cities are leading in the Malaysia Virtual Visits Market?
What types of consultations are available in the Malaysia Virtual Visits Market?
What are the main clinical applications for virtual visits in Malaysia?
Other Regional/Country Reports
Other Adjacent Reports
Brazil Mobile Health Market
GCC AI in Healthcare Market Size, Share & Forecast, By Solution Type, Application & Care Setting, 2026-2031Global Electronic Health Records Market SWOT Analysis of Epic Systems Corporation & Forecast, 2026-2031GCC Health Data Analytics Market Size, Share, Growth Drivers, Trends, Opportunities & Forecast 2025–2030Saudi Arabia Mental Health Services Market Size, Share, Growth Drivers, Trends, Opportunities & Forecast 2025–2030Middle East Chronic Disease Management Market Size, Share, Growth Drivers, Trends, Opportunities & Forecast 2025–2030Why Buy From Us?

What makes us stand out is that our consultants follow Robust, Refine and Result (RRR) methodology. Robust for clear definitions, approaches and sanity checking, Refine for differentiating respondents' facts and opinions, and Result for presenting data with story.

We have set a benchmark in the industry by offering our clients with syndicated and customized market research reports featuring coverage of entire market as well as meticulous research and analyst insights.

While we don't replace traditional research, we flip the method upside down. Our dual approach of Top Bottom & Bottom Top ensures quality deliverable by not just verifying company fundamentals but also looking at the sector and macroeconomic factors.

With one step in the future, our research team constantly tries to show you the bigger picture. We help with some of the tough questions you may encounter along the way: How is the industry positioned? Best marketing channel? KPI's of competitors? By aligning every element, we help maximize success.

Our report gives you instant access to the answers and sources that other companies might choose to hide. We elaborate each steps of research methodology we have used and showcase you the sample size to earn your trust.

If you need any support, we are here! We pride ourselves on universe strength, data quality, and quick, friendly, and professional service.