About the Report
Base Year 2024Oman Telehealth Market Overview
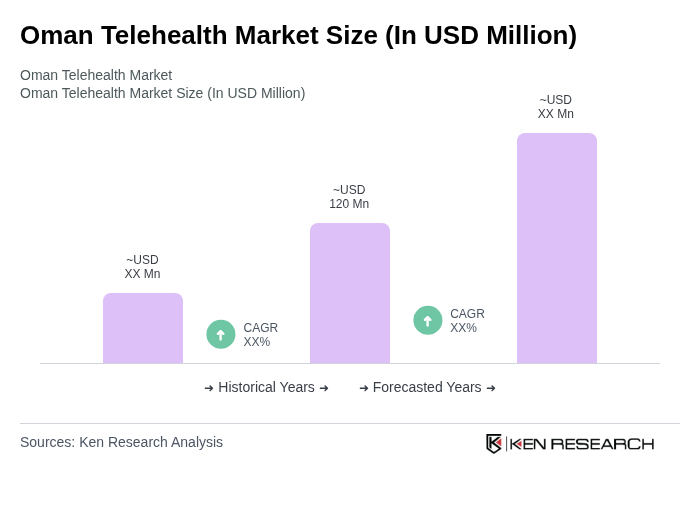
- The Oman Telehealth Market is valued at USD 120 million, based on a five-year historical analysis, in line with regional assessments of the Oman South East telehealth market and Oman-specific telemedicine revenues. This growth is primarily driven by the increasing adoption of digital health solutions, rising healthcare costs, and the need for accessible medical services, especially in remote areas, as teleconsultation, mobile health and remote monitoring are increasingly deployed across hospitals and clinics. The COVID-19 pandemic has further accelerated the shift towards telehealth, as patients and providers seek safer alternatives to traditional in-person consultations and as home-based and virtual care models expand across the GCC.
- Muscat, the capital city, is the dominant hub for telehealth services in Oman due to its advanced healthcare infrastructure and concentration of healthcare professionals, with major providers such as Muscat Private Hospital and Sultan Qaboos University Hospital leading digital health adoption. Other significant regions include Dhofar and Al Batinah, where the government has invested in improving healthcare access and technology as part of broader health system strengthening and digital health initiatives. These areas benefit from a growing population and increasing demand for healthcare services, making them key players in the telehealth market as connectivity and virtual care services expand beyond the capital.
- In 2023, the Omani government implemented a national telehealth strategy aimed at enhancing healthcare delivery through digital platforms, building on ongoing national digital health initiatives that support telemedicine, electronic medical records, and virtual care integration. This initiative includes regulations to ensure data privacy and security, as well as guidelines for telehealth service providers to maintain quality standards, aligned with the provisions of the Personal Data Protection Law (Royal Decree No. 6/2022) issued by the Sultanate of Oman, which mandates lawful processing, confidentiality, and security measures for handling health and other sensitive personal data. The strategy is designed to promote the integration of telehealth into the national healthcare system, improving access to care for all citizens through secure teleconsultation platforms, remote monitoring solutions, and broader digital health infrastructure.
Oman Telehealth Market Segmentation
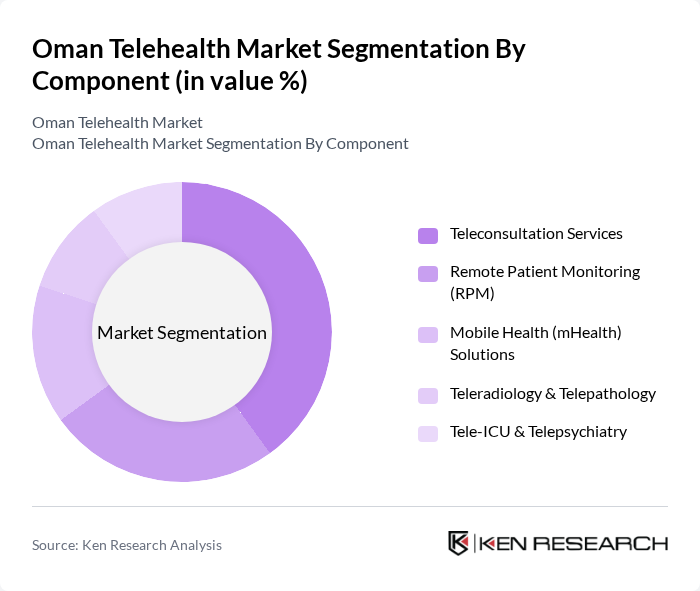
By Component:The components of the telehealth market include various services and technologies that facilitate remote healthcare delivery. Key subsegments include Teleconsultation Services, Remote Patient Monitoring (RPM), Mobile Health (mHealth) Solutions, Teleradiology & Telepathology, and Tele-ICU & Telepsychiatry, which aligns with regional and Oman-specific telehealth and telemedicine segmentation used by industry research. Teleconsultation services are the leading component, supported by widespread adoption across hospitals and clinics, while RPM and mHealth are gaining momentum with the growing burden of chronic diseases and increased smartphone and broadband penetration. Each of these components plays a crucial role in enhancing patient care and improving healthcare outcomes.
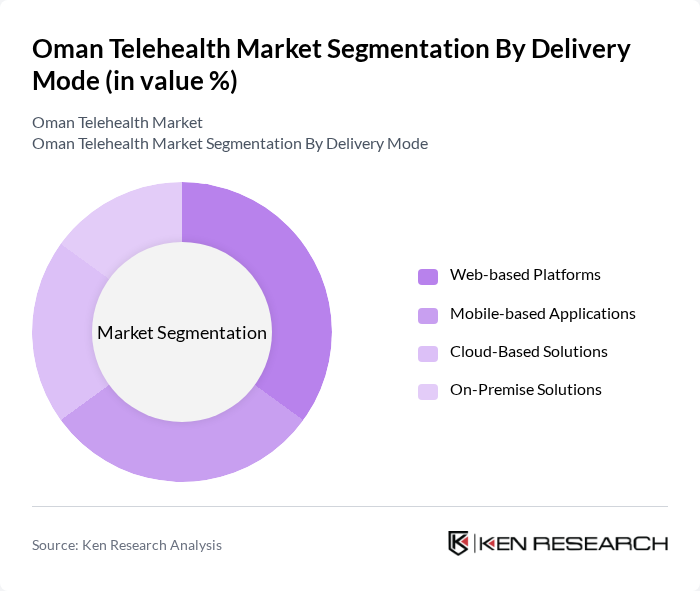
By Delivery Mode:The delivery modes in the telehealth market encompass various platforms through which healthcare services are provided. This includes Web-based Platforms, Mobile-based Applications, Cloud-Based Solutions, and On-Premise Solutions, consistent with regional market classifications for telehealth and telemedicine solutions. Web-based and mobile-based channels are increasingly prominent as patients and providers favor convenient, user-friendly interfaces, while cloud-based solutions are gaining traction among providers seeking scalable and interoperable digital health systems. Each mode offers unique advantages, catering to different user preferences and technological capabilities.
Oman Telehealth Market Competitive Landscape
The Oman Telehealth Market is characterized by a dynamic mix of regional and international players. Leading participants such as Oman Medical Specialty Centre, Muscat Private Hospital, Aster DM Healthcare, Al Nahda Hospital, Sultan Qaboos University Hospital, Dr. Ahmed Al Shamsi Clinic, Al Hayat Hospital, Oman Telehealth Services, Health 360, Al Noor Hospital, Muscat Health Services, Oman Health Authority, Salalah Medical Services, Sohar Hospital, Medcare Hospital contribute to innovation, geographic expansion, and service delivery in this space.
Oman Telehealth Market Industry Analysis
Growth Drivers
- Increasing Demand for Remote Healthcare Services:The demand for remote healthcare services in Oman has surged, with over 1.5 million consultations conducted via telehealth platforms in future. This trend is driven by a growing population of approximately 5.5 million, where around 15% reside in rural areas with limited access to healthcare facilities. The COVID-19 pandemic further accelerated this shift, as 70% of patients expressed a preference for virtual consultations, highlighting a significant market opportunity for telehealth services.
- Government Initiatives Supporting Telehealth Adoption:The Omani government has invested over USD 50 million in digital health and e-health initiatives in future, aiming to enhance healthcare accessibility. The Ministry of Health's strategic plan includes the implementation of telemedicine services across a substantial share of healthcare facilities in future, in line with the national eHealth strategy. Additionally, regulatory frameworks are being established to facilitate telehealth integration, which is expected to increase service utilization significantly in future, reflecting strong governmental support for this sector.
- Rising Prevalence of Chronic Diseases:Chronic diseases are on the rise in Oman, with diabetes affecting about 15% and hypertension affecting roughly one-third of the adult population, according to national and WHO estimates. This increase necessitates ongoing medical care, which telehealth can effectively provide. The World Health Organization reports that managing chronic conditions through telehealth and digital health interventions can reduce unnecessary hospital visits and improve continuity of care. This makes telehealth a vital solution for healthcare providers aiming to improve patient outcomes while managing costs in a strained healthcare system.
Market Challenges
- Limited Internet Connectivity in Rural Areas:Despite advancements, internet access gaps in some rural areas in Oman still pose a barrier to telehealth adoption. The International Telecommunication Union and national data indicate that overall individuals using the internet in Oman are well above 90%, but coverage and quality can be lower in remote and sparsely populated areas. This digital divide limits the reach of telehealth services, preventing equitable healthcare access and hindering the overall growth of the telehealth market in these underserved regions.
- Regulatory Hurdles and Compliance Issues:The telehealth sector in Oman faces regulatory challenges, including the need for compliance with local healthcare laws. Currently, Oman is in the process of strengthening frameworks for digital health and telemedicine under the Ministry of Health and related eHealth strategies, and detailed standardized regulations specific to all telehealth providers are still evolving. Until these are fully implemented, providers may encounter legal uncertainties that could deter investment and slow market growth, affecting service availability and quality.
Oman Telehealth Market Future Outlook
The future of the telehealth market in Oman appears promising, driven by technological advancements and increasing consumer acceptance. As the government continues to invest in digital health infrastructure, the integration of AI and machine learning into telehealth services is expected to enhance patient care and operational efficiency. Furthermore, the growing emphasis on preventive healthcare will likely lead to an expansion of telehealth services, making them more accessible and effective for managing chronic diseases and improving overall health outcomes.
Market Opportunities
- Expansion of Mobile Health Applications:The proliferation of smartphones, with penetration in Oman estimated at over 90% of the population using mobile connections and devices, presents a significant opportunity for mobile health applications. These apps can facilitate remote monitoring and patient engagement, potentially increasing telehealth service usage significantly in future, as more patients seek convenient healthcare solutions.
- Partnerships with Local Healthcare Providers:Collaborating with local healthcare providers can enhance telehealth service delivery. By leveraging existing networks, telehealth companies can improve patient trust and expand their reach. Such partnerships could lead to a notable increase in service adoption rates in future, as local providers can effectively promote telehealth solutions to their patient base.
Scope of the Report
| Segment | Sub-Segments |
|---|---|
| By Component | Teleconsultation Services Remote Patient Monitoring (RPM) Mobile Health (mHealth) Solutions Teleradiology & Telepathology Tele-ICU & Telepsychiatry |
| By Delivery Mode | Web-based Platforms Mobile-based Applications Cloud-Based Solutions On-Premise Solutions |
| By End-User | Hospitals & Healthcare Facilities Clinics & Diagnostic Centers Home Healthcare Corporate & Employee Wellness Programs Pharmacies & Retail Clinics |
| By Application | Teleconsultation Remote Patient Monitoring Tele-ICU & Critical Care Mental Health & Telepsychiatry Others |
| By Connectivity Type | G G Broadband / Wi-Fi Satellite Connectivity |
| By Payment / Reimbursement Model | Out-of-Pocket / Self-Pay Insurance / Payer-Based Employer-Sponsored / Corporate Wellness Government-Funded Programs |
| By Region | Muscat Dhofar Al Batinah Al Dakhiliyah Others |
Key Target Audience
Investors and Venture Capitalist Firms
Government and Regulatory Bodies (e.g., Ministry of Health, Telecommunications Regulatory Authority)
Healthcare Providers and Institutions
Telehealth Technology Developers
Insurance Companies and Health Plans
Pharmaceutical Companies
Healthcare IT Solutions Providers
Medical Device Manufacturers
Players Mentioned in the Report:
Oman Medical Specialty Centre
Muscat Private Hospital
Aster DM Healthcare
Al Nahda Hospital
Sultan Qaboos University Hospital
Dr. Ahmed Al Shamsi Clinic
Al Hayat Hospital
Oman Telehealth Services
Health 360
Al Noor Hospital
Muscat Health Services
Oman Health Authority
Salalah Medical Services
Sohar Hospital
Medcare Hospital
Table of Contents
Market Assessment Phase
1. Executive Summary and Approach
2. Oman Telehealth Market Overview
2.1 Key Insights and Strategic Recommendations
2.2 Oman Telehealth Market Overview
2.3 Definition and Scope
2.4 Evolution of Market Ecosystem
2.5 Timeline of Key Regulatory Milestones
2.6 Value Chain & Stakeholder Mapping
2.7 Business Cycle Analysis
2.8 Policy & Incentive Landscape
3. Oman Telehealth Market Analysis
3.1 Growth Drivers
3.1.1 Increasing Demand for Remote Healthcare Services
3.1.2 Government Initiatives Supporting Telehealth Adoption
3.1.3 Rising Prevalence of Chronic Diseases
3.1.4 Technological Advancements in Healthcare Delivery
3.2 Market Challenges
3.2.1 Limited Internet Connectivity in Rural Areas
3.2.2 Regulatory Hurdles and Compliance Issues
3.2.3 Resistance from Traditional Healthcare Providers
3.2.4 Data Privacy and Security Concerns
3.3 Market Opportunities
3.3.1 Expansion of Mobile Health Applications
3.3.2 Partnerships with Local Healthcare Providers
3.3.3 Investment in Telehealth Infrastructure
3.3.4 Growing Awareness and Acceptance of Telehealth
3.4 Market Trends
3.4.1 Shift Towards Integrated Healthcare Solutions
3.4.2 Increased Use of AI and Machine Learning in Telehealth
3.4.3 Rise of Patient-Centric Care Models
3.4.4 Focus on Preventive Healthcare Services
3.5 Government Regulation
3.5.1 Licensing Requirements for Telehealth Providers
3.5.2 Telehealth Reimbursement Policies
3.5.3 Data Protection Regulations
3.5.4 Standards for Telehealth Technology
4. SWOT Analysis
5. Stakeholder Analysis
6. Porter's Five Forces Analysis
7. Oman Telehealth Market Market Size, 2019-2024
7.1 By Value
7.2 By Volume
7.3 By Average Selling Price
8. Oman Telehealth Market Segmentation
8.1 By Component
8.1.1 Teleconsultation Services
8.1.2 Remote Patient Monitoring (RPM)
8.1.3 Mobile Health (mHealth) Solutions
8.1.4 Teleradiology & Telepathology
8.1.5 Tele-ICU & Telepsychiatry
8.2 By Delivery Mode
8.2.1 Web-based Platforms
8.2.2 Mobile-based Applications
8.2.3 Cloud-Based Solutions
8.2.4 On-Premise Solutions
8.3 By End-User
8.3.1 Hospitals & Healthcare Facilities
8.3.2 Clinics & Diagnostic Centers
8.3.3 Home Healthcare
8.3.4 Corporate & Employee Wellness Programs
8.3.5 Pharmacies & Retail Clinics
8.4 By Application
8.4.1 Teleconsultation
8.4.2 Remote Patient Monitoring
8.4.3 Tele-ICU & Critical Care
8.4.4 Mental Health & Telepsychiatry
8.4.5 Others
8.5 By Connectivity Type
8.5.1 4G
8.5.2 5G
8.5.3 Broadband / Wi-Fi
8.5.4 Satellite Connectivity
8.6 By Payment / Reimbursement Model
8.6.1 Out-of-Pocket / Self-Pay
8.6.2 Insurance / Payer-Based
8.6.3 Employer-Sponsored / Corporate Wellness
8.6.4 Government-Funded Programs
8.7 By Region
8.7.1 Muscat
8.7.2 Dhofar
8.7.3 Al Batinah
8.7.4 Al Dakhiliyah
8.7.5 Others
9. Oman Telehealth Market Competitive Analysis
9.1 Market Share of Key Players
9.2 Cross Comparison of Key Players
9.2.1 Company Name
9.2.2 Group Size (Large, Medium, or Small as per industry convention)
9.2.3 Number of Teleconsultations per Year
9.2.4 Active Monthly Users (MAUs)
9.2.5 Average Revenue Per User (ARPU)
9.2.6 Customer Acquisition Cost (CAC)
9.2.7 Customer Lifetime Value (CLV)
9.2.8 Churn Rate
9.2.9 EBITDA Margin from Telehealth Operations
9.2.10 Average Consultation Success / Completion Rate
9.2.11 Market Penetration (Share of Addressable Population Served)
9.2.12 Net Promoter Score (NPS)
9.3 SWOT Analysis of Top Players
9.4 Pricing Analysis
9.5 Detailed Profile of Major Companies
9.5.1 Oman Medical Specialty Centre
9.5.2 Muscat Private Hospital
9.5.3 Aster DM Healthcare
9.5.4 Al Nahda Hospital
9.5.5 Sultan Qaboos University Hospital
9.5.6 Dr. Ahmed Al Shamsi Clinic
9.5.7 Al Hayat Hospital
9.5.8 Oman Telehealth Services
9.5.9 Health 360
9.5.10 Al Noor Hospital
9.5.11 Muscat Health Services
9.5.12 Oman Health Authority
9.5.13 Salalah Medical Services
9.5.14 Sohar Hospital
9.5.15 Medcare Hospital
10. Oman Telehealth Market End-User Analysis
10.1 Procurement Behavior of Key Ministries
10.1.1 Ministry of Health
10.1.2 Ministry of Education
10.1.3 Ministry of Social Development
10.1.4 Others
10.2 Corporate Spend on Infrastructure & Energy
10.2.1 Healthcare Infrastructure Investments
10.2.2 Technology Upgrades
10.2.3 Training and Development
10.2.4 Others
10.3 Pain Point Analysis by End-User Category
10.3.1 Patients
10.3.2 Healthcare Providers
10.3.3 Insurance Companies
10.3.4 Others
10.4 User Readiness for Adoption
10.4.1 Awareness Levels
10.4.2 Technological Proficiency
10.4.3 Trust in Telehealth Services
10.4.4 Others
10.5 Post-Deployment ROI and Use Case Expansion
10.5.1 Cost Savings
10.5.2 Improved Patient Outcomes
10.5.3 Scalability of Services
10.5.4 Others
11. Oman Telehealth Market Future Size, 2025-2030
11.1 By Value
11.2 By Volume
11.3 By Average Selling Price
Go-To-Market Strategy Phase
1. Whitespace Analysis + Business Model Canvas
1.1 Market Gaps Identification
1.2 Business Model Development
2. Marketing and Positioning Recommendations
2.1 Branding Strategies
2.2 Product USPs
3. Distribution Plan
3.1 Urban Retail vs Rural NGO Tie-ups
4. Channel & Pricing Gaps
4.1 Underserved Routes
4.2 Pricing Bands
5. Unmet Demand & Latent Needs
5.1 Category Gaps
5.2 Consumer Segments
6. Customer Relationship
6.1 Loyalty Programs
6.2 After-sales Service
7. Value Proposition
7.1 Sustainability
7.2 Integrated Supply Chains
8. Key Activities
8.1 Regulatory Compliance
8.2 Branding
8.3 Distribution Setup
9. Entry Strategy Evaluation
9.1 Domestic Market Entry Strategy
9.1.1 Product Mix
9.1.2 Pricing Band
9.1.3 Packaging
9.2 Export Entry Strategy
9.2.1 Target Countries
9.2.2 Compliance Roadmap
10. Entry Mode Assessment
10.1 JV
10.2 Greenfield
10.3 M&A
10.4 Distributor Model
11. Capital and Timeline Estimation
11.1 Capital Requirements
11.2 Timelines
12. Control vs Risk Trade-Off
12.1 Ownership vs Partnerships
13. Profitability Outlook
13.1 Breakeven Analysis
13.2 Long-term Sustainability
14. Potential Partner List
14.1 Distributors
14.2 JVs
14.3 Acquisition Targets
15. Execution Roadmap
15.1 Phased Plan for Market Entry
15.1.1 Market Setup
15.1.2 Market Entry
15.1.3 Growth Acceleration
15.1.4 Scale & Stabilize
15.2 Key Activities and Milestones
15.2.1 Activity Planning
15.2.2 Milestone Tracking
Research Methodology
Phase 1: Approach1
Desk Research
- Analysis of government health reports and telehealth policy documents from the Ministry of Health, Oman
- Review of industry publications and market reports focusing on telehealth trends in the Middle East
- Examination of demographic and health statistics from the National Centre for Statistics and Information (NCSI) of Oman
Primary Research
- Interviews with healthcare providers and telehealth service operators in Oman
- Surveys conducted with patients utilizing telehealth services to understand user experience and satisfaction
- Focus group discussions with healthcare professionals to gather insights on telehealth adoption barriers and facilitators
Validation & Triangulation
- Cross-validation of findings through comparison with regional telehealth market data
- Triangulation of insights from primary interviews with secondary data sources
- Sanity checks through expert panel reviews comprising healthcare analysts and telehealth specialists
Phase 2: Market Size Estimation1
Top-down Assessment
- Estimation of telehealth market size based on national healthcare expenditure and digital health adoption rates
- Segmentation of the market by service type, including remote consultations, mental health services, and chronic disease management
- Incorporation of government initiatives promoting telehealth as part of the national health strategy
Bottom-up Modeling
- Collection of data on the number of telehealth consultations conducted by leading service providers
- Estimation of average revenue per consultation based on pricing models of telehealth services
- Calculation of total market size by multiplying the number of consultations by average revenue
Forecasting & Scenario Analysis
- Multi-factor regression analysis incorporating variables such as internet penetration, smartphone usage, and healthcare access
- Scenario modeling based on potential regulatory changes and shifts in consumer behavior towards telehealth
- Development of baseline, optimistic, and pessimistic forecasts for market growth through 2030
Phase 3: CATI Sample Composition1
| Scope Item/Segment | Sample Size | Target Respondent Profiles |
|---|---|---|
| Healthcare Providers | 80 | Doctors, Clinic Managers, Telehealth Coordinators |
| Patients Using Telehealth Services | 120 | Telehealth Users, Chronic Disease Patients, Mental Health Patients |
| Healthcare Policy Makers | 40 | Health Ministry Officials, Regulatory Bodies, Health Policy Analysts |
| Telehealth Technology Providers | 60 | Technology Developers, IT Managers, Product Managers |
| Insurance Companies | 50 | Health Insurance Underwriters, Claims Managers, Product Development Officers |
Frequently Asked Questions
What is the current value of the Oman Telehealth Market?
The Oman Telehealth Market is valued at approximately USD 120 million, reflecting significant growth driven by the increasing adoption of digital health solutions and the demand for accessible medical services, particularly in remote areas.
What factors are driving the growth of telehealth in Oman?
How has the COVID-19 pandemic impacted telehealth services in Oman?
Which regions in Oman are leading in telehealth services?
Other Regional/Country Reports
Indonesia Telehealth Market Size, Share, Growth Drivers, Trends, Opportunities & Forecast 2025–2030
Malaysia Telehealth Market Size, Share, Growth Drivers, Trends, Opportunities & Forecast 2025–2030
KSA Telehealth Market Size, Share, Growth Drivers, Trends, Opportunities & Forecast 2025–2030
APAC Telehealth Market Size, Share, Growth Drivers, Trends, Opportunities & Forecast 2025–2030
SEA Telehealth Market Size, Share, Growth Drivers, Trends, Opportunities & Forecast 2025–2030
Vietnam Telehealth Market Size, Share, Growth Drivers, Trends, Opportunities & Forecast 2025–2030
Other Adjacent Reports
Qatar Mobile Health Market
India Healthcare IT Market Size, Share & Forecast, By Solution Type, Deployment Model & Customer Type, 2025-2032Global Electronic Health Records Market SWOT Analysis of Epic Systems Corporation & Forecast, 2026-2031GCC AI in Healthcare Market Size, Share & Forecast, By Solution Type, Application & Care Setting, 2026-2031United States Cloud Computing in Healthcare Market Outlook to 2030: Size, Share, Growth and TrendsJapan Teleradiology Market Report Size Share Growth Drivers Trends Opportunities & Forecast 2025–2030Middle East Chronic Disease Management Market Size, Share, Growth Drivers, Trends, Opportunities & Forecast 2025–2030Why Buy From Us?

What makes us stand out is that our consultants follow Robust, Refine and Result (RRR) methodology. Robust for clear definitions, approaches and sanity checking, Refine for differentiating respondents' facts and opinions, and Result for presenting data with story.

We have set a benchmark in the industry by offering our clients with syndicated and customized market research reports featuring coverage of entire market as well as meticulous research and analyst insights.

While we don't replace traditional research, we flip the method upside down. Our dual approach of Top Bottom & Bottom Top ensures quality deliverable by not just verifying company fundamentals but also looking at the sector and macroeconomic factors.

With one step in the future, our research team constantly tries to show you the bigger picture. We help with some of the tough questions you may encounter along the way: How is the industry positioned? Best marketing channel? KPI's of competitors? By aligning every element, we help maximize success.

Our report gives you instant access to the answers and sources that other companies might choose to hide. We elaborate each steps of research methodology we have used and showcase you the sample size to earn your trust.

If you need any support, we are here! We pride ourselves on universe strength, data quality, and quick, friendly, and professional service.