About the Report
Base Year 2024Qatar Investment Banking Market Overview
- The Qatar Investment Banking Market is valued at USD 200 million, based on a five-year historical analysis. This growth is primarily driven by the increasing demand for financial advisory services, particularly in mergers and acquisitions, as well as the expansion of capital markets. The market has seen a surge in investment activities, supported by a robust economic environment and government initiatives aimed at diversifying the economy.
- Doha is the dominant city in the Qatar Investment Banking Market, primarily due to its status as the capital and economic hub of the country. The presence of major financial institutions and a favorable regulatory environment contribute to its leadership. Additionally, the city's strategic location and infrastructure development have attracted both local and international investors, further solidifying its position in the market.
- The Financial Institutions Directive No. (15/2021), issued by the Qatar Central Bank in 2021, governs investment banking activities by requiring licensing for advisory, underwriting, and brokerage services with minimum capital thresholds of QAR 10 million and ongoing compliance reporting for risk management and anti-money laundering. This framework includes stricter compliance measures for financial institutions and promotes the adoption of digital technologies. The initiative is designed to foster investor confidence and ensure the stability of the financial system, thereby supporting the growth of the investment banking market.
Qatar Investment Banking Market Segmentation
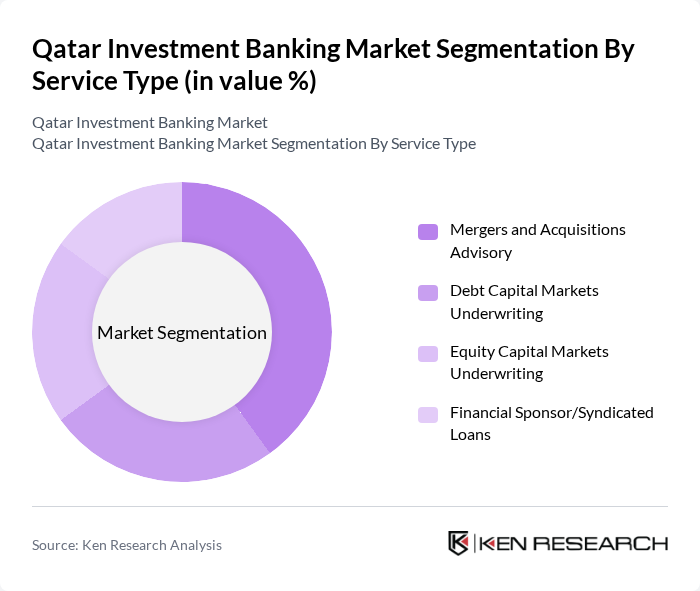
By Service Type:The service type segmentation includes various financial services offered by investment banks. The primary subsegments are Mergers and Acquisitions Advisory, Debt Capital Markets Underwriting, Equity Capital Markets Underwriting, and Financial Sponsor/Syndicated Loans. Mergers and Acquisitions Advisory is currently the leading subsegment, driven by a surge in corporate restructuring and strategic partnerships among businesses seeking growth opportunities.
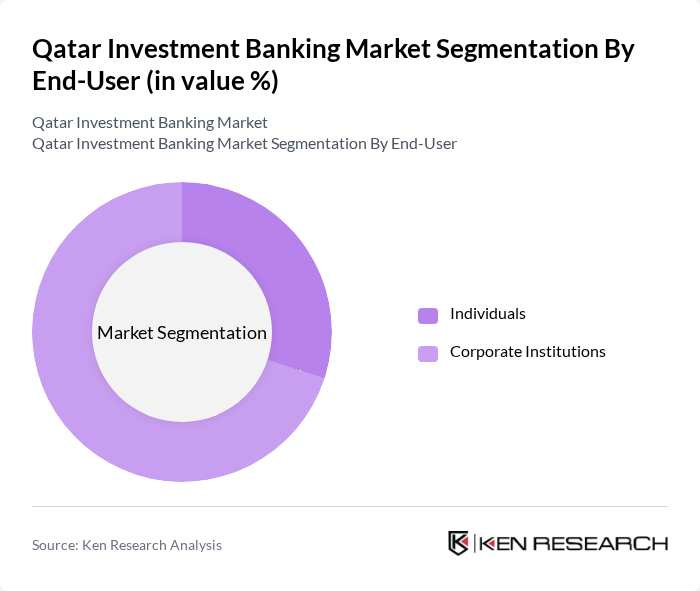
By End-User:The end-user segmentation encompasses the various clients that utilize investment banking services. The primary subsegments include Individuals and Corporate Institutions. Corporate Institutions dominate this segment, as they frequently engage in complex financial transactions, including mergers, acquisitions, and capital raising activities, which require specialized advisory services.
Qatar Investment Banking Market Competitive Landscape
The Qatar Investment Banking Market is characterized by a dynamic mix of regional and international players. Leading participants such as Qatar National Bank, Doha Bank, Commercial Bank of Qatar, Qatar Islamic Bank, Masraf Al Rayan, Ahli Bank, Al Khalij Commercial Bank, Qatar First Bank, Investment Bank of Qatar, Barwa Bank, Al Rayan Investment, QInvest, Qatar Financial Centre, Qatar Development Bank, Gulf International Bank contribute to innovation, geographic expansion, and service delivery in this space.
Qatar Investment Banking Market Industry Analysis
Growth Drivers
- Increasing Foreign Direct Investment:Qatar has seen a significant rise in foreign direct investment (FDI), reaching approximately $25 billion in future. This influx is driven by the country’s strategic location, favorable business environment, and government initiatives aimed at attracting international investors. The Qatar Investment Authority has been actively promoting sectors such as real estate, energy, and technology, which are expected to further enhance the investment landscape, thereby boosting the investment banking sector.
- Government Infrastructure Projects:The Qatari government has allocated over $300 billion for infrastructure projects as part of its National Vision 2030. This includes developments in transportation, healthcare, and education. Such large-scale projects create substantial demand for investment banking services, including project financing and advisory services. The ongoing preparations for the FIFA World Cup have also accelerated infrastructure investments, further stimulating the banking sector's growth.
- Rising Demand for Financial Services:The demand for diverse financial services in Qatar is on the rise, with the banking sector witnessing a growth in assets, which reached $600 billion in future. This growth is fueled by an expanding middle class and increasing consumer awareness of financial products. As more individuals and businesses seek tailored financial solutions, investment banks are positioned to capitalize on this trend by offering innovative products and services to meet evolving client needs.
Market Challenges
- Regulatory Compliance Costs:Investment banks in Qatar face significant regulatory compliance costs, estimated at around $1.5 billion annually. The stringent regulations imposed by the Qatar Central Bank and other regulatory bodies require banks to invest heavily in compliance systems and processes. This financial burden can limit profitability and hinder the ability to invest in growth initiatives, posing a challenge for banks operating in the competitive landscape.
- Competition from Regional Banks:The Qatari investment banking sector is increasingly competitive, with regional banks from the Gulf Cooperation Council (GCC) entering the market. These banks often have established reputations and extensive networks, making it challenging for local banks to maintain market share. The competition is further intensified by the aggressive pricing strategies employed by these regional players, which can erode profit margins for Qatari banks.
Qatar Investment Banking Market Future Outlook
The future of the Qatar investment banking market appears promising, driven by ongoing economic diversification efforts and a commitment to innovation. As the government continues to invest in infrastructure and technology, banks are likely to enhance their service offerings, particularly in digital banking and wealth management. Additionally, the increasing focus on sustainable finance will create new avenues for growth, positioning Qatar as a regional hub for investment banking services in the coming years.
Market Opportunities
- Expansion of Digital Banking Services:The digital banking sector in Qatar is projected to grow significantly, with investments in fintech expected to exceed $700 million in future. This presents a substantial opportunity for investment banks to develop and offer innovative digital solutions, enhancing customer engagement and operational efficiency while meeting the evolving needs of tech-savvy clients.
- Development of Islamic Banking Products:The Islamic banking sector in Qatar is valued at approximately $250 billion, with a growing demand for Sharia-compliant financial products. Investment banks can leverage this opportunity by expanding their offerings in Islamic finance, catering to both local and international clients seeking ethical investment options, thus enhancing their market presence.
Scope of the Report
| Segment | Sub-Segments |
|---|---|
| By Service Type | Mergers and Acquisitions Advisory Debt Capital Markets Underwriting Equity Capital Markets Underwriting Financial Sponsor/Syndicated Loans |
| By End-User | Individuals Corporate Institutions |
| By Enterprise Size | Large Enterprises Small and Medium-Sized Enterprises (SMEs) |
| By Client Type | Retail Clients Corporate Clients Institutional Clients Government Clients Others |
| By Geographic Presence | Domestic Market GCC Region International Markets Others |
| By Investment Type | Equity Investments Debt Investments Real Estate Investments Alternative Investments Others |
| By Regulatory Framework | Conventional Banking Regulations Islamic Banking Regulations International Compliance Standards Others |
Key Target Audience
Investors and Venture Capitalist Firms
Government and Regulatory Bodies (e.g., Qatar Central Bank, Qatar Financial Markets Authority)
Private Equity Firms
Wealth Management Firms
Corporate Clients and Multinational Corporations
Real Estate Investment Trusts (REITs)
Family Offices
Insurance Companies
Players Mentioned in the Report:
Qatar National Bank
Doha Bank
Commercial Bank of Qatar
Qatar Islamic Bank
Masraf Al Rayan
Ahli Bank
Al Khalij Commercial Bank
Qatar First Bank
Investment Bank of Qatar
Barwa Bank
Al Rayan Investment
QInvest
Qatar Financial Centre
Qatar Development Bank
Gulf International Bank
Table of Contents
Market Assessment Phase
1. Executive Summary and Approach
2. Qatar Investment Banking Market Overview
2.1 Key Insights and Strategic Recommendations
2.2 Qatar Investment Banking Market Overview
2.3 Definition and Scope
2.4 Evolution of Market Ecosystem
2.5 Timeline of Key Regulatory Milestones
2.6 Value Chain & Stakeholder Mapping
2.7 Business Cycle Analysis
2.8 Policy & Incentive Landscape
3. Qatar Investment Banking Market Analysis
3.1 Growth Drivers
3.1.1 Increasing Foreign Direct Investment
3.1.2 Government Infrastructure Projects
3.1.3 Rising Demand for Financial Services
3.1.4 Technological Advancements in Banking
3.2 Market Challenges
3.2.1 Regulatory Compliance Costs
3.2.2 Competition from Regional Banks
3.2.3 Economic Fluctuations
3.2.4 Limited Market Awareness
3.3 Market Opportunities
3.3.1 Expansion of Digital Banking Services
3.3.2 Development of Islamic Banking Products
3.3.3 Strategic Partnerships with Fintechs
3.3.4 Growth in Wealth Management Services
3.4 Market Trends
3.4.1 Shift Towards Sustainable Investment
3.4.2 Increased Focus on Customer Experience
3.4.3 Adoption of AI and Machine Learning
3.4.4 Rise of Mobile Banking Solutions
3.5 Government Regulation
3.5.1 Central Bank Regulations on Capital Adequacy
3.5.2 Anti-Money Laundering Policies
3.5.3 Consumer Protection Laws
3.5.4 Licensing Requirements for New Entrants
4. SWOT Analysis
5. Stakeholder Analysis
6. Porter's Five Forces Analysis
7. Qatar Investment Banking Market Market Size, 2019-2024
7.1 By Value
7.2 By Volume
7.3 By Average Selling Price
8. Qatar Investment Banking Market Segmentation
8.1 By Service Type
8.1.1 Mergers and Acquisitions Advisory
8.1.2 Debt Capital Markets Underwriting
8.1.3 Equity Capital Markets Underwriting
8.1.4 Financial Sponsor/Syndicated Loans
8.2 By End-User
8.2.1 Individuals
8.2.2 Corporate Institutions
8.3 By Enterprise Size
8.3.1 Large Enterprises
8.3.2 Small and Medium-Sized Enterprises (SMEs)
8.4 By Client Type
8.4.1 Retail Clients
8.4.2 Corporate Clients
8.4.3 Institutional Clients
8.4.4 Government Clients
8.4.5 Others
8.5 By Geographic Presence
8.5.1 Domestic Market
8.5.2 GCC Region
8.5.3 International Markets
8.5.4 Others
8.6 By Investment Type
8.6.1 Equity Investments
8.6.2 Debt Investments
8.6.3 Real Estate Investments
8.6.4 Alternative Investments
8.6.5 Others
8.7 By Regulatory Framework
8.7.1 Conventional Banking Regulations
8.7.2 Islamic Banking Regulations
8.7.3 International Compliance Standards
8.7.4 Others
9. Qatar Investment Banking Market Competitive Analysis
9.1 Market Share of Key Players
9.2 Cross Comparison of Key Players
9.2.1 Company Name
9.2.2 Revenue (USD Million)
9.2.3 Revenue Growth Rate (CAGR %)
9.2.4 Market Share (%)
9.2.5 Total Assets (USD Billion)
9.2.6 Number of Transactions Completed
9.2.7 Average Deal Size (USD Million)
9.2.8 Client Retention Rate (%)
9.2.9 Return on Assets (ROA %)
9.2.10 Non-Performing Loan Ratio (%)
9.3 SWOT Analysis of Top Players
9.4 Pricing Analysis
9.5 Detailed Profile of Major Companies
9.5.1 Qatar National Bank
9.5.2 Doha Bank
9.5.3 Commercial Bank of Qatar
9.5.4 Qatar Islamic Bank
9.5.5 Masraf Al Rayan
9.5.6 Ahli Bank
9.5.7 Al Khalij Commercial Bank
9.5.8 Qatar First Bank
9.5.9 Investment Bank of Qatar
9.5.10 Barwa Bank
9.5.11 Al Rayan Investment
9.5.12 QInvest
9.5.13 Qatar Financial Centre
9.5.14 Qatar Development Bank
9.5.15 Gulf International Bank
10. Qatar Investment Banking Market End-User Analysis
10.1 Procurement Behavior of Key Ministries
10.1.1 Ministry of Finance
10.1.2 Ministry of Economy and Commerce
10.1.3 Ministry of Energy and Industry
10.1.4 Ministry of Transport and Communications
10.2 Corporate Spend on Infrastructure & Energy
10.2.1 Major Infrastructure Projects
10.2.2 Energy Sector Investments
10.2.3 Public-Private Partnerships
10.2.4 Corporate Social Responsibility Initiatives
10.3 Pain Point Analysis by End-User Category
10.3.1 Corporates
10.3.2 High Net-Worth Individuals
10.3.3 Institutional Investors
10.3.4 Government Entities
10.4 User Readiness for Adoption
10.4.1 Awareness of Financial Products
10.4.2 Digital Literacy Levels
10.4.3 Trust in Financial Institutions
10.4.4 Regulatory Compliance Understanding
10.5 Post-Deployment ROI and Use Case Expansion
10.5.1 Performance Metrics
10.5.2 Customer Feedback Mechanisms
10.5.3 Scalability of Financial Solutions
10.5.4 Future Investment Plans
11. Qatar Investment Banking Market Future Size, 2025-2030
11.1 By Value
11.2 By Volume
11.3 By Average Selling Price
Go-To-Market Strategy Phase
1. Whitespace Analysis + Business Model Canvas
1.1 Market Gaps Identification
1.2 Value Proposition Development
1.3 Revenue Streams Analysis
1.4 Cost Structure Evaluation
1.5 Key Partnerships Exploration
1.6 Customer Segmentation
1.7 Channels of Distribution
2. Marketing and Positioning Recommendations
2.1 Branding Strategies
2.2 Product USPs
2.3 Target Market Identification
2.4 Communication Strategies
2.5 Digital Marketing Approaches
2.6 Customer Engagement Tactics
2.7 Performance Metrics
3. Distribution Plan
3.1 Urban Retail Strategies
3.2 Rural NGO Tie-Ups
3.3 Online Distribution Channels
3.4 Direct Sales Approaches
3.5 Partnership Opportunities
3.6 Logistics and Supply Chain Management
3.7 Performance Evaluation
4. Channel & Pricing Gaps
4.1 Underserved Routes
4.2 Pricing Bands Analysis
4.3 Competitor Pricing Strategies
4.4 Customer Willingness to Pay
4.5 Value-Based Pricing Models
4.6 Dynamic Pricing Opportunities
4.7 Pricing Strategy Recommendations
5. Unmet Demand & Latent Needs
5.1 Category Gaps
5.2 Consumer Segments Analysis
5.3 Emerging Trends Identification
5.4 Customer Feedback Insights
5.5 Market Research Findings
5.6 Future Demand Projections
5.7 Strategic Recommendations
6. Customer Relationship
6.1 Loyalty Programs
6.2 After-Sales Service
6.3 Customer Support Strategies
6.4 Feedback Mechanisms
6.5 Relationship Management Tools
6.6 Customer Retention Strategies
6.7 Performance Metrics
7. Value Proposition
7.1 Sustainability Initiatives
7.2 Integrated Supply Chains
7.3 Unique Selling Points
7.4 Customer-Centric Approaches
7.5 Competitive Advantages
7.6 Market Differentiation Strategies
7.7 Performance Metrics
8. Key Activities
8.1 Regulatory Compliance
8.2 Branding Initiatives
8.3 Distribution Setup
8.4 Marketing Campaigns
8.5 Training and Development
8.6 Performance Monitoring
8.7 Strategic Partnerships
9. Entry Strategy Evaluation
9.1 Domestic Market Entry Strategy
9.1.1 Product Mix
9.1.2 Pricing Band
9.1.3 Packaging
9.2 Export Entry Strategy
9.2.1 Target Countries
9.2.2 Compliance Roadmap
10. Entry Mode Assessment
10.1 Joint Ventures
10.2 Greenfield Investments
10.3 Mergers & Acquisitions
10.4 Distributor Model
10.5 Risk Assessment
10.6 Strategic Fit Evaluation
10.7 Performance Metrics
11. Capital and Timeline Estimation
11.1 Capital Requirements
11.2 Timelines
11.3 Funding Sources
11.4 Financial Projections
11.5 Risk Management Strategies
11.6 Performance Metrics
12. Control vs Risk Trade-Off
12.1 Ownership vs Partnerships
12.2 Risk Mitigation Strategies
12.3 Control Mechanisms
12.4 Performance Metrics
13. Profitability Outlook
13.1 Breakeven Analysis
13.2 Long-Term Sustainability
13.3 Financial Health Indicators
13.4 Market Positioning
13.5 Performance Metrics
14. Potential Partner List
14.1 Distributors
14.2 Joint Ventures
14.3 Acquisition Targets
14.4 Strategic Alliances
14.5 Performance Metrics
15. Execution Roadmap
15.1 Phased Plan for Market Entry
15.1.1 Market Setup
15.1.2 Market Entry
15.1.3 Growth Acceleration
15.1.4 Scale & Stabilize
15.2 Key Activities and Milestones
15.2.1 Activity Planning
15.2.2 Milestone Tracking
15.2.3 Performance Evaluation
Research Methodology
Phase 1: Approach1
Desk Research
- Analysis of financial reports from major Qatari investment banks and financial institutions
- Review of market studies and white papers published by local financial regulatory bodies
- Examination of economic indicators and investment trends from the Qatar Central Bank
Primary Research
- Interviews with senior executives from leading investment banks in Qatar
- Surveys targeting financial analysts and investment advisors within the region
- Focus groups with institutional investors and private equity firms operating in Qatar
Validation & Triangulation
- Cross-validation of findings through multiple data sources including government reports and industry publications
- Triangulation of qualitative insights from interviews with quantitative data from market reports
- Sanity checks conducted through expert panels comprising seasoned investment professionals
Phase 2: Market Size Estimation1
Top-down Assessment
- Estimation of total assets under management (AUM) in the Qatari investment banking sector
- Analysis of investment flows into various sectors such as real estate, energy, and technology
- Incorporation of macroeconomic factors influencing investment trends in Qatar
Bottom-up Modeling
- Collection of data on transaction volumes and fees from major investment banking deals
- Estimation of revenue streams based on service offerings such as M&A advisory and capital raising
- Analysis of client demographics and their investment preferences to refine revenue projections
Forecasting & Scenario Analysis
- Multi-variable forecasting models incorporating GDP growth, oil prices, and foreign investment trends
- Scenario analysis based on potential regulatory changes and geopolitical factors affecting investment
- Development of baseline, optimistic, and pessimistic forecasts through 2028
Phase 3: CATI Sample Composition1
| Scope Item/Segment | Sample Size | Target Respondent Profiles |
|---|---|---|
| Corporate Investment Strategies | 120 | Chief Financial Officers, Investment Managers |
| Private Equity Trends | 100 | Private Equity Partners, Fund Managers |
| Wealth Management Services | 90 | Wealth Advisors, Client Relationship Managers |
| Real Estate Investment Insights | 70 | Real Estate Analysts, Portfolio Managers |
| Regulatory Impact on Investment Banking | 60 | Compliance Officers, Legal Advisors |
Frequently Asked Questions
What is the current value of the Qatar Investment Banking Market?
The Qatar Investment Banking Market is valued at approximately USD 200 million, reflecting a five-year historical analysis. This growth is driven by increased demand for financial advisory services, particularly in mergers and acquisitions, and the expansion of capital markets.
Which city dominates the Qatar Investment Banking Market?
What regulatory framework governs investment banking in Qatar?
What are the primary service types in the Qatar Investment Banking Market?
Other Regional/Country Reports
Other Adjacent Reports
Philippines Commercial Banking Market
Brazil Islamic Banking Market
India Wealth Management Market Size, Share & Forecast, By Product Type, Customer Segment & Distribution Channel, 2025-2032Kuwait Capital Markets Market
South Korea Financial Advisory Market
USA Private Equity Market Size, Share & Forecast, By Investment Strategy, Investor Segment & Fund Size, 2026-2031Mexico Venture Capital Market
Comoros Fintech MarketQatar Project Finance Market
Canada Asset Management Market Size, Share & Forecast, By Product Type, Customer Segment & Distribution Channel, 2025–2032Why Buy From Us?

What makes us stand out is that our consultants follow Robust, Refine and Result (RRR) methodology. Robust for clear definitions, approaches and sanity checking, Refine for differentiating respondents' facts and opinions, and Result for presenting data with story.

We have set a benchmark in the industry by offering our clients with syndicated and customized market research reports featuring coverage of entire market as well as meticulous research and analyst insights.

While we don't replace traditional research, we flip the method upside down. Our dual approach of Top Bottom & Bottom Top ensures quality deliverable by not just verifying company fundamentals but also looking at the sector and macroeconomic factors.

With one step in the future, our research team constantly tries to show you the bigger picture. We help with some of the tough questions you may encounter along the way: How is the industry positioned? Best marketing channel? KPI's of competitors? By aligning every element, we help maximize success.

Our report gives you instant access to the answers and sources that other companies might choose to hide. We elaborate each steps of research methodology we have used and showcase you the sample size to earn your trust.

If you need any support, we are here! We pride ourselves on universe strength, data quality, and quick, friendly, and professional service.