About the Report
Base Year 2024Qatar Automotive Telematics Market Overview
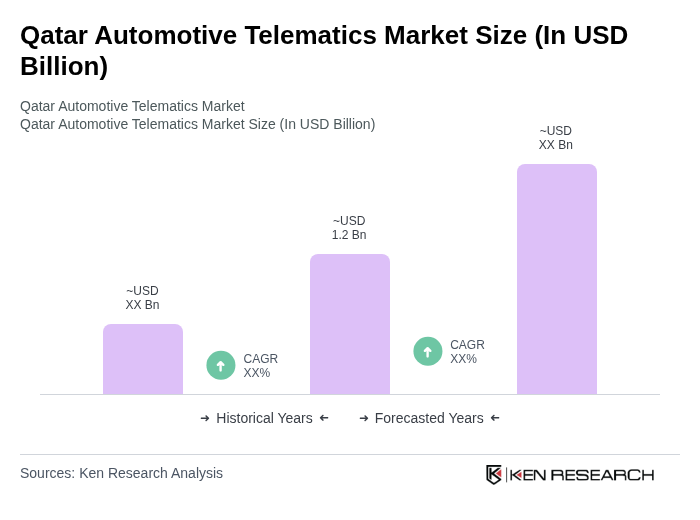
- The Qatar Automotive Telematics Market is valued at USD 1.2 billion, based on a five-year historical analysis. This growth is primarily driven by the increasing adoption of connected vehicles, rapid expansion of automotive IoT solutions, and the rising demand for fleet management platforms among logistics, public transport, and corporate fleets. The integration of telematics in vehicles enhances operational efficiency, supports predictive maintenance, improves driver behavior monitoring, and strengthens road safety, making it a crucial component for both consumers and businesses.
- Doha is the dominant city in the Qatar Automotive Telematics Market due to its rapid urbanization, concentration of vehicle ownership, and significant investments in smart mobility and intelligent transport systems as part of national digital transformation initiatives. Additionally, Al Rayyan and Al Wakrah are emerging as key centers, benefiting from their proximity to Doha, ongoing urban and infrastructure development, and growing deployment of telematics solutions in public transport, logistics, and commercial fleets.
- The Qatari government has progressively strengthened regulatory and policy support for connected and safer transportation, including requirements for tracking and monitoring of commercial and public transport fleets to improve road safety and traffic management. A key instrument is the Traffic Law issued under Law No. 19 of 2007 by the Ministry of Interior, which empowers authorities to implement systems for monitoring vehicle movements, enforce speed and safety compliance, and use electronic means for traffic control, forming the legal basis for telematics-enabled tracking and control in commercial and public service vehicles.
Qatar Automotive Telematics Market Segmentation
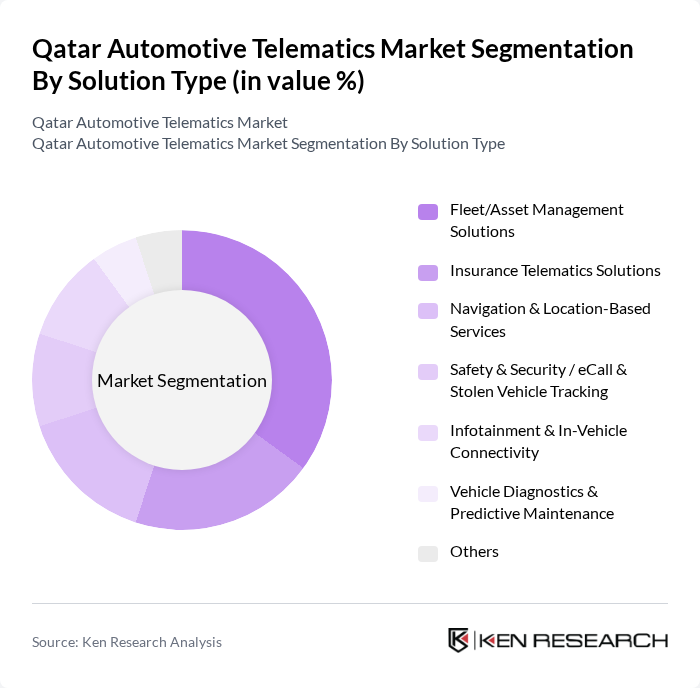
By Solution Type:The solution type segmentation includes various subsegments such as Fleet/Asset Management Solutions, Insurance Telematics Solutions, Navigation & Location-Based Services, Safety & Security / eCall & Stolen Vehicle Tracking, Infotainment & In-Vehicle Connectivity, Vehicle Diagnostics & Predictive Maintenance, and Others. Fleet/Asset Management Solutions dominate the market due to the increasing need for efficient fleet operations, route optimization, fuel and maintenance cost reduction, and compliance with safety and tracking requirements for commercial and government fleets. Businesses are increasingly adopting these solutions to monitor vehicle performance in real time, optimize routes, enhance driver safety and behavior monitoring, and enable data-driven decision-making for logistics and transport operations, leading to significant market growth.
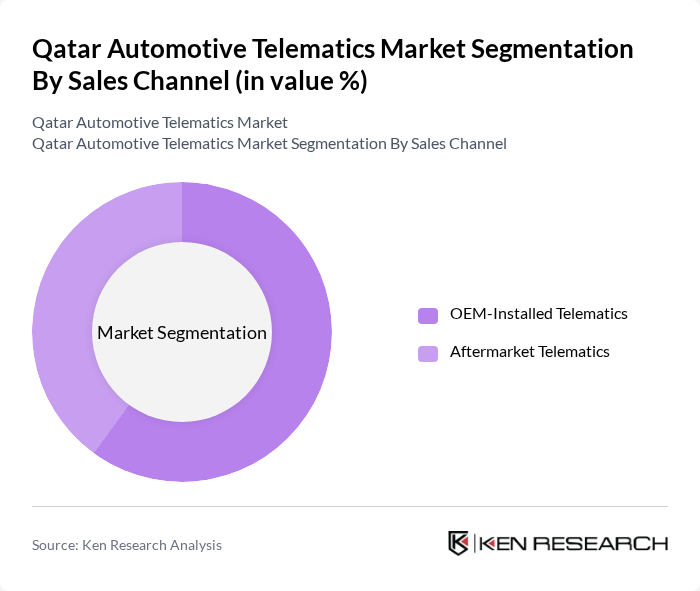
By Sales Channel:The sales channel segmentation includes OEM-Installed Telematics and Aftermarket Telematics. OEM-Installed Telematics is the leading subsegment, as automotive manufacturers increasingly integrate embedded connectivity, navigation, safety, and diagnostics capabilities into new vehicles in line with global connected-car trends and rising customer expectations. This trend is driven by consumer demand for advanced safety features, infotainment, and seamless smartphone integration, as well as fleet operators’ preference for factory-fitted connectivity modules that support warranty, compliance, and lifecycle management, making it a preferred choice for both manufacturers and consumers.
Qatar Automotive Telematics Market Competitive Landscape
The Qatar Automotive Telematics Market is characterized by a dynamic mix of regional and international players. Leading participants such as Ooredoo Qatar Q.P.S.C., Vodafone Qatar P.Q.S.C., Qatar Mobility Innovations Center (QMIC), Mannai Corporation QPSC – Automotive & ICT Divisions, Gulf Warehousing Company Q.P.S.C. (GWC), Qatar Fuel (WOQOD) – Fleet & Logistics Operations, Mowasalat (Karwa) – Public Transport & Taxi Fleet, Qatar Rail – Rail & Feeder Transport Integration, Al Jaber Group – Transport & Heavy Equipment Division, Nakilat – Land Logistics & Support Fleets, Baladna – Distribution & Cold Chain Fleets, Karwa Technologies & Other Local Telematics Service Providers, Regional & Global Telematics OEMs Active in Qatar, Major Automotive OEMs with Connected Vehicle Offerings in Qatar, System Integrators & ICT Players Enabling Telematics Solutions contribute to innovation, geographic expansion, and service delivery in this space.
Qatar Automotive Telematics Market Industry Analysis
Growth Drivers
- Increasing Demand for Vehicle Safety and Security:The Qatar automotive telematics market is significantly driven by the rising demand for enhanced vehicle safety and security features. In future, the number of road traffic accidents in Qatar is projected to reach approximately 4,500 incidents, prompting consumers to seek advanced telematics solutions. The integration of real-time tracking and emergency response systems is expected to reduce accident rates by 20%, thereby increasing the adoption of telematics technologies among vehicle owners and fleet operators.
- Rising Adoption of Connected Vehicles:The shift towards connected vehicles is a major growth driver in Qatar's automotive telematics market. In future, it is estimated that over 70% of new vehicles sold in Qatar will be equipped with connected technologies. This trend is fueled by consumer preferences for features such as navigation, infotainment, and remote diagnostics, which enhance the overall driving experience. The increasing penetration of smartphones and mobile applications further supports this growth, as they facilitate seamless connectivity between vehicles and users.
- Government Initiatives for Smart Transportation:The Qatari government is actively promoting smart transportation initiatives, which significantly bolster the automotive telematics market. In future, the government plans to invest around USD 1.2 billion in smart city projects, including intelligent transportation systems. These initiatives aim to improve traffic management and reduce congestion, thereby creating a favorable environment for telematics solutions. The government's commitment to enhancing urban mobility is expected to drive the adoption of telematics technologies across various sectors.
Market Challenges
- High Initial Investment Costs:One of the primary challenges facing the Qatar automotive telematics market is the high initial investment required for telematics systems. The average cost of implementing a comprehensive telematics solution can exceed USD 1,800 per vehicle, which poses a barrier for small and medium-sized enterprises. This financial hurdle limits the widespread adoption of telematics technologies, particularly among fleet operators who may struggle to justify the upfront costs against potential long-term savings.
- Data Privacy and Security Concerns:Data privacy and security issues present significant challenges in the automotive telematics market. With the increasing amount of data generated by connected vehicles, concerns regarding data breaches and unauthorized access are on the rise. In future, it is anticipated that over 35% of consumers in Qatar will express apprehension about sharing their vehicle data. This skepticism can hinder the adoption of telematics solutions, as consumers prioritize their privacy and security over potential benefits.
Qatar Automotive Telematics Market Future Outlook
The future of the Qatar automotive telematics market appears promising, driven by technological advancements and increasing consumer awareness. As 5G networks expand, the potential for real-time data transmission will enhance telematics applications, making them more attractive to consumers. Additionally, the integration of artificial intelligence and machine learning will enable more sophisticated analytics, improving fleet management and vehicle safety. These trends indicate a robust growth trajectory for the market, with significant opportunities for innovation and collaboration among stakeholders.
Market Opportunities
- Expansion of 5G Networks:The rollout of 5G networks in Qatar presents a significant opportunity for the automotive telematics market. With faster data transmission speeds and lower latency, telematics solutions can offer real-time insights and enhance vehicle connectivity. This technological advancement is expected to attract more consumers and businesses to adopt telematics systems, ultimately driving market growth.
- Integration of AI and Machine Learning:The integration of artificial intelligence and machine learning into telematics applications offers substantial market opportunities. These technologies can analyze vast amounts of data to provide predictive maintenance, optimize fleet operations, and enhance driver safety. As businesses seek to improve efficiency and reduce costs, the demand for AI-driven telematics solutions is likely to increase, fostering innovation in the sector.
Scope of the Report
| Segment | Sub-Segments |
|---|---|
| By Solution Type | Fleet/Asset Management Solutions Insurance Telematics Solutions Navigation & Location-Based Services Safety & Security / eCall & Stolen Vehicle Tracking Infotainment & In-Vehicle Connectivity Vehicle Diagnostics & Predictive Maintenance Others |
| By Sales Channel | OEM-Installed Telematics Aftermarket Telematics |
| By Vehicle Type | Passenger Cars Light Commercial Vehicles (LCVs) Heavy Commercial Vehicles & Buses Specialized & Off-Highway Vehicles Electric Vehicles |
| By Connectivity & Technology | Embedded Telematics Tethered / Smartphone-Integrated Telematics Integrated / Hybrid Telematics GPS & GNSS Tracking Cellular (3G/4G/5G) Communication Satellite Communication Others |
| By Service Model | Subscription-Based (Recurring SaaS) One-Time License / Perpetual Managed Services Professional & Consulting Services Hardware Provisioning & Installation Services Others |
| By End-User | Logistics & Road Freight Companies Public Transport & Bus Operators Corporate & Leasing Fleets Government & Municipal Fleets Utilities, Oil & Gas, and Construction Fleets Individual Vehicle Owners Others |
| By Region | Doha Al Rayyan Al Wakrah Others |
Key Target Audience
Investors and Venture Capitalist Firms
Government and Regulatory Bodies (e.g., Ministry of Transport and Communications, Qatar National Research Fund)
Automotive Manufacturers
Telematics Solution Providers
Fleet Management Companies
Insurance Companies
Telecommunications Providers
Automotive Aftermarket Service Providers
Players Mentioned in the Report:
Ooredoo Qatar Q.P.S.C.
Vodafone Qatar P.Q.S.C.
Qatar Mobility Innovations Center (QMIC)
Mannai Corporation QPSC Automotive & ICT Divisions
Gulf Warehousing Company Q.P.S.C. (GWC)
Qatar Fuel (WOQOD) Fleet & Logistics Operations
Mowasalat (Karwa) Public Transport & Taxi Fleet
Qatar Rail Rail & Feeder Transport Integration
Al Jaber Group Transport & Heavy Equipment Division
Nakilat Land Logistics & Support Fleets
Baladna Distribution & Cold Chain Fleets
Karwa Technologies & Other Local Telematics Service Providers
Regional & Global Telematics OEMs Active in Qatar
Major Automotive OEMs with Connected Vehicle Offerings in Qatar
System Integrators & ICT Players Enabling Telematics Solutions
Table of Contents
Market Assessment Phase
1. Executive Summary and Approach
2. Qatar Automotive Telematics Market Overview
2.1 Key Insights and Strategic Recommendations
2.2 Qatar Automotive Telematics Market Overview
2.3 Definition and Scope
2.4 Evolution of Market Ecosystem
2.5 Timeline of Key Regulatory Milestones
2.6 Value Chain & Stakeholder Mapping
2.7 Business Cycle Analysis
2.8 Policy & Incentive Landscape
3. Qatar Automotive Telematics Market Analysis
3.1 Growth Drivers
3.1.1 Increasing demand for vehicle safety and security
3.1.2 Rising adoption of connected vehicles
3.1.3 Government initiatives for smart transportation
3.1.4 Growth in fleet management solutions
3.2 Market Challenges
3.2.1 High initial investment costs
3.2.2 Data privacy and security concerns
3.2.3 Lack of standardization in telematics solutions
3.2.4 Limited awareness among consumers
3.3 Market Opportunities
3.3.1 Expansion of 5G networks
3.3.2 Integration of AI and machine learning
3.3.3 Development of new telematics applications
3.3.4 Partnerships with automotive manufacturers
3.4 Market Trends
3.4.1 Shift towards subscription-based models
3.4.2 Increasing focus on sustainability
3.4.3 Growth of usage-based insurance
3.4.4 Enhanced user experience through mobile applications
3.5 Government Regulation
3.5.1 Implementation of vehicle tracking regulations
3.5.2 Standards for data sharing and privacy
3.5.3 Incentives for telematics adoption
3.5.4 Regulations on emissions and fuel efficiency
4. SWOT Analysis
5. Stakeholder Analysis
6. Porter's Five Forces Analysis
7. Qatar Automotive Telematics Market Market Size, 2019-2024
7.1 By Value
7.2 By Volume
7.3 By Average Selling Price
8. Qatar Automotive Telematics Market Segmentation
8.1 By Solution Type
8.1.1 Fleet/Asset Management Solutions
8.1.2 Insurance Telematics Solutions
8.1.3 Navigation & Location-Based Services
8.1.4 Safety & Security / eCall & Stolen Vehicle Tracking
8.1.5 Infotainment & In-Vehicle Connectivity
8.1.6 Vehicle Diagnostics & Predictive Maintenance
8.1.7 Others
8.2 By Sales Channel
8.2.1 OEM-Installed Telematics
8.2.2 Aftermarket Telematics
8.3 By Vehicle Type
8.3.1 Passenger Cars
8.3.2 Light Commercial Vehicles (LCVs)
8.3.3 Heavy Commercial Vehicles & Buses
8.3.4 Specialized & Off-Highway Vehicles
8.3.5 Electric Vehicles
8.4 By Connectivity & Technology
8.4.1 Embedded Telematics
8.4.2 Tethered / Smartphone-Integrated Telematics
8.4.3 Integrated / Hybrid Telematics
8.4.4 GPS & GNSS Tracking
8.4.5 Cellular (3G/4G/5G) Communication
8.4.6 Satellite Communication
8.4.7 Others
8.5 By Service Model
8.5.1 Subscription-Based (Recurring SaaS)
8.5.2 One-Time License / Perpetual
8.5.3 Managed Services
8.5.4 Professional & Consulting Services
8.5.5 Hardware Provisioning & Installation Services
8.5.6 Others
8.6 By End-User
8.6.1 Logistics & Road Freight Companies
8.6.2 Public Transport & Bus Operators
8.6.3 Corporate & Leasing Fleets
8.6.4 Government & Municipal Fleets
8.6.5 Utilities, Oil & Gas, and Construction Fleets
8.6.6 Individual Vehicle Owners
8.6.7 Others
8.7 By Region
8.7.1 Doha
8.7.2 Al Rayyan
8.7.3 Al Wakrah
8.7.4 Others
9. Qatar Automotive Telematics Market Competitive Analysis
9.1 Market Share of Key Players
9.2 Cross Comparison of Key Players
9.2.1 Company Name
9.2.2 Group Size (Large, Medium, or Small as per industry convention)
9.2.3 Qatar Telematics Revenue (USD/QAR)
9.2.4 Revenue Growth Rate (3-Year CAGR)
9.2.5 Telematics Subscriber / Connected Vehicle Base
9.2.6 Average Revenue per User (ARPU)
9.2.7 Telematics EBITDA Margin
9.2.8 Share of Recurring / Subscription Revenue
9.2.9 Customer Acquisition Cost
9.2.10 Customer Retention / Churn Rate
9.2.11 Market Share in Qatar Automotive Telematics
9.2.12 Average Contract Tenure
9.2.13 R&D Spend on Connected Vehicle & Telematics (% of Revenue)
9.2.14 Strategic Partnerships / OEM Integrations Count
9.3 SWOT Analysis of Top Players
9.4 Pricing Analysis
9.5 Detailed Profile of Major Companies
9.5.1 Ooredoo Qatar Q.P.S.C.
9.5.2 Vodafone Qatar P.Q.S.C.
9.5.3 Qatar Mobility Innovations Center (QMIC)
9.5.4 Mannai Corporation QPSC – Automotive & ICT Divisions
9.5.5 Gulf Warehousing Company Q.P.S.C. (GWC)
9.5.6 Qatar Fuel (WOQOD) – Fleet & Logistics Operations
9.5.7 Mowasalat (Karwa) – Public Transport & Taxi Fleet
9.5.8 Qatar Rail – Rail & Feeder Transport Integration
9.5.9 Al Jaber Group – Transport & Heavy Equipment Division
9.5.10 Nakilat – Land Logistics & Support Fleets
9.5.11 Baladna – Distribution & Cold Chain Fleets
9.5.12 Karwa Technologies & Other Local Telematics Service Providers
9.5.13 Regional & Global Telematics OEMs Active in Qatar
9.5.14 Major Automotive OEMs with Connected Vehicle Offerings in Qatar
9.5.15 System Integrators & ICT Players Enabling Telematics Solutions
10. Qatar Automotive Telematics Market End-User Analysis
10.1 Procurement Behavior of Key Ministries
10.1.1 Ministry of Transport and Communications
10.1.2 Ministry of Interior
10.1.3 Ministry of Municipality and Environment
10.1.4 Ministry of Education and Higher Education
10.2 Corporate Spend on Infrastructure & Energy
10.2.1 Investment in Smart City Initiatives
10.2.2 Budget Allocation for Transportation Projects
10.2.3 Funding for Research and Development
10.2.4 Expenditure on Telematics Solutions
10.3 Pain Point Analysis by End-User Category
10.3.1 Fleet Managers
10.3.2 Individual Vehicle Owners
10.3.3 Government Agencies
10.3.4 Logistics Companies
10.4 User Readiness for Adoption
10.4.1 Awareness of Telematics Benefits
10.4.2 Availability of Infrastructure
10.4.3 Training and Support Needs
10.4.4 Financial Readiness
10.5 Post-Deployment ROI and Use Case Expansion
10.5.1 Measurement of Cost Savings
10.5.2 User Feedback and Improvement
10.5.3 Expansion into New Use Cases
10.5.4 Long-term Value Assessment
11. Qatar Automotive Telematics Market Future Size, 2025-2030
11.1 By Value
11.2 By Volume
11.3 By Average Selling Price
Go-To-Market Strategy Phase
1. Whitespace Analysis + Business Model Canvas
1.1 Market Gaps Identification
1.2 Value Proposition Development
1.3 Revenue Streams Analysis
1.4 Cost Structure Evaluation
1.5 Key Partnerships Exploration
1.6 Customer Segmentation
1.7 Channels and Customer Relationships
2. Marketing and Positioning Recommendations
2.1 Branding Strategies
2.2 Product USPs
2.3 Target Market Identification
2.4 Communication Strategy
2.5 Digital Marketing Approaches
2.6 Customer Engagement Tactics
2.7 Performance Metrics
3. Distribution Plan
3.1 Urban Retail Strategies
3.2 Rural NGO Tie-ups
3.3 Online Distribution Channels
3.4 Partnerships with Local Dealers
3.5 Logistics and Supply Chain Management
3.6 Inventory Management
3.7 Customer Service Framework
4. Channel & Pricing Gaps
4.1 Underserved Routes
4.2 Pricing Bands Analysis
4.3 Competitor Pricing Strategies
4.4 Customer Willingness to Pay
4.5 Discount and Promotion Strategies
4.6 Price Sensitivity Assessment
4.7 Value-Based Pricing Models
5. Unmet Demand & Latent Needs
5.1 Category Gaps Identification
5.2 Consumer Segments Analysis
5.3 Emerging Trends and Preferences
5.4 Product Development Opportunities
5.5 Market Entry Barriers
5.6 Customer Feedback Mechanisms
5.7 Future Demand Projections
6. Customer Relationship
6.1 Loyalty Programs
6.2 After-sales Service
6.3 Customer Feedback Loops
6.4 Community Engagement Initiatives
6.5 Customer Education and Training
6.6 Relationship Management Tools
6.7 Performance Tracking
7. Value Proposition
7.1 Sustainability Initiatives
7.2 Integrated Supply Chains
7.3 Unique Selling Points
7.4 Customer-Centric Innovations
7.5 Competitive Advantages
7.6 Market Differentiation Strategies
7.7 Long-term Value Creation
8. Key Activities
8.1 Regulatory Compliance
8.2 Branding Initiatives
8.3 Distribution Setup
8.4 Training and Development
8.5 Market Research and Analysis
8.6 Performance Monitoring
8.7 Stakeholder Engagement
9. Entry Strategy Evaluation
9.1 Domestic Market Entry Strategy
9.1.1 Product Mix
9.1.2 Pricing Band
9.1.3 Packaging
9.2 Export Entry Strategy
9.2.1 Target Countries
9.2.2 Compliance Roadmap
10. Entry Mode Assessment
10.1 Joint Ventures
10.2 Greenfield Investments
10.3 Mergers and Acquisitions
10.4 Distributor Model
10.5 Risk Assessment
10.6 Strategic Fit Evaluation
10.7 Long-term Partnership Opportunities
11. Capital and Timeline Estimation
11.1 Capital Requirements
11.2 Timelines for Implementation
11.3 Financial Projections
11.4 Funding Sources
11.5 Budget Allocation
11.6 Cost-Benefit Analysis
11.7 Risk Mitigation Strategies
12. Control vs Risk Trade-Off
12.1 Ownership vs Partnerships
12.2 Risk Management Framework
12.3 Control Mechanisms
12.4 Partnership Evaluation Criteria
12.5 Long-term Strategic Goals
12.6 Performance Metrics
12.7 Exit Strategies
13. Profitability Outlook
13.1 Breakeven Analysis
13.2 Long-term Sustainability
13.3 Profit Margin Projections
13.4 Revenue Growth Strategies
13.5 Cost Management Techniques
13.6 Financial Health Indicators
13.7 Market Positioning for Profitability
14. Potential Partner List
14.1 Distributors
14.2 Joint Ventures
14.3 Acquisition Targets
14.4 Strategic Alliances
14.5 Local Partnerships
14.6 International Collaborations
14.7 Industry Associations
15. Execution Roadmap
15.1 Phased Plan for Market Entry
15.1.1 Market Setup
15.1.2 Market Entry
15.1.3 Growth Acceleration
15.1.4 Scale & Stabilize
15.2 Key Activities and Milestones
15.2.1 Initial Launch Activities
15.2.2 Performance Review Points
15.2.3 Expansion Activities
15.2.4 Long-term Growth Strategies
Research Methodology
Phase 1: Approach1
Desk Research
- Industry reports from automotive telematics associations and market research firms
- Government publications on transportation and telematics regulations in Qatar
- Academic journals and white papers focusing on telematics technology and applications
Primary Research
- Interviews with telematics solution providers and automotive manufacturers in Qatar
- Surveys targeting fleet managers and logistics companies utilizing telematics
- Field interviews with automotive industry experts and technology consultants
Validation & Triangulation
- Cross-validation of data from multiple sources including industry reports and expert interviews
- Triangulation of market trends through sales data and regulatory insights
- Sanity checks conducted through expert panel reviews and feedback sessions
Phase 2: Market Size Estimation1
Top-down Assessment
- Analysis of national automotive sales data to estimate telematics adoption rates
- Segmentation of the market by vehicle type and telematics application
- Incorporation of government initiatives promoting smart transportation solutions
Bottom-up Modeling
- Data collection from telematics service providers on subscription and usage rates
- Estimation of market size based on fleet sizes and telematics penetration rates
- Cost analysis of telematics solutions and their impact on operational efficiency
Forecasting & Scenario Analysis
- Multi-variable regression analysis incorporating economic indicators and technology trends
- Scenario modeling based on potential regulatory changes and market disruptions
- Development of baseline, optimistic, and pessimistic forecasts through 2030
Phase 3: CATI Sample Composition1
| Scope Item/Segment | Sample Size | Target Respondent Profiles |
|---|---|---|
| Commercial Fleet Management | 100 | Fleet Managers, Operations Directors |
| Passenger Vehicle Telematics | 80 | Automotive Manufacturers, Product Managers |
| Logistics and Supply Chain Telematics | 90 | Logistics Coordinators, Supply Chain Analysts |
| Telematics Software Development | 70 | Software Engineers, Product Development Leads |
| Government Transportation Initiatives | 60 | Policy Makers, Transportation Planners |
Frequently Asked Questions
What is the current value of the Qatar Automotive Telematics Market?
The Qatar Automotive Telematics Market is valued at approximately USD 1.2 billion, reflecting significant growth driven by the adoption of connected vehicles and the demand for fleet management solutions across various sectors.
What factors are driving the growth of the automotive telematics market in Qatar?
Which city is the leading market for automotive telematics in Qatar?
What are the main types of solutions offered in the Qatar Automotive Telematics Market?
Other Regional/Country Reports
Other Adjacent Reports
Kuwait Connected Vehicles Market
Qatar Fleet Management Systems Market
Indonesia Automotive IoT Market Outlook to 2030Philippines Vehicle Safety Systems Market
Vietnam Navigation and Location Services Market
Vietnam In-Vehicle Infotainment Market
Singapore Predictive Maintenance Solutions Market
Singapore Intelligent Transportation Systems Market
Singapore Usage-Based Insurance Market
Kuwait Automotive Electronics (ECUs, Sensors, Controllers) Market Size, Share, Growth Drivers, Trends, Opportunities, Competitive Landscape & Forecast 2025–2030Why Buy From Us?

What makes us stand out is that our consultants follow Robust, Refine and Result (RRR) methodology. Robust for clear definitions, approaches and sanity checking, Refine for differentiating respondents' facts and opinions, and Result for presenting data with story.

We have set a benchmark in the industry by offering our clients with syndicated and customized market research reports featuring coverage of entire market as well as meticulous research and analyst insights.

While we don't replace traditional research, we flip the method upside down. Our dual approach of Top Bottom & Bottom Top ensures quality deliverable by not just verifying company fundamentals but also looking at the sector and macroeconomic factors.

With one step in the future, our research team constantly tries to show you the bigger picture. We help with some of the tough questions you may encounter along the way: How is the industry positioned? Best marketing channel? KPI's of competitors? By aligning every element, we help maximize success.

Our report gives you instant access to the answers and sources that other companies might choose to hide. We elaborate each steps of research methodology we have used and showcase you the sample size to earn your trust.

If you need any support, we are here! We pride ourselves on universe strength, data quality, and quick, friendly, and professional service.