About the Report
Base Year 2024Listen to the audio summary
United Arab Emirates Medical Imaging Market Overview
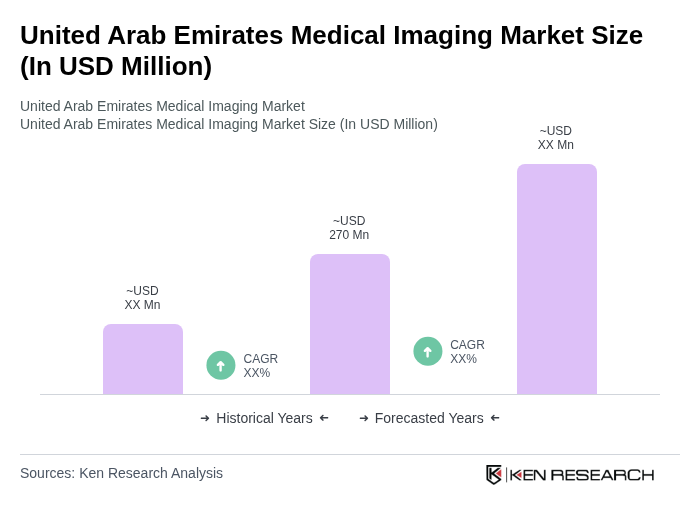
- The United Arab Emirates Medical Imaging Market is valued at USD 270 million, based on a five-year historical analysis. This growth is primarily driven by advancements in imaging technologies, increasing prevalence of chronic diseases such as cardiovascular diseases, cancer, and diabetes, and rising healthcare expenditure supported by mandatory health insurance coverage and sustained government investment in hospital and diagnostic infrastructure. The demand for diagnostic imaging services has surged due to the growing awareness of early disease detection, the expansion of screening programs, and the need for accurate, non?invasive diagnosis across both public and private healthcare providers.
- Key cities such as Dubai and Abu Dhabi dominate the market due to their advanced healthcare infrastructure, high population density, and a significant influx of medical tourists, positioning them as regional hubs for specialized and tertiary care. The presence of leading hospitals and diagnostic centers equipped with state-of-the-art MRI, CT, ultrasound, and hybrid imaging systems in these cities further enhances their market position, making them focal points for investment in AI-enabled imaging, teleradiology, and minimally invasive image?guided procedures in the region.
- The UAE’s medical imaging ecosystem operates within the broader national health policy and strategic frameworks, including the UAE Vision 2031 and emirate-level health strategies that emphasize digital health and advanced diagnostics; for example, the Dubai Health Authority has pursued structured AI validation and integration in radiology, such as through its Memorandum of Understanding with Agfa HealthCare to validate radiology AI algorithms for clinical use. In addition, regulatory oversight for medical imaging equipment and radiological practices is anchored in instruments such as the Federal Law No. 10 of 2008 on Medical Liability issued by the UAE Federal Government and the Cabinet Resolution No. 14 of 2019 on the Executive Regulations of this law, which set requirements for licensing of healthcare facilities, use of medical devices, adherence to clinical standards, and professional accountability in diagnostic procedures, including imaging.
United Arab Emirates Medical Imaging Market Segmentation
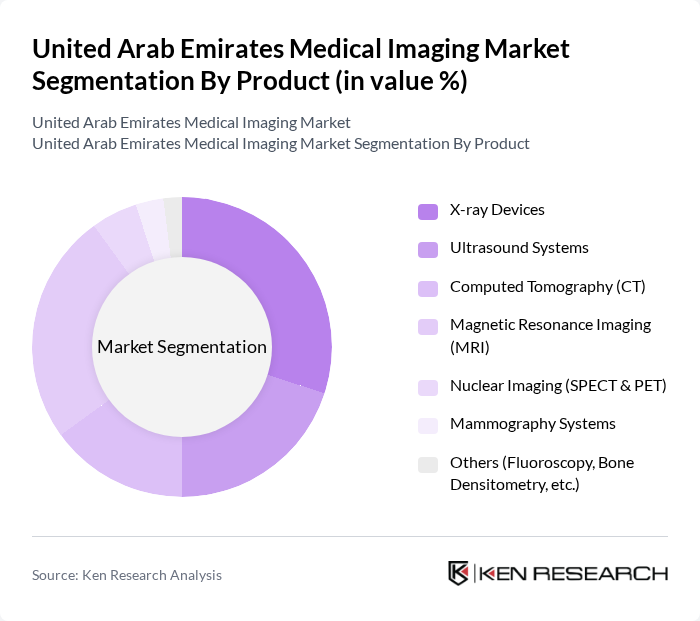
By Product:The product segmentation of the market includes various imaging modalities that cater to different diagnostic needs. The primary subsegments are X-ray Devices, Ultrasound Systems, Computed Tomography (CT), Magnetic Resonance Imaging (MRI), Nuclear Imaging (SPECT & PET), Mammography Systems, and Others (Fluoroscopy, Bone Densitometry, etc.). Among these, CT systems have recently emerged as a key revenue-contributing segment in the UAE, while X-ray Devices, Ultrasound Systems, and MRI systems continue to account for a substantial share of installed base and procedure volume due to their widespread application in hospitals and diagnostic centers for routine imaging, emergency care, oncology, cardiology, and musculoskeletal assessments.
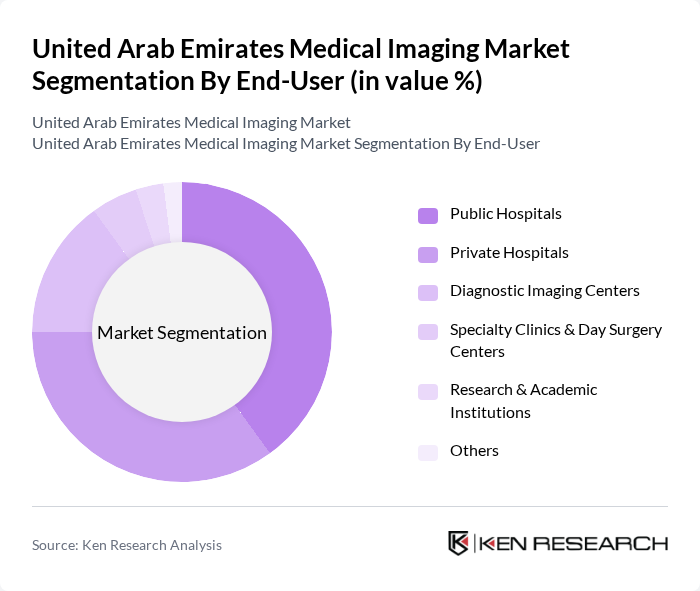
By End-User:The end-user segmentation includes Public Hospitals, Private Hospitals, Diagnostic Imaging Centers, Specialty Clinics & Day Surgery Centers, Research & Academic Institutions, and Others. Public and Private Hospitals dominate the market as they are the primary providers of medical imaging services, supported by large multidisciplinary facilities, comprehensive emergency and inpatient services, and continuous investment in high-end MRI, CT, and interventional radiology suites to cater to a large and complex patient base across cardiology, oncology, neurology, orthopedics, and women’s health. Diagnostic Imaging Centers and specialized clinics are gaining share, driven by outpatient demand, medical tourism, and the growth of teleradiology and subspecialty reporting services in major emirates.
United Arab Emirates Medical Imaging Market Competitive Landscape
The United Arab Emirates Medical Imaging Market is characterized by a dynamic mix of regional and international players. Leading participants such as Siemens Healthineers AG, GE HealthCare Technologies Inc., Koninklijke Philips N.V., Canon Medical Systems Corporation, Fujifilm Healthcare, Hitachi Ltd (Imaging & Diagnostics), Agfa HealthCare NV, Carestream Health Inc., Hologic Inc., Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Shimadzu Corporation, United Imaging Healthcare Co., Ltd., Samsung Medison Co., Ltd., Esaote S.p.A., Other Notable Regional Players (e.g., Local Distributors & OEM Partners) contribute to innovation, geographic expansion, and service delivery in this space.
United Arab Emirates Medical Imaging Market Industry Analysis
Growth Drivers
- Increasing Prevalence of Chronic Diseases:The United Arab Emirates (UAE) is witnessing a significant rise in chronic diseases, with diabetes affecting approximately 1.5 million individuals as of now. This growing health crisis necessitates advanced medical imaging for effective diagnosis and management. The World Health Organization reported that chronic diseases account for 70% of deaths in the UAE, driving demand for imaging services. Consequently, healthcare providers are investing in imaging technologies to enhance patient care and outcomes.
- Advancements in Imaging Technology:The UAE medical imaging sector is experiencing rapid technological advancements, with the introduction of high-resolution MRI and CT scanners. In future, the market saw a 20% increase in the adoption of digital imaging technologies, enhancing diagnostic accuracy. The integration of 3D imaging and real-time imaging capabilities is revolutionizing patient diagnostics, leading to improved treatment plans. This technological evolution is crucial for healthcare facilities aiming to provide cutting-edge services to their patients.
- Rising Healthcare Expenditure:The UAE government allocated approximately AED 70 billion (USD 19 billion) for healthcare in future, reflecting a commitment to improving health services. This increase in healthcare expenditure is fostering the growth of the medical imaging market, as hospitals and clinics upgrade their imaging equipment. The focus on enhancing healthcare infrastructure is expected to continue, with investments aimed at expanding access to advanced imaging technologies across the nation, ultimately benefiting patient care.
Market Challenges
- High Cost of Advanced Imaging Equipment:The financial burden associated with acquiring advanced imaging equipment poses a significant challenge for healthcare providers in the UAE. High-end MRI machines can cost upwards of AED 12 million (USD 3.3 million), making it difficult for smaller facilities to invest in such technologies. This financial barrier limits access to state-of-the-art imaging services, potentially impacting patient outcomes and the overall growth of the medical imaging market in the region.
- Shortage of Skilled Professionals:The UAE faces a critical shortage of skilled radiologists and imaging technicians, with an estimated deficit of 2,000 professionals as of now. This shortage hampers the effective utilization of advanced imaging technologies and can lead to longer wait times for patients. The lack of trained personnel also poses challenges in maintaining high standards of care, which is essential for the growth and sustainability of the medical imaging market in the UAE.
United Arab Emirates Medical Imaging Market Future Outlook
The future of the UAE medical imaging market appears promising, driven by ongoing technological advancements and increasing healthcare investments. The integration of artificial intelligence in imaging processes is expected to enhance diagnostic accuracy and efficiency. Additionally, the expansion of telemedicine services will facilitate remote consultations and imaging interpretations, improving access to care. As the healthcare landscape evolves, the focus on patient-centric services will likely shape the future direction of the medical imaging sector in the UAE.
Market Opportunities
- Expansion of Telemedicine Services:The rise of telemedicine in the UAE presents a significant opportunity for the medical imaging market. With the government promoting digital health initiatives, tele-radiology services are expected to grow, allowing remote access to imaging consultations. This shift can enhance patient access to specialized care, particularly in rural areas, ultimately driving demand for imaging services and improving healthcare delivery.
- Integration of AI in Imaging:The integration of artificial intelligence in medical imaging is poised to revolutionize diagnostics in the UAE. AI technologies can analyze imaging data more efficiently, reducing the time required for diagnosis. As healthcare providers increasingly adopt AI solutions, the demand for advanced imaging systems will rise, creating opportunities for innovation and improved patient outcomes in the medical imaging market.
Scope of the Report
| Segment | Sub-Segments |
|---|---|
| By Product | X-ray Devices Ultrasound Systems Computed Tomography (CT) Magnetic Resonance Imaging (MRI) Nuclear Imaging (SPECT & PET) Mammography Systems Others (Fluoroscopy, Bone Densitometry, etc.) |
| By End-User | Public Hospitals Private Hospitals Diagnostic Imaging Centers Specialty Clinics & Day Surgery Centers Research & Academic Institutions Others |
| By Application | Oncology Cardiology Neurology Orthopedics & Musculoskeletal Gastroenterology Obstetrics & Gynecology Others |
| By Technology | Digital Imaging Systems Analog/Conventional Systems Hybrid & Advanced Modalities (e.g., PET-CT, PET-MRI) AI-enabled & Cloud-based Imaging Solutions |
| By Region | Abu Dhabi Dubai Sharjah Ajman Ras Al Khaimah Fujairah Umm Al-Quwain |
| By Ownership / Facility Type | Government-owned Facilities Private Sector Facilities Public-Private Partnership (PPP) Facilities |
| By Procurement / Financing Model | Direct Capital Purchase Leasing & Managed Equipment Services Pay-per-use / Outcome-based Models Others |
Key Target Audience
Investors and Venture Capitalist Firms
Government and Regulatory Bodies (e.g., Ministry of Health and Prevention, Dubai Health Authority)
Medical Imaging Equipment Manufacturers
Healthcare Providers and Hospitals
Medical Imaging Service Providers
Health Insurance Companies
Medical Technology Startups
Pharmaceutical Companies
Players Mentioned in the Report:
Siemens Healthineers AG
GE HealthCare Technologies Inc.
Koninklijke Philips N.V.
Canon Medical Systems Corporation
Fujifilm Healthcare
Hitachi Ltd (Imaging & Diagnostics)
Agfa HealthCare NV
Carestream Health Inc.
Hologic Inc.
Shenzhen Mindray Bio-Medical Electronics Co., Ltd.
Shimadzu Corporation
United Imaging Healthcare Co., Ltd.
Samsung Medison Co., Ltd.
Esaote S.p.A.
Other Notable Regional Players (e.g., Local Distributors & OEM Partners)
Table of Contents
Market Assessment Phase
1. Executive Summary and Approach
2. United Arab Emirates Medical Imaging Market Overview
2.1 Key Insights and Strategic Recommendations
2.2 United Arab Emirates Medical Imaging Market Overview
2.3 Definition and Scope
2.4 Evolution of Market Ecosystem
2.5 Timeline of Key Regulatory Milestones
2.6 Value Chain & Stakeholder Mapping
2.7 Business Cycle Analysis
2.8 Policy & Incentive Landscape
3. United Arab Emirates Medical Imaging Market Analysis
3.1 Growth Drivers
3.1.1 Increasing prevalence of chronic diseases
3.1.2 Advancements in imaging technology
3.1.3 Rising healthcare expenditure
3.1.4 Growing demand for early diagnosis
3.2 Market Challenges
3.2.1 High cost of advanced imaging equipment
3.2.2 Shortage of skilled professionals
3.2.3 Regulatory hurdles
3.2.4 Data privacy concerns
3.3 Market Opportunities
3.3.1 Expansion of telemedicine services
3.3.2 Integration of AI in imaging
3.3.3 Increasing public-private partnerships
3.3.4 Growth in medical tourism
3.4 Market Trends
3.4.1 Shift towards portable imaging devices
3.4.2 Rise in demand for minimally invasive procedures
3.4.3 Adoption of cloud-based imaging solutions
3.4.4 Focus on patient-centric imaging services
3.5 Government Regulation
3.5.1 Licensing requirements for imaging facilities
3.5.2 Compliance with international imaging standards
3.5.3 Regulations on radiation safety
3.5.4 Guidelines for tele-radiology services
4. SWOT Analysis
5. Stakeholder Analysis
6. Porter's Five Forces Analysis
7. United Arab Emirates Medical Imaging Market Market Size, 2019-2024
7.1 By Value
7.2 By Volume
7.3 By Average Selling Price
8. United Arab Emirates Medical Imaging Market Segmentation
8.1 By Product
8.1.1 X-ray Devices
8.1.2 Ultrasound Systems
8.1.3 Computed Tomography (CT)
8.1.4 Magnetic Resonance Imaging (MRI)
8.1.5 Nuclear Imaging (SPECT & PET)
8.1.6 Mammography Systems
8.1.7 Others (Fluoroscopy, Bone Densitometry, etc.)
8.2 By End-User
8.2.1 Public Hospitals
8.2.2 Private Hospitals
8.2.3 Diagnostic Imaging Centers
8.2.4 Specialty Clinics & Day Surgery Centers
8.2.5 Research & Academic Institutions
8.2.6 Others
8.3 By Application
8.3.1 Oncology
8.3.2 Cardiology
8.3.3 Neurology
8.3.4 Orthopedics & Musculoskeletal
8.3.5 Gastroenterology
8.3.6 Obstetrics & Gynecology
8.3.7 Others
8.4 By Technology
8.4.1 Digital Imaging Systems
8.4.2 Analog/Conventional Systems
8.4.3 Hybrid & Advanced Modalities (e.g., PET-CT, PET-MRI)
8.4.4 AI-enabled & Cloud-based Imaging Solutions
8.5 By Region
8.5.1 Abu Dhabi
8.5.2 Dubai
8.5.3 Sharjah
8.5.4 Ajman
8.5.5 Ras Al Khaimah
8.5.6 Fujairah
8.5.7 Umm Al-Quwain
8.6 By Ownership / Facility Type
8.6.1 Government-owned Facilities
8.6.2 Private Sector Facilities
8.6.3 Public-Private Partnership (PPP) Facilities
8.7 By Procurement / Financing Model
8.7.1 Direct Capital Purchase
8.7.2 Leasing & Managed Equipment Services
8.7.3 Pay-per-use / Outcome-based Models
8.7.4 Others
9. United Arab Emirates Medical Imaging Market Competitive Analysis
9.1 Market Share of Key Players
9.2 Cross Comparison of Key Players
9.2.1 Company Name
9.2.2 UAE Medical Imaging Revenue (USD Million)
9.2.3 3-year Revenue CAGR in UAE (%)
9.2.4 Installed Base in UAE (Number of Systems)
9.2.5 New System Installations per Year in UAE
9.2.6 Market Share by Modality (% of CT/MRI/Ultrasound, etc.)
9.2.7 Average Selling Price Positioning vs Market (Premium / Mid / Value)
9.2.8 R&D and Innovation Intensity (% of Global Revenue Spent on R&D)
9.2.9 Service & Maintenance Coverage (UAE Sites Covered / Uptime %)
9.2.10 EBITDA Margin for Imaging Business (Global / Regional, %)
9.2.11 Order Backlog & Booking-to-Bill Ratio (Where Disclosed)
9.2.12 Key Reference Sites / Flagship Installations in UAE
9.3 SWOT Analysis of Top Players
9.4 Pricing Analysis
9.5 Detailed Profile of Major Companies
9.5.1 Siemens Healthineers AG
9.5.2 GE HealthCare Technologies Inc.
9.5.3 Koninklijke Philips N.V.
9.5.4 Canon Medical Systems Corporation
9.5.5 Fujifilm Healthcare
9.5.6 Hitachi Ltd (Imaging & Diagnostics)
9.5.7 Agfa HealthCare NV
9.5.8 Carestream Health Inc.
9.5.9 Hologic Inc.
9.5.10 Shenzhen Mindray Bio-Medical Electronics Co., Ltd.
9.5.11 Shimadzu Corporation
9.5.12 United Imaging Healthcare Co., Ltd.
9.5.13 Samsung Medison Co., Ltd.
9.5.14 Esaote S.p.A.
9.5.15 Other Notable Regional Players (e.g., Local Distributors & OEM Partners)
10. United Arab Emirates Medical Imaging Market End-User Analysis
10.1 Procurement Behavior of Key Ministries
10.1.1 Budget Allocation Trends
10.1.2 Decision-Making Processes
10.1.3 Preferred Suppliers
10.1.4 Contracting Practices
10.2 Corporate Spend on Infrastructure & Energy
10.2.1 Investment in Imaging Technology
10.2.2 Infrastructure Development Plans
10.2.3 Energy Efficiency Initiatives
10.2.4 Budgeting for Upgrades
10.3 Pain Point Analysis by End-User Category
10.3.1 Equipment Reliability Issues
10.3.2 Training and Support Needs
10.3.3 Integration Challenges
10.3.4 Cost Management Concerns
10.4 User Readiness for Adoption
10.4.1 Technology Acceptance Levels
10.4.2 Training Requirements
10.4.3 Infrastructure Readiness
10.4.4 User Feedback Mechanisms
10.5 Post-Deployment ROI and Use Case Expansion
10.5.1 Measurement of ROI
10.5.2 Case Studies of Successful Implementations
10.5.3 Future Use Case Opportunities
10.5.4 Feedback for Continuous Improvement
11. United Arab Emirates Medical Imaging Market Future Size, 2025-2030
11.1 By Value
11.2 By Volume
11.3 By Average Selling Price
Go-To-Market Strategy Phase
1. Whitespace Analysis + Business Model Canvas
1.1 Market Gaps Identification
1.2 Business Model Framework
2. Marketing and Positioning Recommendations
2.1 Branding Strategies
2.2 Product USPs
3. Distribution Plan
3.1 Urban Retail Strategies
3.2 Rural NGO Tie-ups
4. Channel & Pricing Gaps
4.1 Underserved Routes
4.2 Pricing Bands
5. Unmet Demand & Latent Needs
5.1 Category Gaps
5.2 Consumer Segments
6. Customer Relationship
6.1 Loyalty Programs
6.2 After-sales Service
7. Value Proposition
7.1 Sustainability Initiatives
7.2 Integrated Supply Chains
8. Key Activities
8.1 Regulatory Compliance
8.2 Branding Efforts
8.3 Distribution Setup
9. Entry Strategy Evaluation
9.1 Domestic Market Entry Strategy
9.1.1 Product Mix Considerations
9.1.2 Pricing Band Analysis
9.1.3 Packaging Strategies
9.2 Export Entry Strategy
9.2.1 Target Countries
9.2.2 Compliance Roadmap
10. Entry Mode Assessment
10.1 Joint Ventures
10.2 Greenfield Investments
10.3 Mergers & Acquisitions
10.4 Distributor Model
11. Capital and Timeline Estimation
11.1 Capital Requirements
11.2 Timelines for Implementation
12. Control vs Risk Trade-Off
12.1 Ownership Considerations
12.2 Partnerships Evaluation
13. Profitability Outlook
13.1 Breakeven Analysis
13.2 Long-term Sustainability
14. Potential Partner List
14.1 Distributors
14.2 Joint Ventures
14.3 Acquisition Targets
15. Execution Roadmap
15.1 Phased Plan for Market Entry
15.1.1 Market Setup
15.1.2 Market Entry
15.1.3 Growth Acceleration
15.1.4 Scale & Stabilize
15.2 Key Activities and Milestones
15.2.1 Milestone Planning
15.2.2 Activity Tracking
Research Methodology
Phase 1: Approach1
Desk Research
- Analysis of industry reports from healthcare organizations and medical imaging associations
- Review of government publications and healthcare expenditure reports from the UAE Ministry of Health
- Examination of market trends and forecasts from reputable market research databases
Primary Research
- Interviews with radiologists and imaging center managers to gather insights on current practices
- Surveys with healthcare administrators regarding budget allocations for medical imaging
- Field interviews with equipment suppliers and manufacturers to understand market dynamics
Validation & Triangulation
- Cross-validation of findings through multiple data sources, including trade publications and expert opinions
- Triangulation of quantitative data from surveys with qualitative insights from interviews
- Sanity checks through expert panel reviews comprising industry veterans and academic professionals
Phase 2: Market Size Estimation1
Top-down Assessment
- Estimation of the medical imaging market size based on national healthcare spending data
- Segmentation of the market by imaging modality (e.g., MRI, CT, ultrasound) and end-user facilities
- Incorporation of demographic trends and disease prevalence rates affecting imaging demand
Bottom-up Modeling
- Collection of data on the number of imaging machines installed across hospitals and clinics
- Operational cost analysis based on service pricing and reimbursement rates
- Volume estimates derived from patient throughput and imaging procedure frequency
Forecasting & Scenario Analysis
- Multi-factor regression analysis incorporating technological advancements and healthcare policy changes
- Scenario modeling based on potential shifts in healthcare funding and insurance coverage
- Baseline, optimistic, and pessimistic projections for market growth through 2030
Phase 3: CATI Sample Composition1
| Scope Item/Segment | Sample Size | Target Respondent Profiles |
|---|---|---|
| Hospital Imaging Departments | 120 | Radiology Heads, Imaging Technologists |
| Private Imaging Centers | 90 | Center Managers, Medical Directors |
| Healthcare Policy Makers | 60 | Health Economists, Policy Analysts |
| Medical Equipment Suppliers | 50 | Sales Managers, Product Specialists |
| Insurance Providers | 40 | Claims Analysts, Underwriters |
Frequently Asked Questions
What is the current value of the United Arab Emirates Medical Imaging Market?
The United Arab Emirates Medical Imaging Market is valued at approximately USD 270 million, reflecting a significant growth driven by advancements in imaging technologies and increasing healthcare expenditure.
What factors are driving the growth of the medical imaging market in the UAE?
Which cities in the UAE are leading in the medical imaging market?
What are the main types of medical imaging products available in the UAE?
Other Regional/Country Reports
Other Adjacent Reports
Egypt Diagnostic Equipment Market
Oman Medical Devices Market Size, Share & Forecast, By Product Type, Care Setting & End User, 2025-2032Vietnam Healthcare IT Solutions Market
Global Telemedicine Market Report Size, Share, Growth Drivers, Trends, Opportunities & Forecast 2025–2030KSA Artificial Intelligence in Healthcare Market Size, Share & Forecast, By Solution Type, Deployment Model & Application, 2026-2031Belgium Oncology Diagnostics Market
Brazil Cardiology Equipment Market
Saudi Arabia In-Vitro Diagnostics Market Outlook to 2030Thailand Radiology Services Market
Kuwait Teleradiology Market Report Size Share Growth Drivers Trends Opportunities & Forecast 2025–2030Why Buy From Us?

What makes us stand out is that our consultants follow Robust, Refine and Result (RRR) methodology. Robust for clear definitions, approaches and sanity checking, Refine for differentiating respondents' facts and opinions, and Result for presenting data with story.

We have set a benchmark in the industry by offering our clients with syndicated and customized market research reports featuring coverage of entire market as well as meticulous research and analyst insights.

While we don't replace traditional research, we flip the method upside down. Our dual approach of Top Bottom & Bottom Top ensures quality deliverable by not just verifying company fundamentals but also looking at the sector and macroeconomic factors.

With one step in the future, our research team constantly tries to show you the bigger picture. We help with some of the tough questions you may encounter along the way: How is the industry positioned? Best marketing channel? KPI's of competitors? By aligning every element, we help maximize success.

Our report gives you instant access to the answers and sources that other companies might choose to hide. We elaborate each steps of research methodology we have used and showcase you the sample size to earn your trust.

If you need any support, we are here! We pride ourselves on universe strength, data quality, and quick, friendly, and professional service.